
SALOMON Golden Trail World Series Returns to the Great Wall
Source: PR Newswire
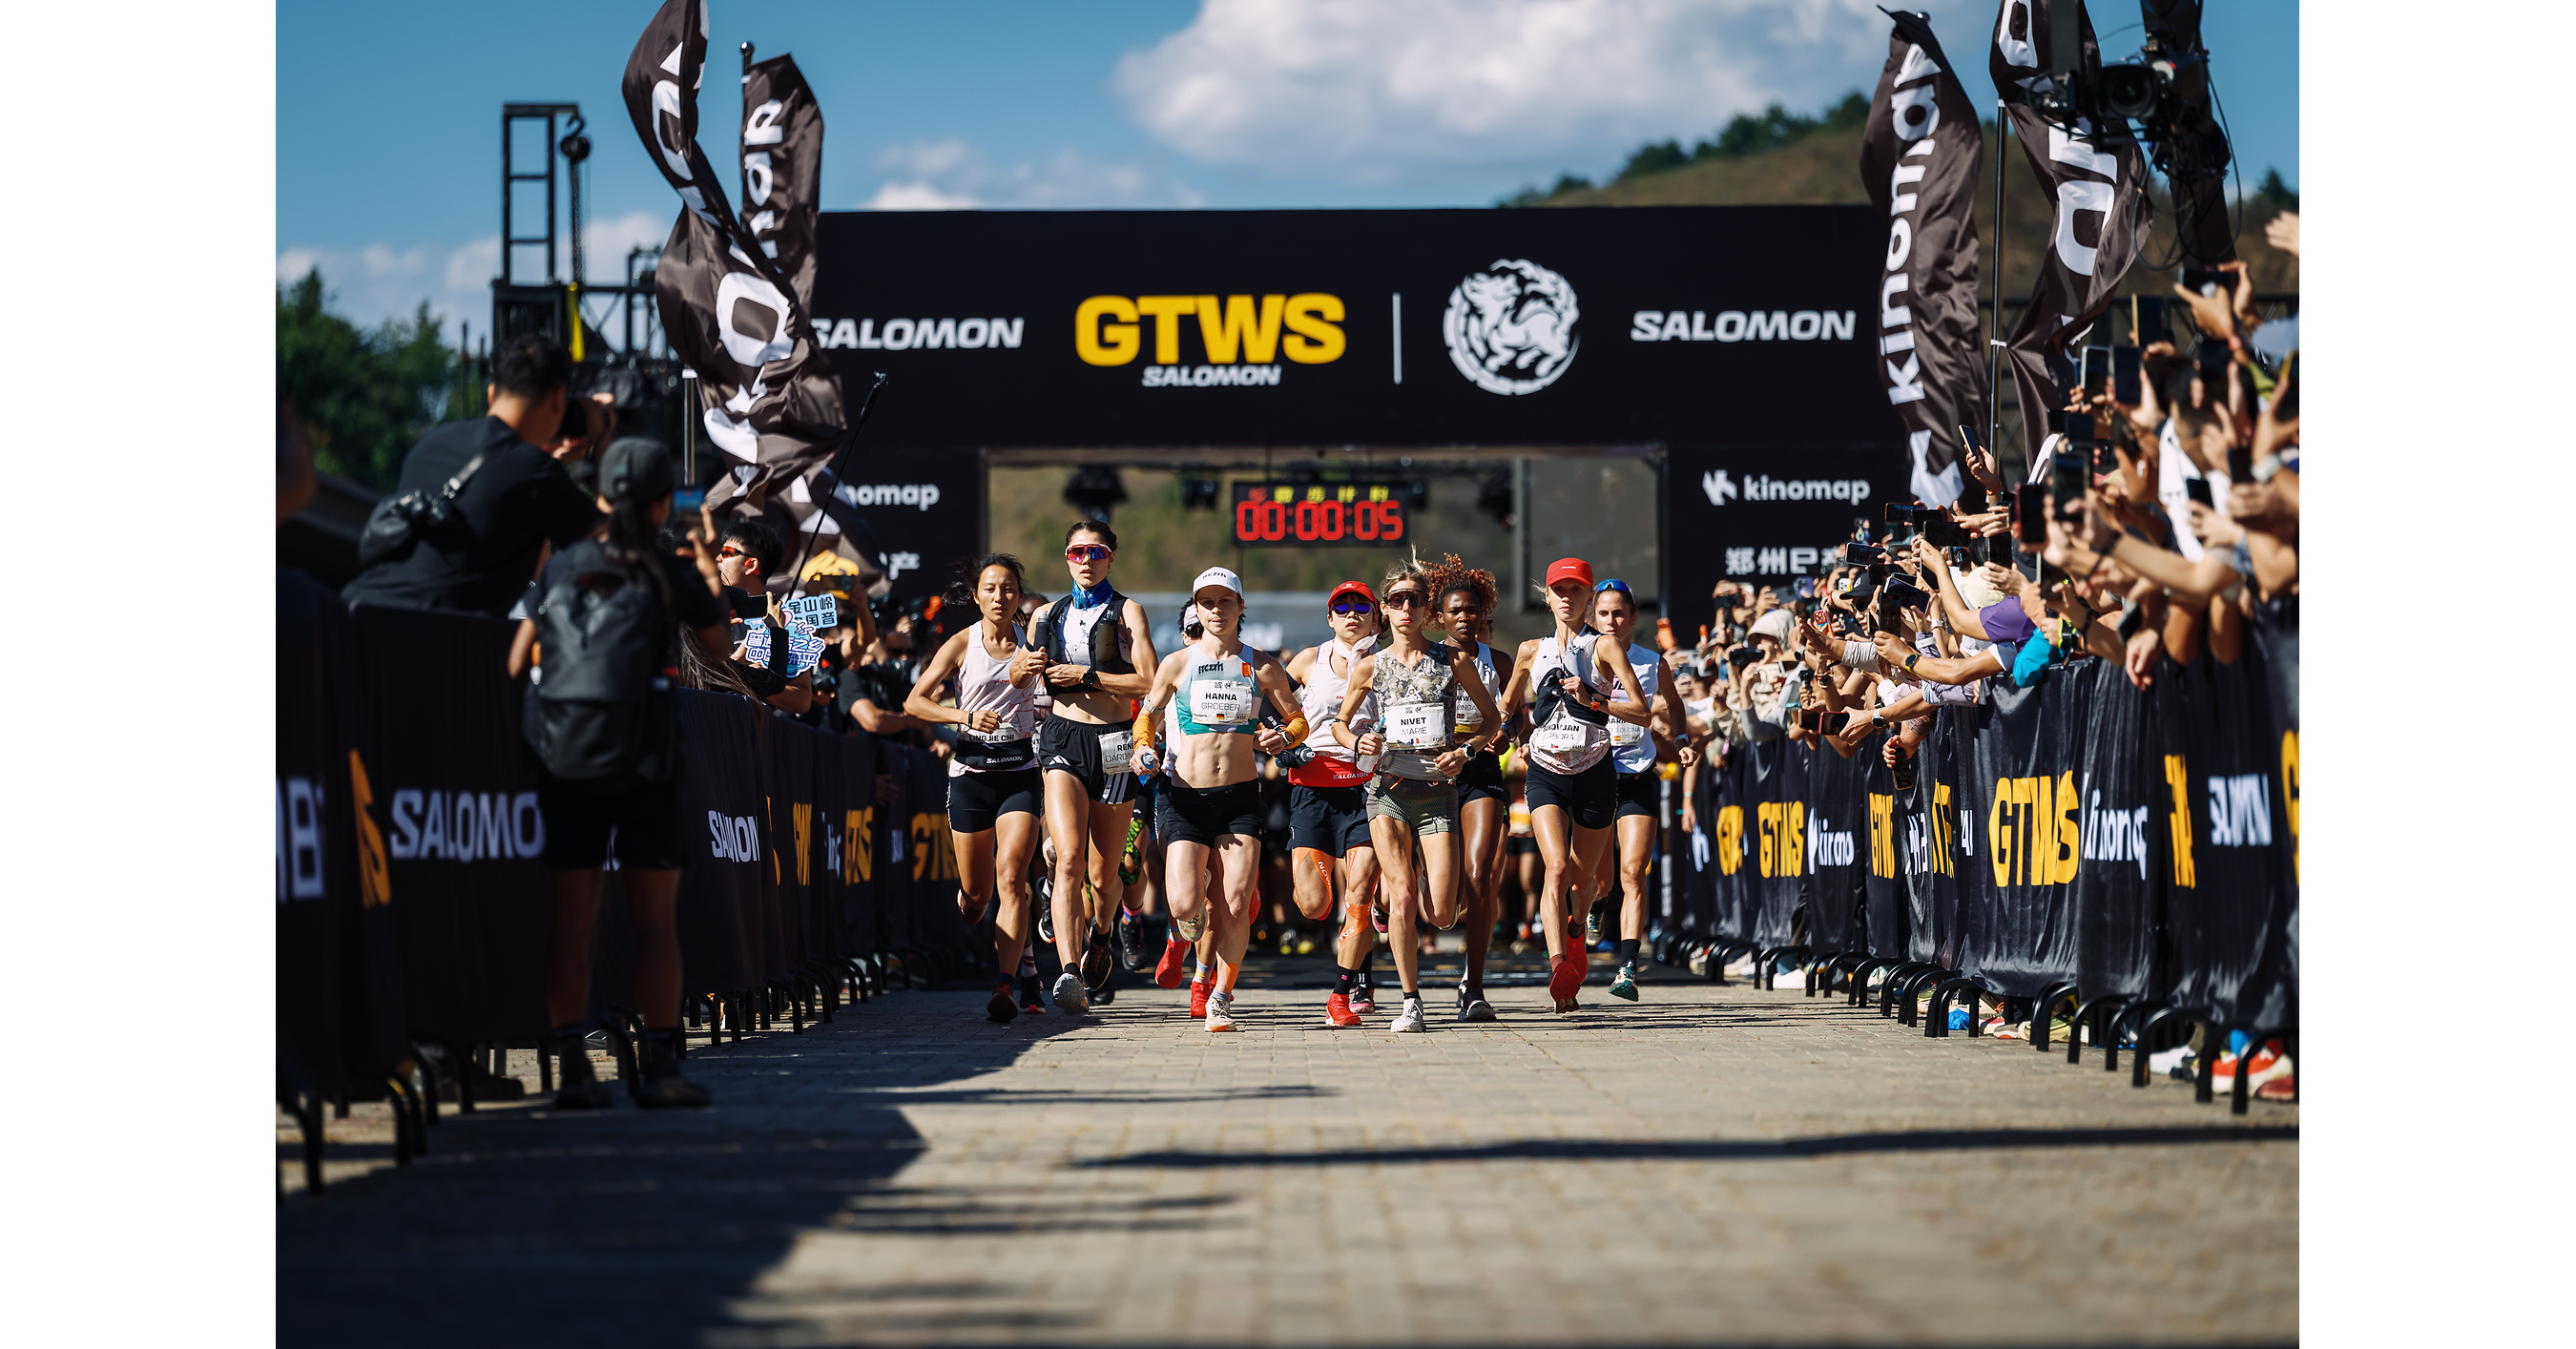
SALOMON's Jinshanling Great Wall Trail Race concluded as the penultimate points event of the 2026 Golden Trail World Series, featuring 36 elite runners and Team SALOMON leading the team ranking. Series prize money increased 50% from 2025 to €451,000, with €30,000 awarded to each men's and women's season champion. SALOMON is expanding the sport's Chinese presence through elite development, global broadcasting partnerships and strengthened anti-doping controls, but the announcement is unlikely to materially affect public markets.
Analysis
The investable read-through sits with Amer Sports (AS), not WBD. Repeated elite-event activation in China can improve Salomon's brand heat and premium footwear/apparel sell-through, particularly in specialist running channels where community credibility matters more than broad-based advertising. The financial effect is likely immaterial over the next quarter, but a sustained China race calendar and athlete-development pipeline could support Salomon's multi-year growth narrative, higher full-price mix, and lower reliance on wholesale promotion over 6-18 months.
WBD's distribution role is strategically useful but economically unproven. Niche endurance content may add low-cost sports inventory and localized digital engagement in China, yet it is unlikely to move affiliate, advertising, or streaming earnings without disclosed audience, sponsorship, or rights-fee data. The market should not capitalize this as a meaningful catalyst for WBD; its valuation remains dominated by leverage reduction, studio performance, and DTC profitability.
The contrarian risk for AS is that event spending is being mistaken for demand creation: elite participation and prize-pool escalation can raise marketing costs before they generate scalable consumer conversion. Watch China segment growth, Salomon wholesale orders, gross-margin trajectory, and inventory turns through the next two earnings reports. A slowdown in Chinese discretionary consumption or increased competition from ANTA (2020.HK), Li Ning (2331.HK), and premium outdoor brands would falsify the proposition that brand activation translates into durable share gains.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- No standalone WBD trade: treat this as a monitoring item until management discloses rights economics, audience scale, sponsorship revenue, or measurable DTC subscriber conversion. The likely earnings sensitivity is below materiality.
- Maintain or initiate a small 6-12 month long AS position only on broader consumer-discretionary weakness, using upcoming quarterly China growth and Salomon margin commentary as confirmation. The upside case is multiple support from sustained premium-brand growth; exit or reduce if Salomon growth decelerates for two consecutive quarters while promotional activity rises.
- Relative-value watch: long AS versus short 2331.HK or 2020.HK is only actionable if channel checks show Salomon gaining premium trail-running shelf space and full-price sell-through in China. This isolates international premium-brand momentum from domestic athletic-apparel demand; do not enter without evidence on orders or retail sell-through.
More News
- Paramount Skydance prices $42 billion debt for Warner Bros deal
- The new and huger Paramount has a new co-CEO
- US judge approves settlement allowing Paramount to acquire Warner Bros
- David Ellison names Ynon Kreiz co-CEO of Paramount and Warner Bros. Discovery
- US judge allows Paramount to close Warner Bros acquisition
- Paramount names Ynon Kreiz as co-CEO ahead of WBD merger