
Furniture China und Maison Shanghai 2026 gehen in den Endspurt
Source: PR Newswire
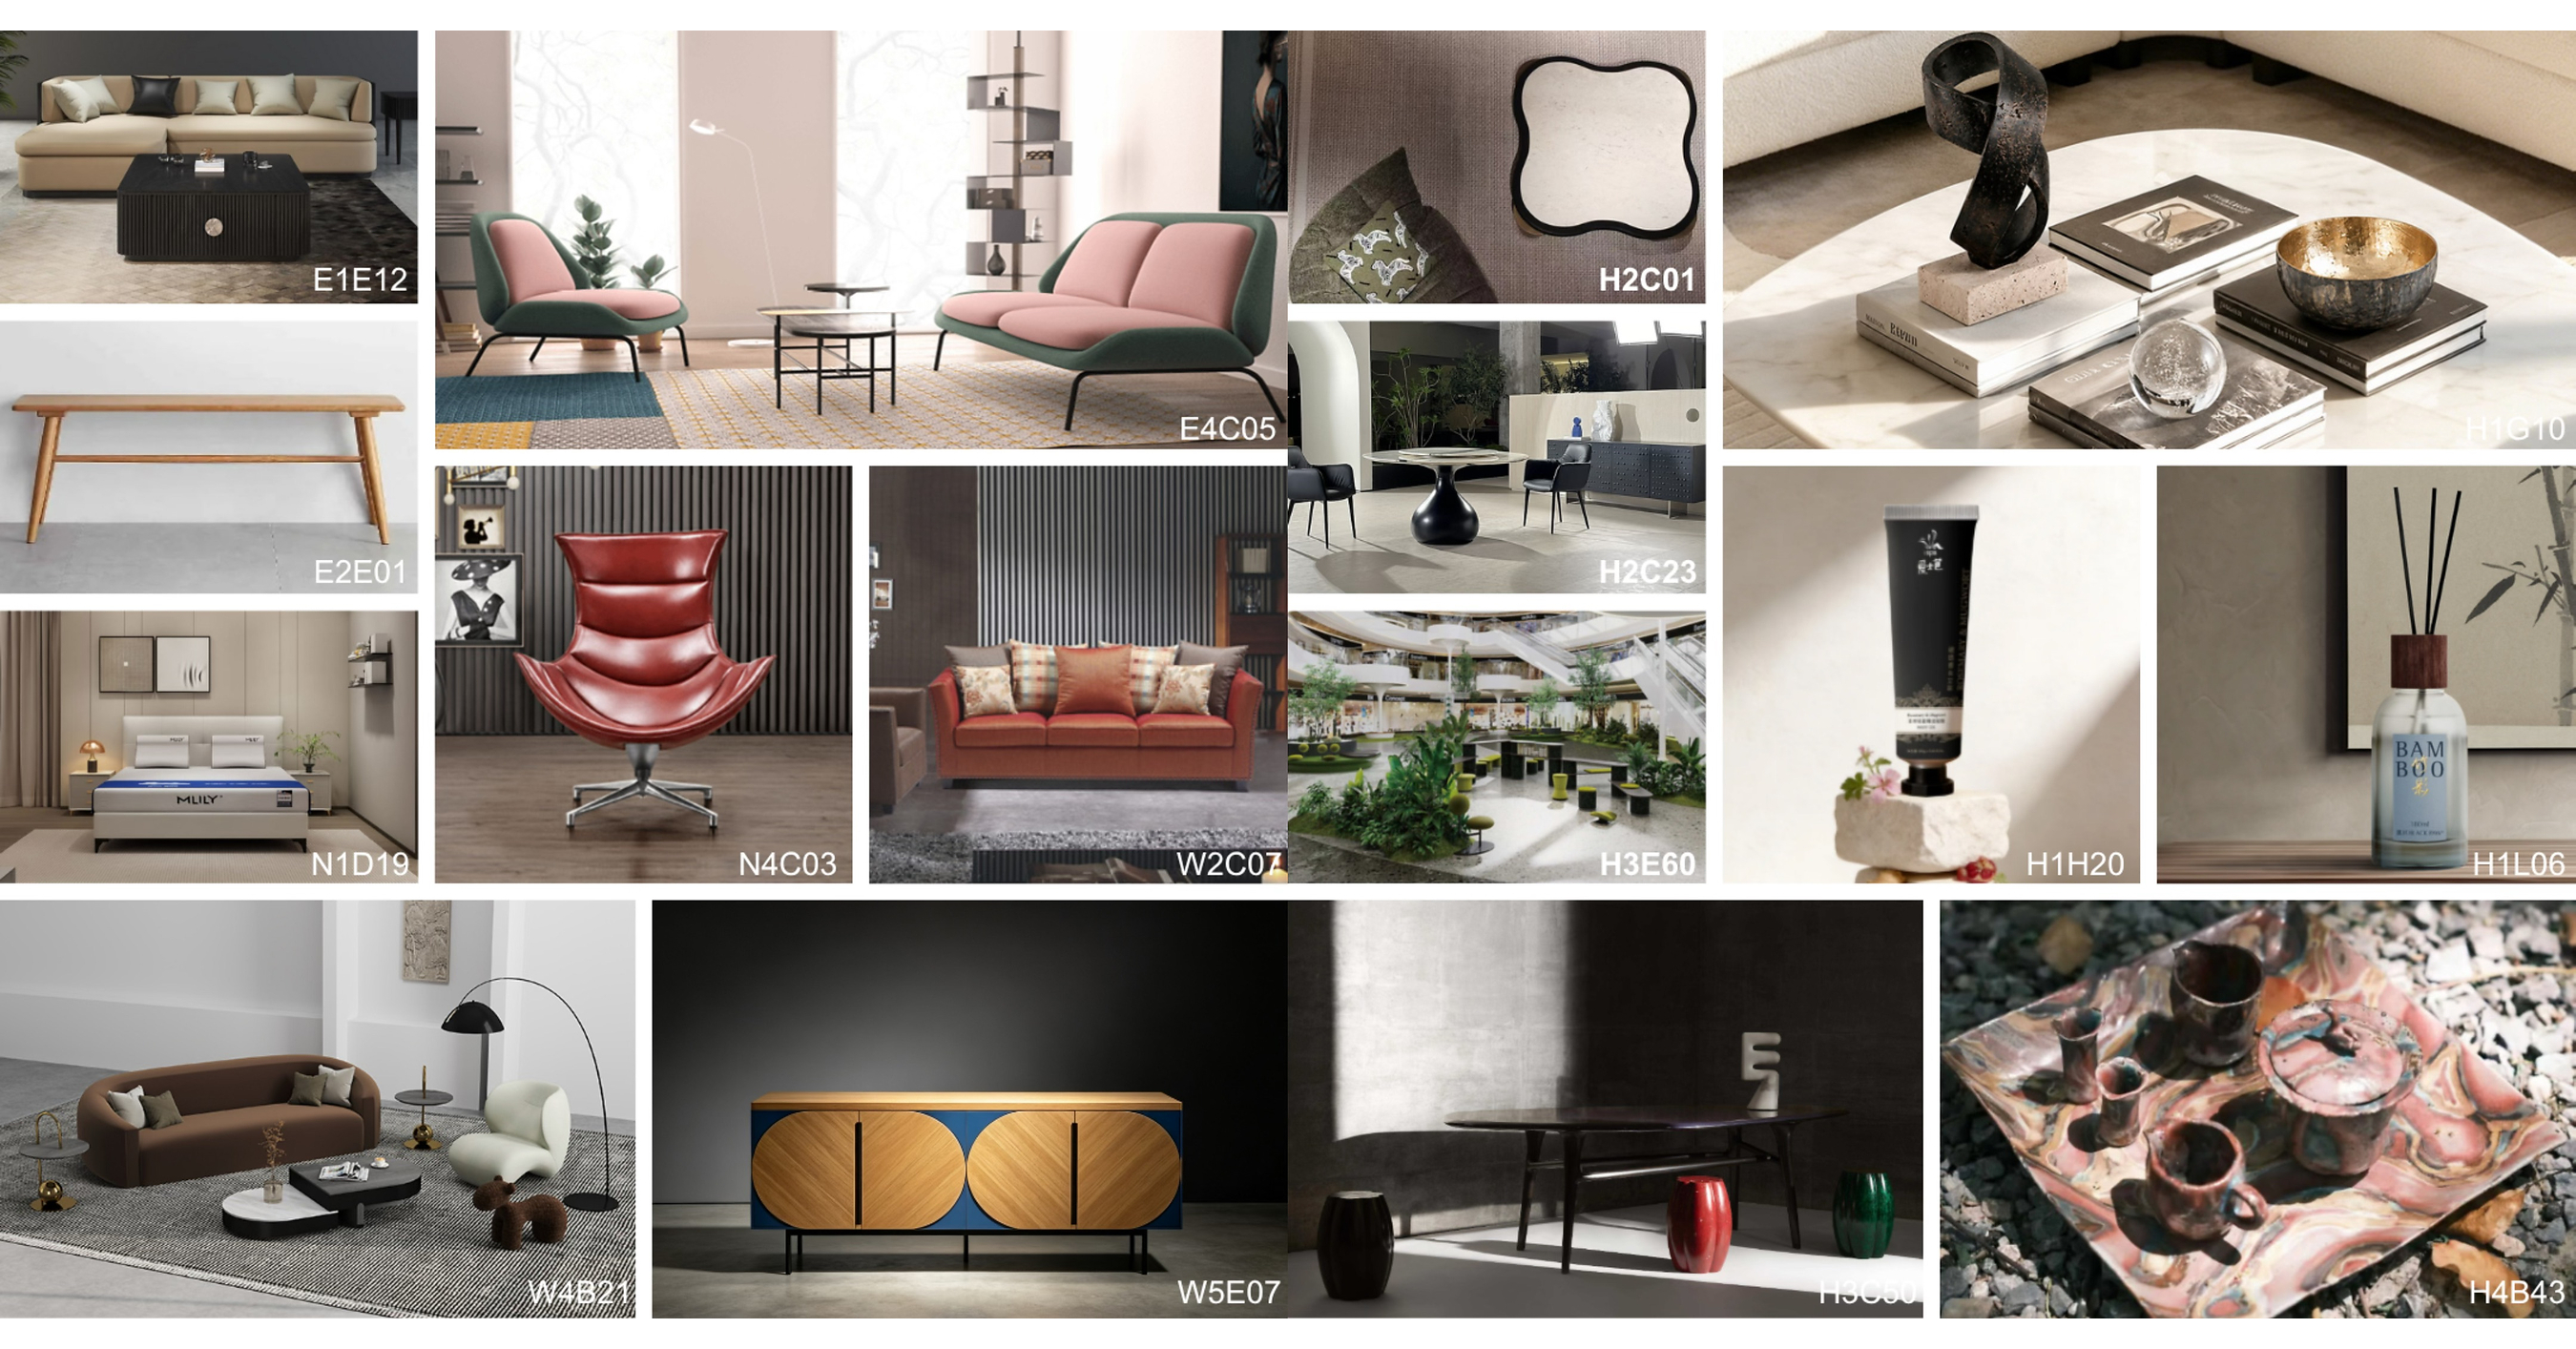
Furniture China (8–11 Sep, SNIEC) and Maison Shanghai 2026 (7–10 Sep, SWEECC) will host 3,200+ exhibiting brands across 350,000 m² with 200,000+ trade visitors expected, aiming to connect sourcing, manufacturing, design and business opportunities in one Shanghai trip. The combined shows cover furniture supply chain categories (including materials/components and outdoor/dining/commercial segments) and expand Maison Shanghai via 4 theme halls plus a design-program to showcase interior design and new market perspectives. Organizers also announced upgrades for overseas buyers, including relocation of the Overseas Buyer Lounge and scheduled DTS × Happy Hour sessions.
Analysis
This is more a sentiment check on China’s role in global sourcing than a tradable equity catalyst. The economic signal only matters if buyer attendance converts into purchase orders over the next 1-3 months; otherwise it is just a noisy lead indicator. The only plausible listed read-through is a marginal lift to cross-border travel and card spend for V/MA, but the revenue delta would be immaterial versus their quarterly base.
Second-order winners are upstream: freight forwarders, logistics intermediaries, and contract manufacturers that can turn showroom traffic into Q4 shipment volume. If foreign participation is robust, it argues buyers are still willing to source from China despite tariff and diversification pressure; if participation is soft, it strengthens the China+1/nearshoring trade and weighs on China-exposed industrial sentiment. In either case, the effect is much more likely to show up in export/order data and small-cap supplier sentiment than in large-cap U.S. payment names.
The key risk is that event marketing overstates commercial impact. Visa support, hotel deals, and buyer lounges improve conversion at the margin, but they do not change end-demand or tariff policy. What would falsify any bullish read-through on China sourcing is a weak post-event order book, weaker export prints, or fresh tariff escalation that pushes buyers to accelerate supplier diversification.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.08
Key Decisions for Investors
- Do not initiate a standalone position in V or MA on this headline; the implied uplift from a furniture sourcing event is too small to matter. Reassess only after the next monthly cross-border spend print or management commentary on travel-related volumes.
- If looking for an actionable proxy, wait for confirmation from post-event order data before considering a small long in FXI or a China export basket. Without hard order conversion, the risk/reward is poor and the move should be faded.
- Watch BKNG and TCOM into the Shanghai booking window as a very short-duration travel-spend tell. Trade only if hotel/airfare bookings show a measurable surprise; otherwise there is no edge and the event should be ignored.
- Set an alert on Chinese export and tariff headlines over the next 1-3 months. A negative tariff or order-flow surprise would be the cleanest falsifier for any China sourcing rebound thesis.
More News
- Pilot killed in attacks by Iran-backed Houthis on Riyadh airport; Saudi-led coalition vows 'firm' response
- Delta Air Lines cuts 2026 forecast on fuel surge, but CEO says demand is still strong
- Is AI the new China Shock?
- Why is T-Mobile stock tumbling today?
- Wall St futures gain as oil slips; telecoms pressured by SpaceX spectrum deal
- OpenAI projected to bring in $20bn less in revenue than expected