
Agthia Reports Revenue Growth Amid Challenging Cost Environment
Source: PR Newswire
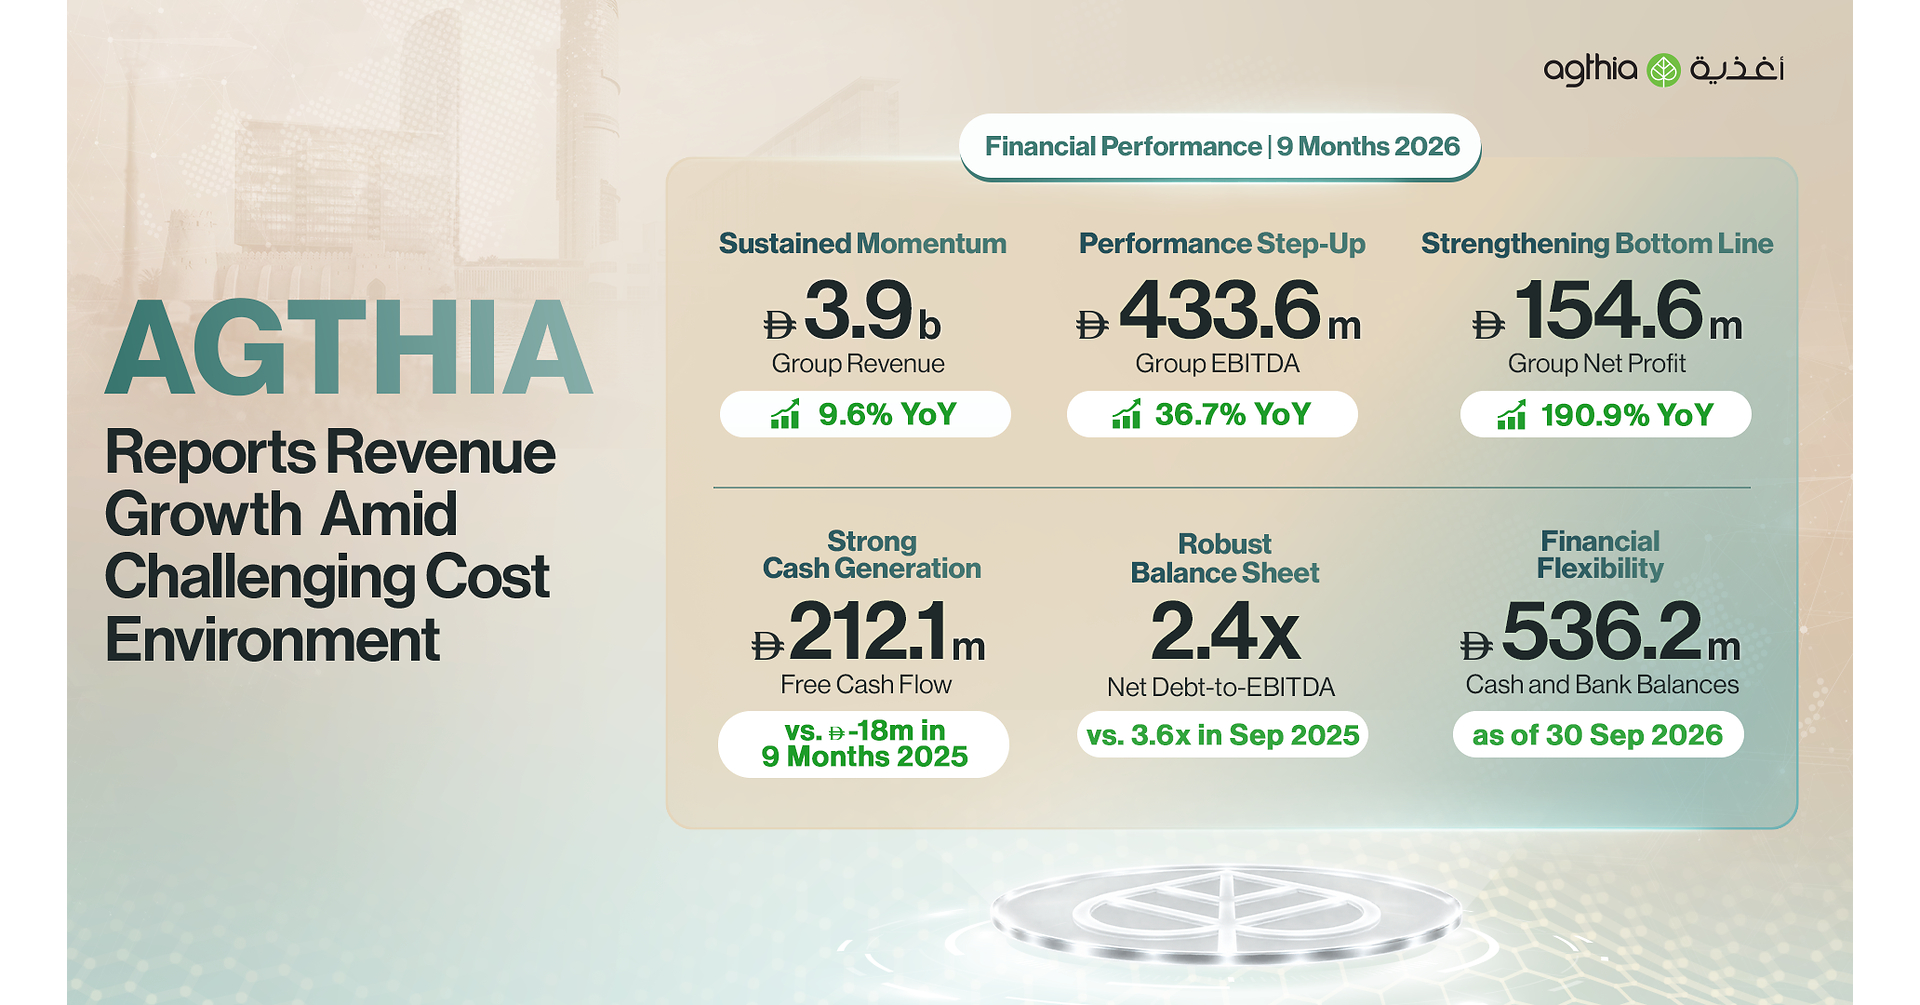
Agthia’s Q3 2026 revenue rose 14.4% year on year to AED 1.3 billion, including AED 104.7 million in one-off sales; underlying growth was 5.2%. EBITDA increased 39.0% to AED 123.1 million, while net profit reached AED 33.2 million versus AED 4.1 million a year earlier, which included Snacking impairment charges. Nine-month free cash flow was AED 212.1 million and net debt-to-EBITDA improved to 2.4x from 2.9x, although higher input, freight and distribution costs pressured segments and regional logistics disruptions affected exports.
Analysis
The earnings quality is more mixed than the headline profit growth suggests: reported revenue includes one-off food-security sales, while the prior-year profit comparison is distorted by Snacking impairment charges. The key near-term question is whether EBITDA improvement persists on core volumes and repeatable cost savings, not whether reported growth remains high. Segment dispersion matters: Agri-Business shows that volume growth can destroy value when input and distribution costs outrun pricing; Water faces a similar, though less severe, PET and freight squeeze. Conversely, Snacking’s margin recovery could become a durable group earnings driver if the reset holds, but store growth and share gains need to convert into cash rather than expansion costs.
Over the next 1–3 months, logistics and input-cost trends, plus the recurrence of exceptional sales, are the main catalysts. Over 6–18 months, the thesis depends on pricing power, the Saudi protein facility’s utilization, and sustained Snacking execution. Improved free cash flow and lower leverage provide a buffer, but do not eliminate exposure to renewed working-capital needs or cost inflation. Contrarian angle: investors may over-credit the sharp earnings rebound and underweight the segment-level margin split. Without valuation, consensus, and segment cash-flow data, there is insufficient basis for a directional valuation call.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- Avoid chasing the reported earnings acceleration immediately; treat one-off revenue and the impairment-affected comparison as reasons to wait for a cleaner read-through.
- Set a 1–3 month alert for core revenue growth excluding exceptional sales, group EBITDA conversion, and Agri-Business margin stabilization. A further margin decline despite feed-sales growth would weaken the transformation case.
- Consider a conditional long thesis only if subsequent results show Snacking margin gains persisting and improved group cash generation without renewed leverage deterioration; verify segment cash flows and the contribution of one-off sales first.
- Falsification checks: renewed PET, freight, or agricultural-input inflation; weaker repeat business after food-security sales; or a reversal in free cash flow/net debt-to-EBITDA. No price target or relative-value trade is justified without valuation and peer data.
More News
- NextDC shares surge 43% after Goodman, Digital Realty stake purchases
- Qualcomm issues disappointing earnings forecast as memory shortage weighs on smartphone sales
- China Blocks SoftBank Acquisition of ABB Robot Unit, FT Says
- ‘Seismic’ blue wave triggers the sinking of oil prices, energy stocks, and the chances of power permitting reform
- Softbank’s $5.4 bln takeover of ABB robotics unit blocked by China- FT
- Inside the chip talent war: Trade secrets and rising Chinese rivals