
GAC lance l'AION UT au Danemark et en Norvège, parallèlement à des essais routiers en Autriche
Source: PR Newswire
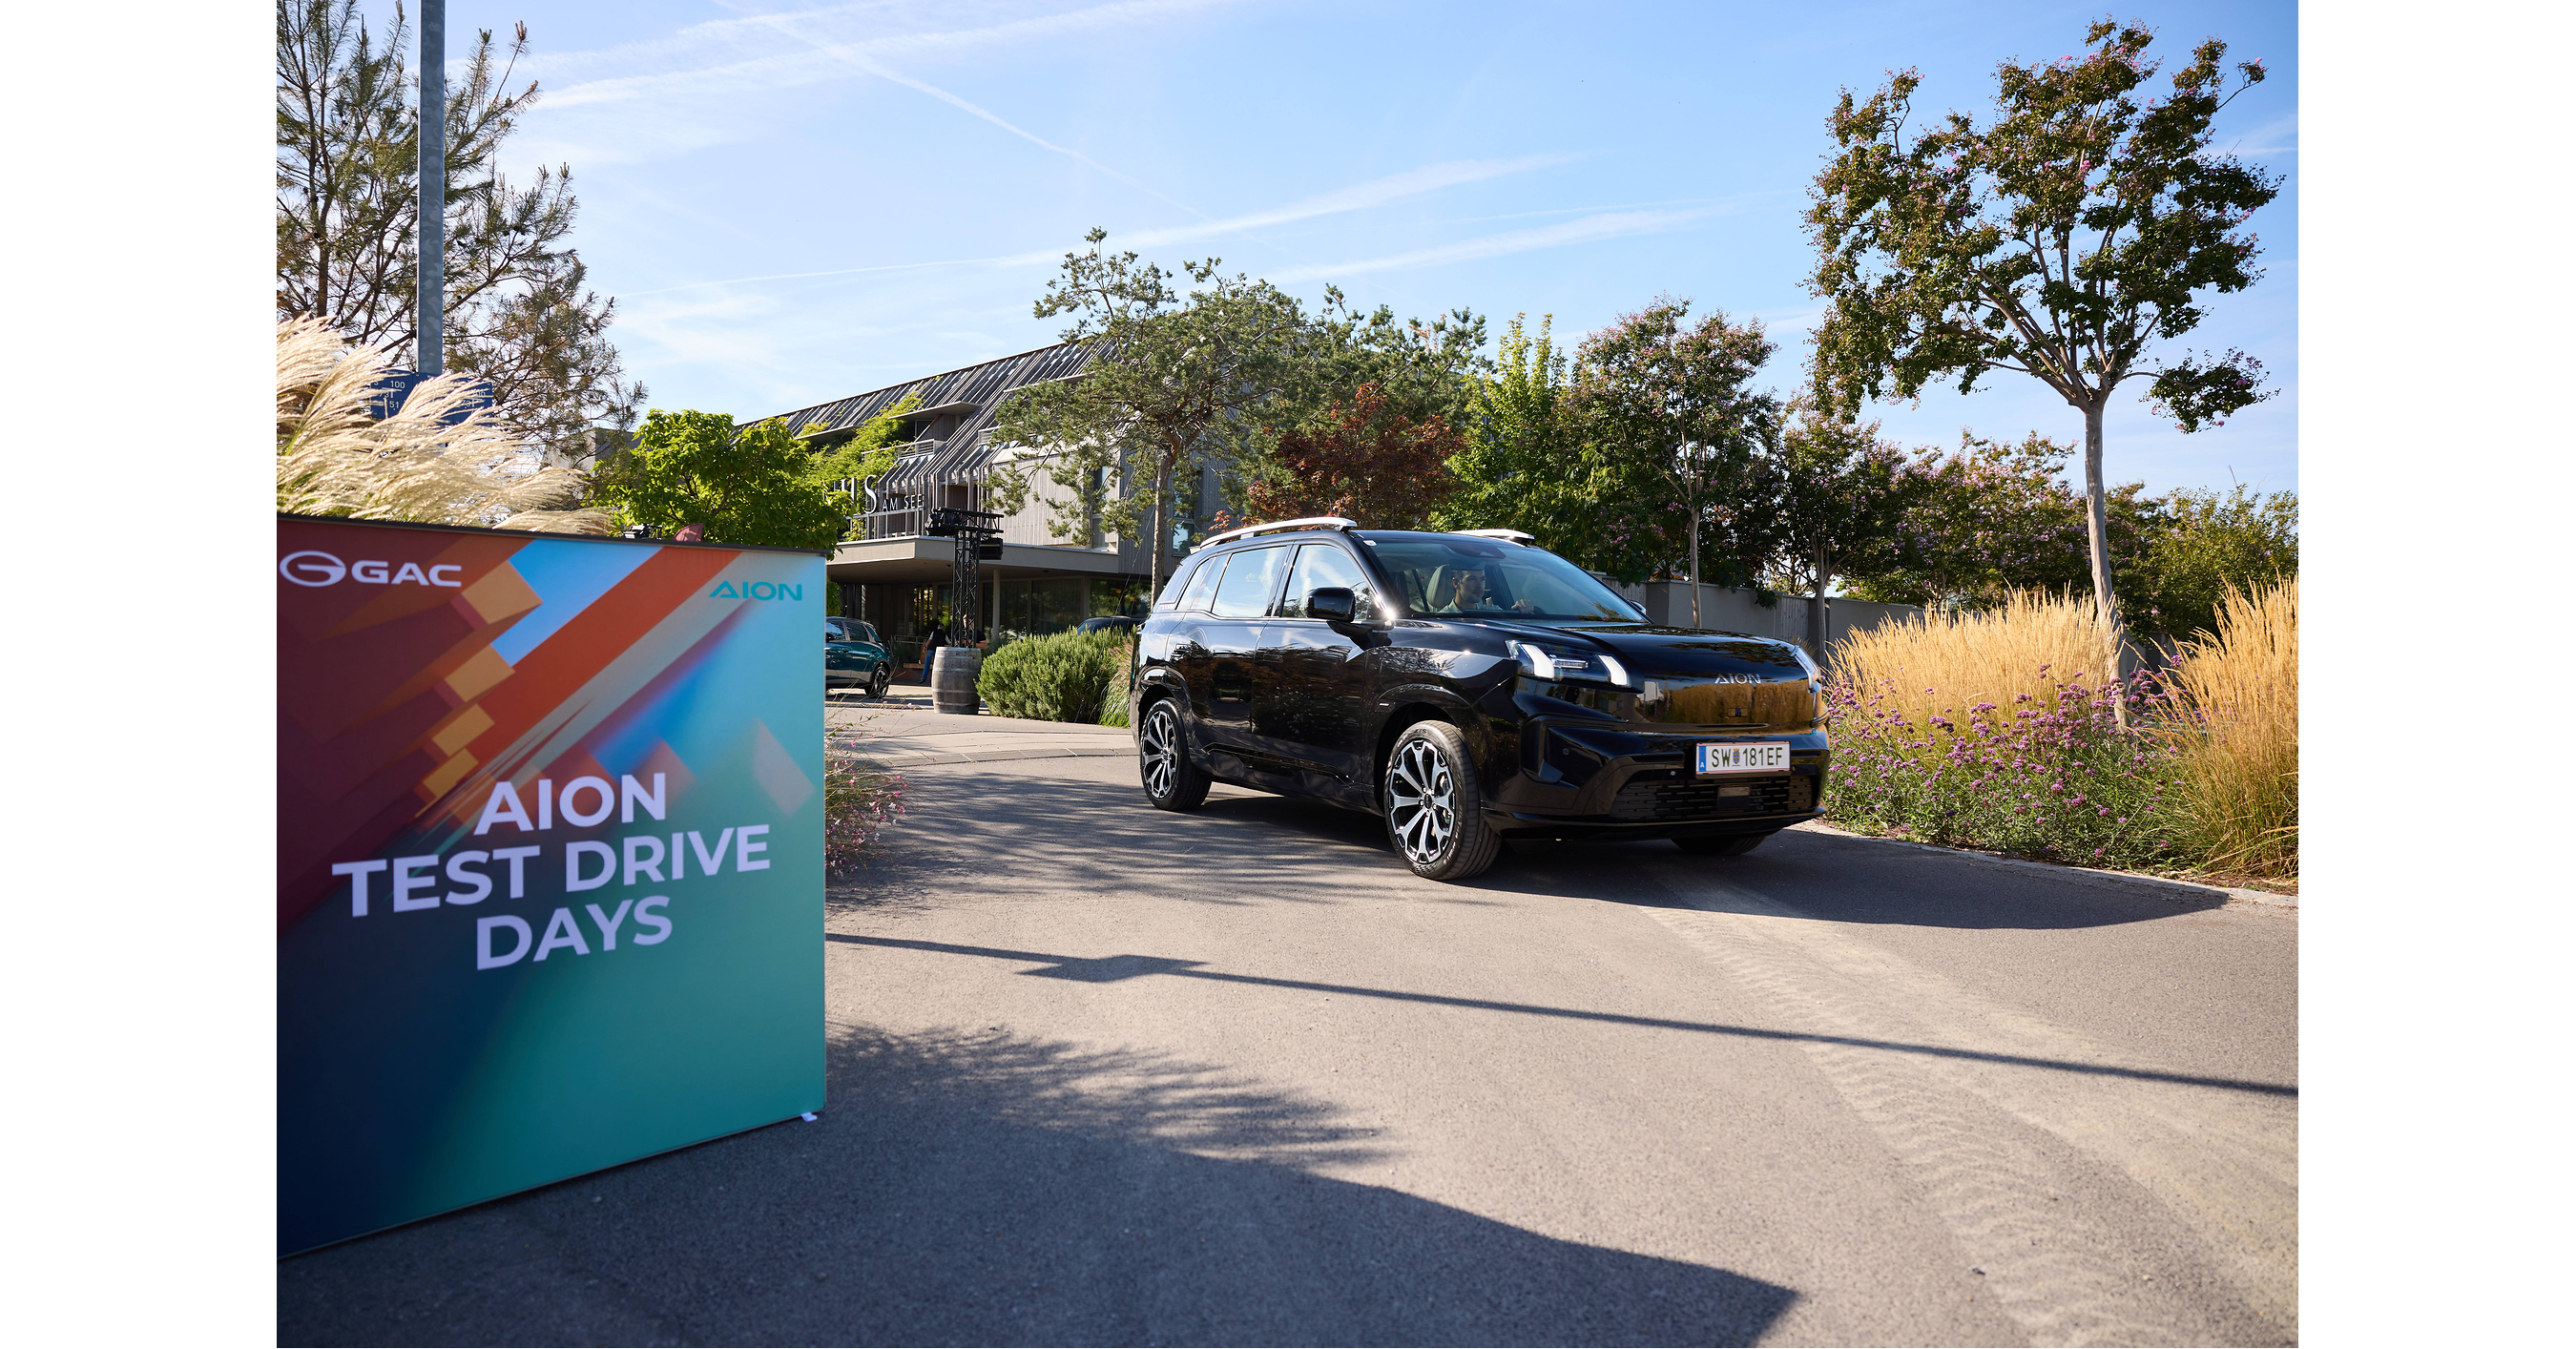
GAC launched its AION UT compact electric hatchback in Denmark and Norway and held public road tests for the AION UT and AION V in Austria, advancing its European market rollout. The AION UT offers up to 430 km of WLTP range, 440 liters of cargo capacity, a 14.6-inch infotainment display and a five-star Euro NCAP 2026 rating. GAC is supporting the expansion through Milan-based design, Austrian vehicle assembly, Amsterdam coordination and Rotterdam parts logistics, alongside local distributor partnerships.
Analysis
This is not investable for AAPL; the data correctly assigns no direct earnings sensitivity. The relevant market mechanism is incremental price and feature competition in European B/C-segment EVs, where a Chinese entrant with localized distribution can pressure residual values, dealer economics and promotional spending before it meaningfully affects incumbent unit share. The absence of disclosed pricing, dealer commitments, homologation economics and initial order intake means the announcement is evidence of market-entry intent rather than a demand datapoint.
Over the next 1-3 months, monitor published Danish/Norwegian pricing versus Renault 5, VW ID.3, Volvo EX30 and BYD Dolphin, plus financing APR and fleet tenders. A material undercut—roughly 10-15% below comparable European alternatives after incentives—would most likely force discounting at volume-oriented European OEMs rather than premium brands; the first-order equity risk is lower 2027 European auto margin expectations, not an immediate sales shock. Norway is an unusually poor read-through for continental Europe because EV penetration is mature and fiscal policy dominates purchase behavior.
The more important 6-18 month issue is whether localized assembly and parts logistics qualify the platform for favorable tariff treatment or simply add fixed cost to low-volume operations. If GAC achieves credible after-sales coverage and fleet adoption, Chinese competition broadens from pricing to warranty, software and residual-value pressure—negative for Stellantis and Renault valuation multiples, while potentially positive for European auto retailers/service networks that gain marques without taking manufacturing risk. Conversely, EU trade enforcement, weak parts availability, or subscale dealer throughput would rapidly impair consumer trust and make this another costly European launch rather than a durable share-gain story.
Contrarian view: incumbent EV weakness is already widely attributed to Chinese imports, but small launches do not automatically translate into registrations. European buyers place disproportionate weight on repair networks, leasing residuals and financing; without independently observable fleet/lease partners, the likely near-term effect is marketing noise rather than a catalyst for broad OEM estimate cuts.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No action in AAPL: maintain neutral exposure; this development has no identifiable revenue, supply-chain or valuation linkage to Apple.
- Place a 1-3 month watch on STLA and RNO: consider a tactical short basket only if GAC posts retail pricing at least 10-15% below Renault 5/ID.3 equivalents and discloses funded dealer or fleet commitments. Target 5-8% downside on incremental European margin de-rating; cover if pricing is near incumbents or registration data remain immaterial.
- For a cleaner competitive hedge, monitor long AUTO.L versus short STLA/RNO after dealer-network confirmation. A retailer can benefit from incremental brands and service activity, while OEMs bear price competition; invalidate the pair if GAC uses a direct-sales model or dealer economics are not disclosed.
- Do not extrapolate from Norwegian launch activity to EU-wide demand. Require 3-6 months of registration, lease-residual and parts-service data before treating this as a structural short catalyst for European autos.
More News
- Meta nears first new high in a year as Muse success showcases winning AI strategy
- Meet Feather, the startup building the ‘Android of robotics’ for developers
- Tesla's Q3 Sales Report Comes Out Oct. 2. Here Are 2 Surprises It Might Reveal.
- The virtual reality Meta is pitching is one where we're not always relying on our iPhones
- Qualcomm's Snapdragon Sound Elite is a new AI chip for audio wearables
- Tesla's Roadster Reveal Is Oct. 1. The Real Story Is Optimus.