
Moldova eGovernance Agency führt Nutzung nach europäischen Standards entwickelter digitaler EVO-Identitätsnachweise im Bankwesen ein
Source: PR Newswire
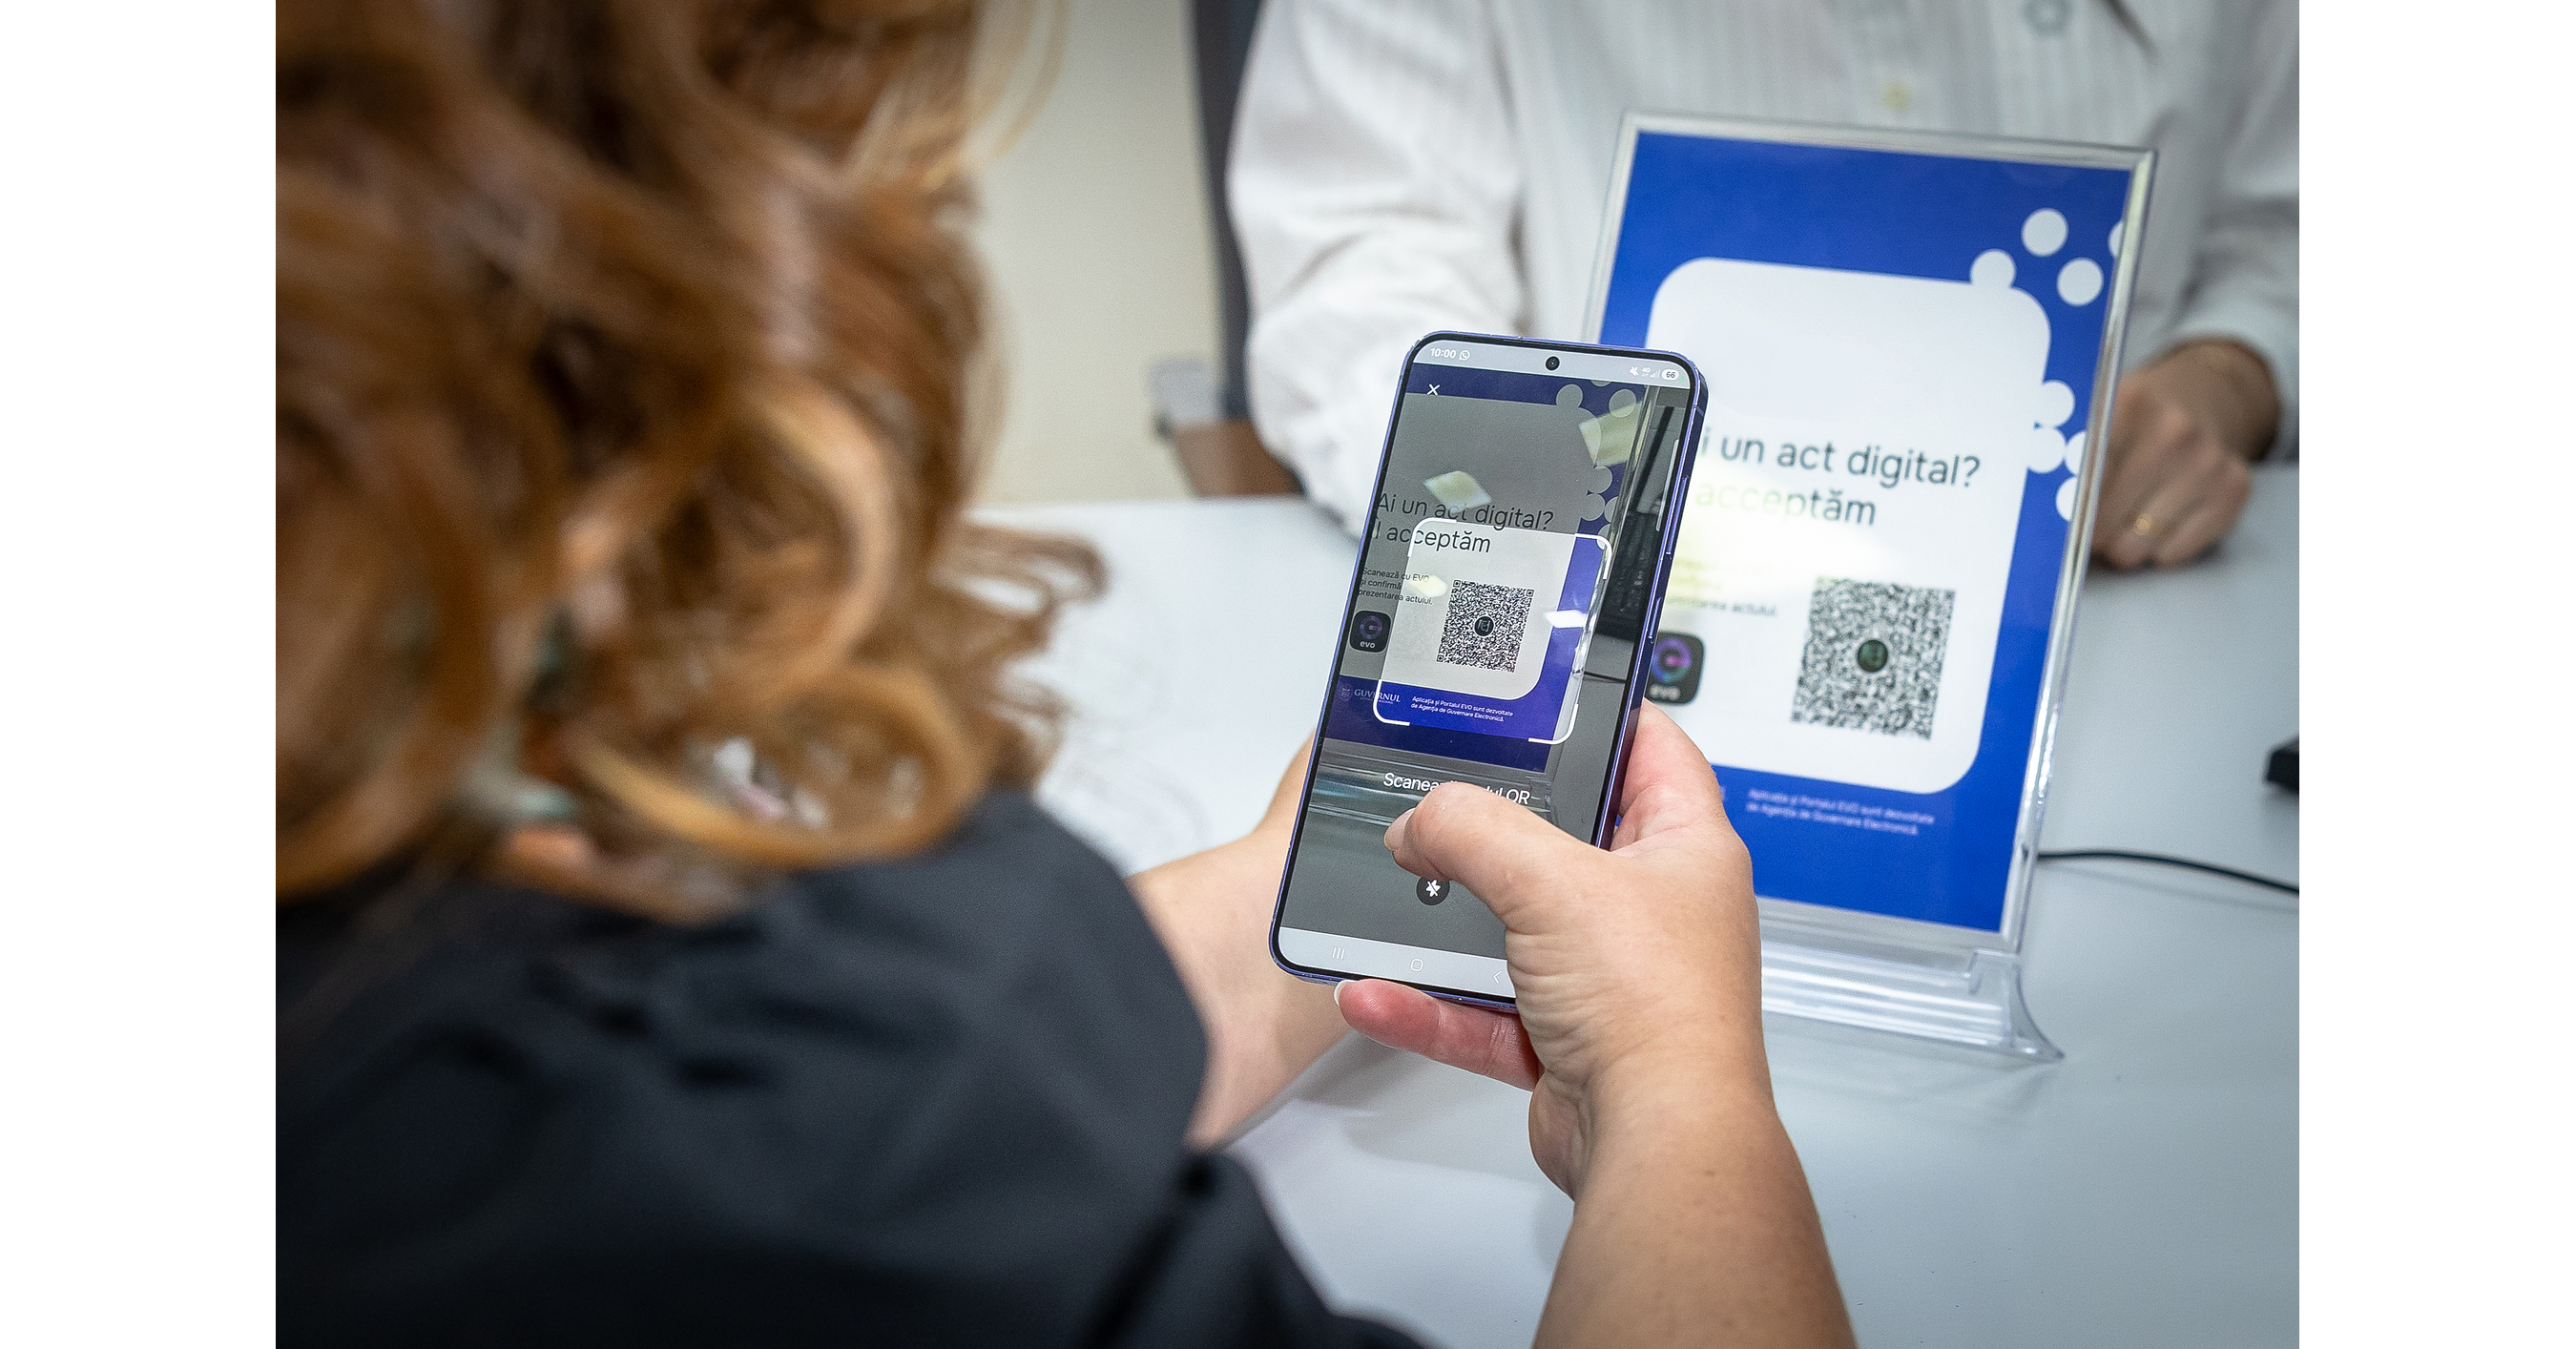
Moldova's EVO digital-identity credentials are now accepted by four banks—Moldindconbank, FinComBank, EuroCreditBank and Victoriabank—enabling customer identification through QR-code-based, consented data sharing. Since opening integrations on April 1, 2026, EVO has expanded to 30 prospective relying parties, including a major telecom operator and the National Bank of Moldova, with at least 20 organizations targeted for live deployment by year-end. The initiative aligns Moldova's digital-ID infrastructure with EUDI Wallet standards and supports eventual cross-border interoperability with European systems.
Analysis
NBHC has no discernible Moldova or European digital-identity revenue exposure; the tagged linkage is non-actionable. The relevant investable implication is indirect: standardized reusable credentials can lower customer-acquisition and manual-KYC costs for smaller banks, but those savings will be immaterial to listed European banks until wallet acceptance scales beyond pilot integrations and regulators permit broader reliance for higher-risk onboarding and credit products.
Over the next 1-3 months, this is principally an execution signal for private regional banks and government IT vendors rather than a public-equity catalyst. The 6-18 month second-order risk is disintermediation of incumbent onboarding workflows: telecoms, payment firms and banks with proprietary identity stacks may lose differentiation as identity becomes a portable public utility, while fraud losses could rise if relying-party controls, credential revocation, and device-security standards are uneven. The company-issued framing provides no adoption, cost-savings, transaction-volume, or fraud-performance data, so there is no basis to capitalize a financial benefit.
Contrarian view: interoperability is often mistaken for immediate cross-border commercial utility. Actual monetization depends on legal recognition, liability allocation after authentication failures, and merchant integration economics; these frictions commonly delay volume adoption well beyond technical testing. A meaningful thesis would require evidence of active-user penetration, repeat verification volumes, and measurable reductions in bank onboarding time or compliance expense.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No position in NBHC: treat the ticker association as spurious absent disclosed Moldova, EUDI-wallet, or identity-platform exposure.
- Maintain a 6-12 month watchlist on European payments/identity infrastructure beneficiaries rather than buy on this announcement; require reported production transaction volumes and signed commercial pricing before underwriting revenue upside.
- For European banks with material CEE exposure, monitor onboarding-cost disclosure and fraud-loss trends at the next two earnings cycles. A verified reduction in cost-to-acquire or KYC operating expense, without a deterioration in fraud provisions, would support a selective long bias; rising fraud or regulatory liability would falsify it.
- Do not use options or directional fintech exposure on this signal alone; the missing data on adoption and economics makes expected catalyst timing too indeterminate.
More News
- Ryanair CEO warns fares could rise by up to 20% in 2027 as fuel bill jumps by $2.2 billion
- The AI trade has broken down. How we got here and what investors should expect next
- Bitcoin pinned at $78k after October losses; Binance resumes withdrawals
- NUBURU Completes Tekne Acquisition, Adding a $93 Million Defense & Dual-Use Program Portfolio and Advancing Expansion Across NATO and Allied Markets
- Aehr Test Systems earnings on deck amid AI chip boom
- SpaceX in talks to buy Boost Mobile or use its network, Washington Post reports