
2027 SUBARU OUTBACK DELIVERS AFFORDABILITY WITH NEW PRICING, NEW OUTBACK ENTRY-LEVEL MODEL STARTING AT $32,995 MSRP
Source: PR Newswire
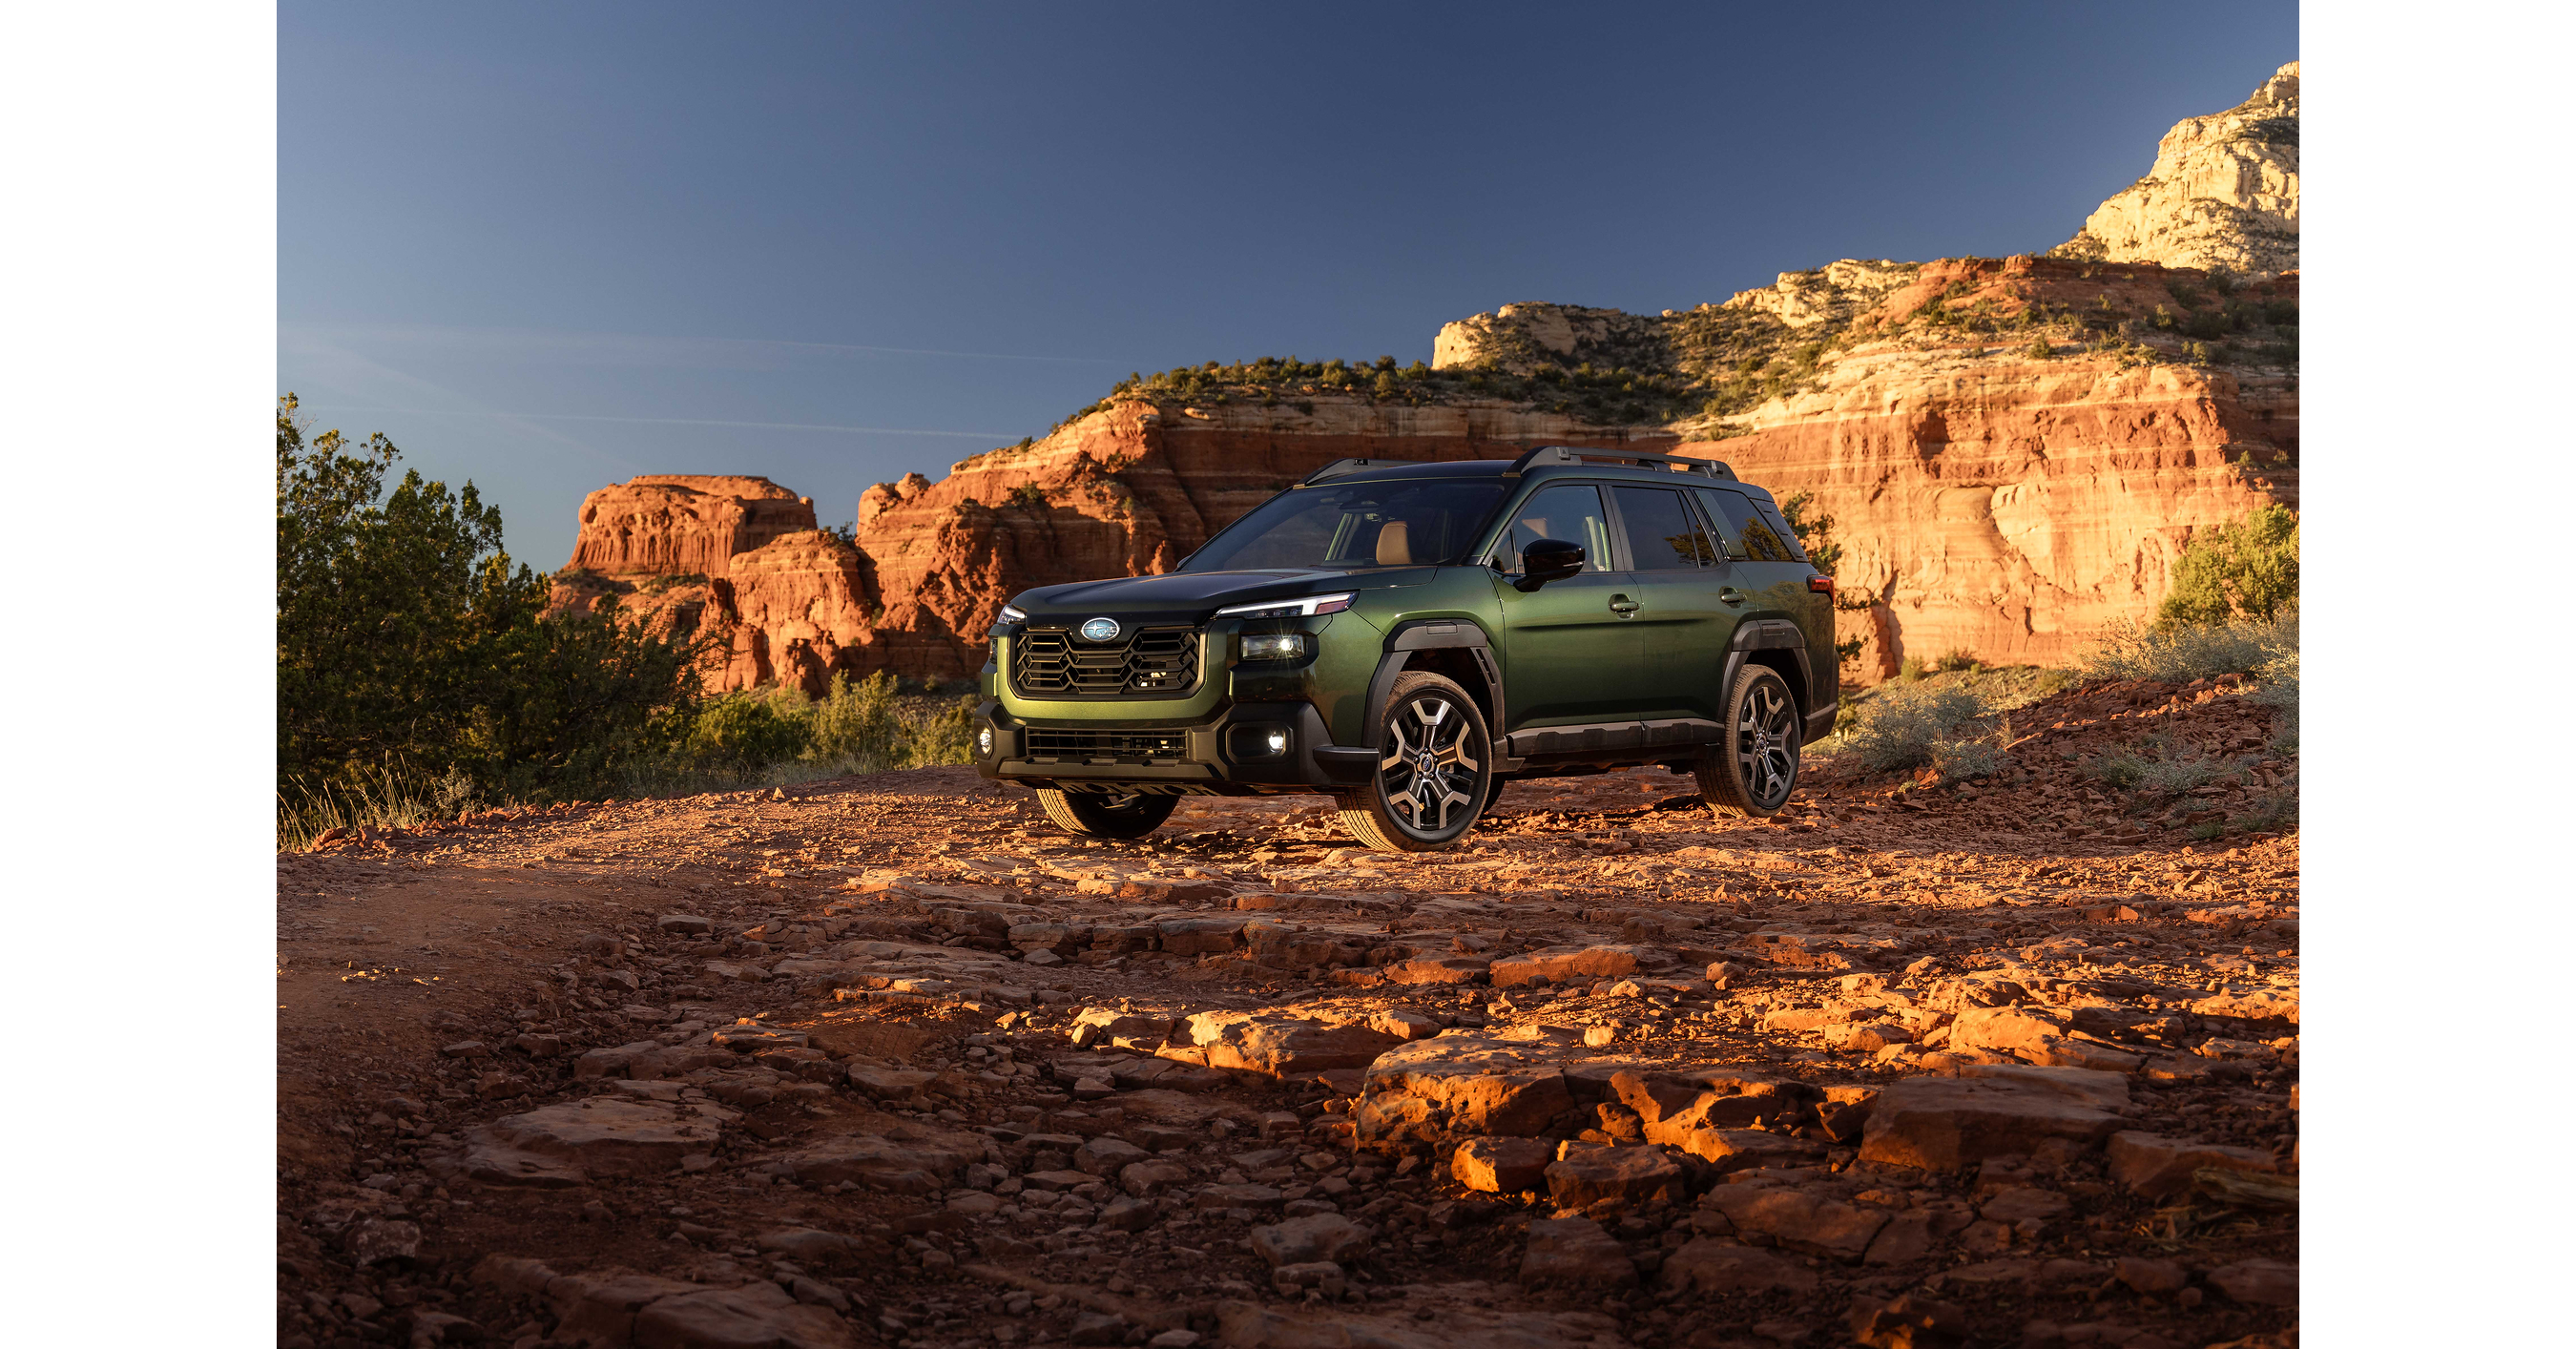
Subaru priced the 2027 Outback lineup from $32,995, lowering the entry price by $2,000 versus the 2026 model and adding more standard equipment, including a 12.1-inch touchscreen, 12.3-inch digital instrument cluster and driver-assistance features. Prices are down an average of $1,000 across most trims; listed reductions include $1,720 for Limited and $1,900 for Touring. The vehicle is expected at U.S. retailers later this year.
Analysis
This is a competitive pricing signal, not a standalone earnings catalyst. The lower entry point may defend Subaru’s share among budget-conscious crossover buyers, but richer standard equipment alongside lower prices shifts the near-term question to unit economics: whether added content is offset by lower component costs, better utilization, or enough incremental volume. If not, the mix of lower-priced vehicles and reduced trim pricing could dilute revenue per unit and pressure margins. More aggressive value positioning may also force Toyota and Honda to defend comparable offerings with incentives, spreading pressure across the segment rather than creating a durable Subaru advantage.
The key near-term read-through is dealer execution as vehicles arrive: realized transaction prices, incentives, and inventory turns matter more than announced MSRP. Over 1–3 months, watch delivery pace and any competitor incentive response; over 6–18 months, sustained share gains without worsening incentives would support the affordability strategy. The counterpoint is that a lower advertised entry price can attract shoppers while buyers transact up-trim, limiting the realized ASP impact. That is unverified, not an assumption.
No company in the supplied identity mapping connects to Subaru; AAPL has no apparent exposure to this announcement. There is no justified mapped-equity trade from this item alone. Verify Subaru’s reported volume, U.S. mix, incentives, and margin commentary before taking a parent-company view. The thesis weakens if the launch fails to improve sales or requires broad discounting; it strengthens if share and volume rise while incentives remain contained.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No trade in AAPL: the article provides no supported business or financial link to Apple.
- Treat Subaru’s pricing move as a watch item, not a standalone directional equity signal; do not infer a parent-company ticker from the supplied data.
- When launch deliveries begin, monitor Subaru’s U.S. sales and incentive levels alongside Toyota and Honda crossover promotions. Consider a relative-value position only if Subaru gains share without materially greater discounting.
- Reassess after reported results or guidance disclose U.S. vehicle mix and automotive margins; persistent margin deterioration or rising incentives would falsify the thesis that richer standard content can be offset by volume.
More News
- Apple’s iPhone Duo Hits Stores in Face of Short Supply and High Demand
- Elon Musk’s dream merger is a nightmare for SpaceX shareholders
- Personal agents like Meta's Muse could fuel AI’s growth — and challenge Amazon and Apple
- PC shipments are in the toilet, plunging over 20 percent from last year
- iPhone Duo Review + Pre-Order Problems with Andru Edwards
- Samsung all but confirms iPhone Duo is goosing Galaxy Z8 sales