
David Storch’s Sheffield Wednesday Bet Starts With a £1 Million Wi-Fi Fix
Source: Bloomberg
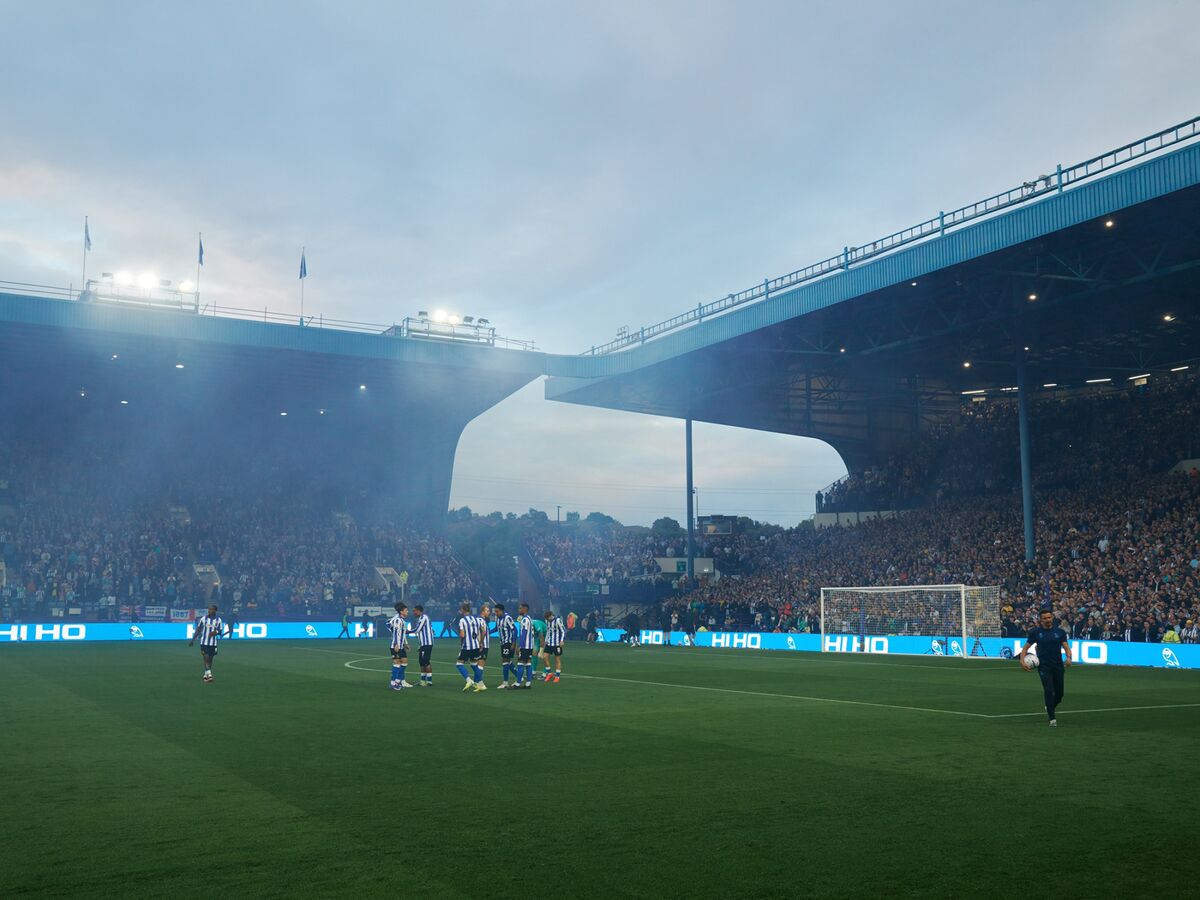
The article describes American investor David Storch’s plan to revive troubled English football club Sheffield Wednesday, starting with a reported £1 million Wi‑Fi investment. No financial performance metrics, funding terms, or outcome forecasts are provided in the excerpt. Overall, it reads as a subscriber-style profile/preview with minimal identifiable market impact.
Analysis
The market should treat this as governance/credibility signaling, not a true operating inflection. A small infrastructure upgrade in a distressed football asset does little to change enterprise value unless it is paired with wage-bill reset, refinancing, and a credible path to stable league status; otherwise it is just maintenance capex with weak payback.
The second-order issue is capital allocation discipline. In clubs like this, cash spent on fan-facing improvements can either help commercial renewal or become a distraction if the balance sheet is still fragile; the real variable is whether new ownership can reduce recurring losses faster than match-day revenue volatility erodes liquidity. If the club needs repeated shareholder support, any near-term uplift from better facilities is likely offset by dilution or creditor overhang.
For public markets, there is no clean, liquid read-through. The only plausible beneficiaries are niche stadium-tech and connectivity vendors, but the spend is too small to matter materially, and the article does not identify a repeatable rollout. The contrarian view is that sentiment around an American rescue story can overstate turnaround odds: value in distressed sports franchises typically comes from debt restructuring and governance cleanup, not cosmetic capex.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.00
Key Decisions for Investors
- No direct trade in IVSBF: treat as a watchlist name only until there is audited evidence of funding capacity, wage-bill reduction, and debt terms; absent that, the signal is too small for a risk-adjusted position.
- Set a 1-3 month alert on any refinancing, owner capital injection, or league-sanction event; those are the real catalysts that can change equity value, while fan-experience capex alone should not move the model.
- If seeking a public-market proxy, avoid broad consumer-discretionary or UK small-cap chase trades tied to the narrative; the economic linkage is too indirect and likely to fade before earnings season.
- Reassess only if the club posts a material operating improvement in the next 6-18 months: lower cash burn, improved attendance/commercial revenue, or a debt haircut; otherwise the upside remains dominated by insolvency/relegation risk.
More News
- Take Five: Bangkok blues
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Saudi Arabia says 1 dead, 11 injured in latest attack on Riyadh airport
- Countries warn against travel to Saudi Arabia following Houthi attacks
- Why is LG Innotek stock plunging today?
- RBI Tightens Rupee Defense as Pricey Crude, Foreign Outflows Bite: USD/INR