
Rivian Shines as a Bright Spot in a Down U.S. EV Market, and Surprisingly, It's Not All R2 Driven
Source: fool.com
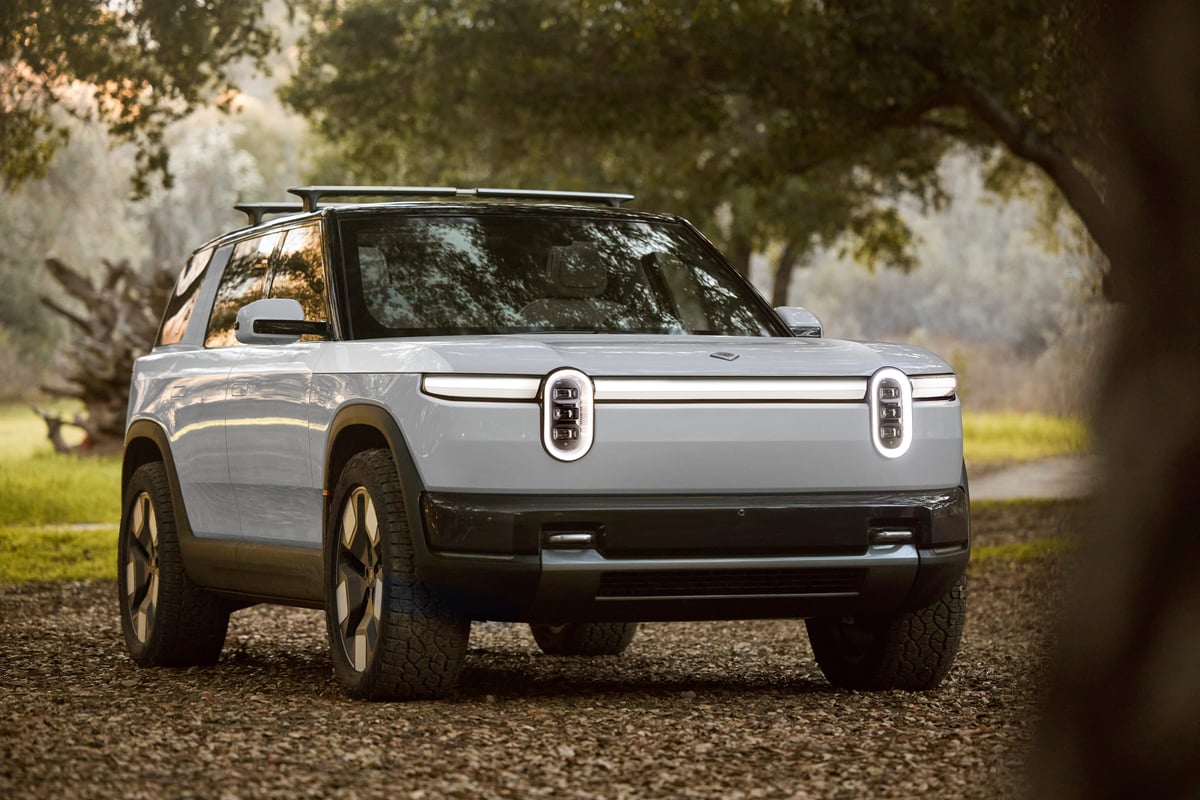
Rivian ranked No. 2 in U.S. battery-EV registrations in August, with 4,995 vehicles and a 33% year-over-year increase, while the overall EV market fell 36%. Its R2 recorded 1,554 registrations, and mostly Amazon-destined electric van registrations rose 87% to 2,165; R1S registrations declined 53%. The article sees scope for further R2-driven growth as production shifts ramp, but notes Tesla remained dominant with 48,083 registrations and 54.5% market share, while competition and the coming R3 launch remain important factors.
Analysis
The headline ranking is a weak proxy for competitive strength: Rivian’s registration count remains far below Tesla’s, and a model launch can lift rankings before it demonstrates repeatable demand or attractive unit economics. The more consequential test is whether the R2 ramp converts into sustained deliveries without manufacturing inefficiency, discounting, or a less favorable mix as lower-priced trims arrive. Higher volume could therefore be positive for utilization but not necessarily for gross profit per vehicle.
Rivian’s van registrations offer a separate demand signal, but concentration in a small number of fleet customers makes this less diversified than a broad consumer recovery. For Amazon, greater fleet electrification could support operating and emissions goals; the financial benefit depends on vehicle deployment, utilization, and total cost of ownership, not registrations alone. Verify deliveries and fleet economics before underwriting a material AMZN impact.
The post-incentive comparison is the near-term catalyst, not August’s ranking. In the next one to three months, watch seasonally adjusted EV demand, Rivian deliveries versus production, inventory, incentives, and automotive gross profit. Over six to eighteen months, faster competing model launches and lower-cost offerings could pressure R2 pricing and shorten its period of differentiation. A reversal would be sustained R2 delivery misses, rising inventory/discounting, or continued R1S weakness without offsetting improvement in margins.
Contrarian read: the data supports product-launch momentum, not yet durable share gains. Tesla’s share increase during a shrinking market is not proof of stronger absolute demand; likewise, Rivian’s rank obscures the large scale gap. No valuation or margin data here justifies chasing RIVN on registrations alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- Do not buy RIVN solely on its No. 2 registration ranking. Treat it as a catalyst watch through the next clean, post-incentive registration and delivery releases.
- For RIVN, require evidence that deliveries are tracking production without inventory buildup and that automotive gross profit improves as R2 volume scales. A miss on deliveries or rising discounting would falsify the ramp thesis.
- Keep AMZN exposure to the van data neutral pending confirmation of actual fleet deliveries, deployment, and total-cost-of-ownership benefits; registrations do not establish a material earnings contribution.
- Avoid an outright TSLA-versus-RIVN pair based on this snapshot: the registration scale gap favors Tesla operationally, but valuation and forward margin expectations are missing. Reassess after post-credit demand data and company guidance.
More News
- ‘There’s nothing temporary about a temporary store’: How Spirit Halloween’s CEO took it from 130 stores to 1,550—and swallowed your mall’s Hot Topic
- Rick Lazio: We’ve lost an auto race before, China’s EV climb should worry us
- Amex Stock Slides on Job Cuts, But the Real Story Is Macro
- SpaceX's $1 Trillion Revenue Ambition: Can Elon Musk Deliver?
- Flying Cars, Smart Homes, and Cracks in the AI Boom
- Tesla: 2027 Could Be A Massive Growth Inflection Point (Rating Upgrade)