
Critical gas for sustainable high-voltage grids now made in Germany
Source: PR Newswire
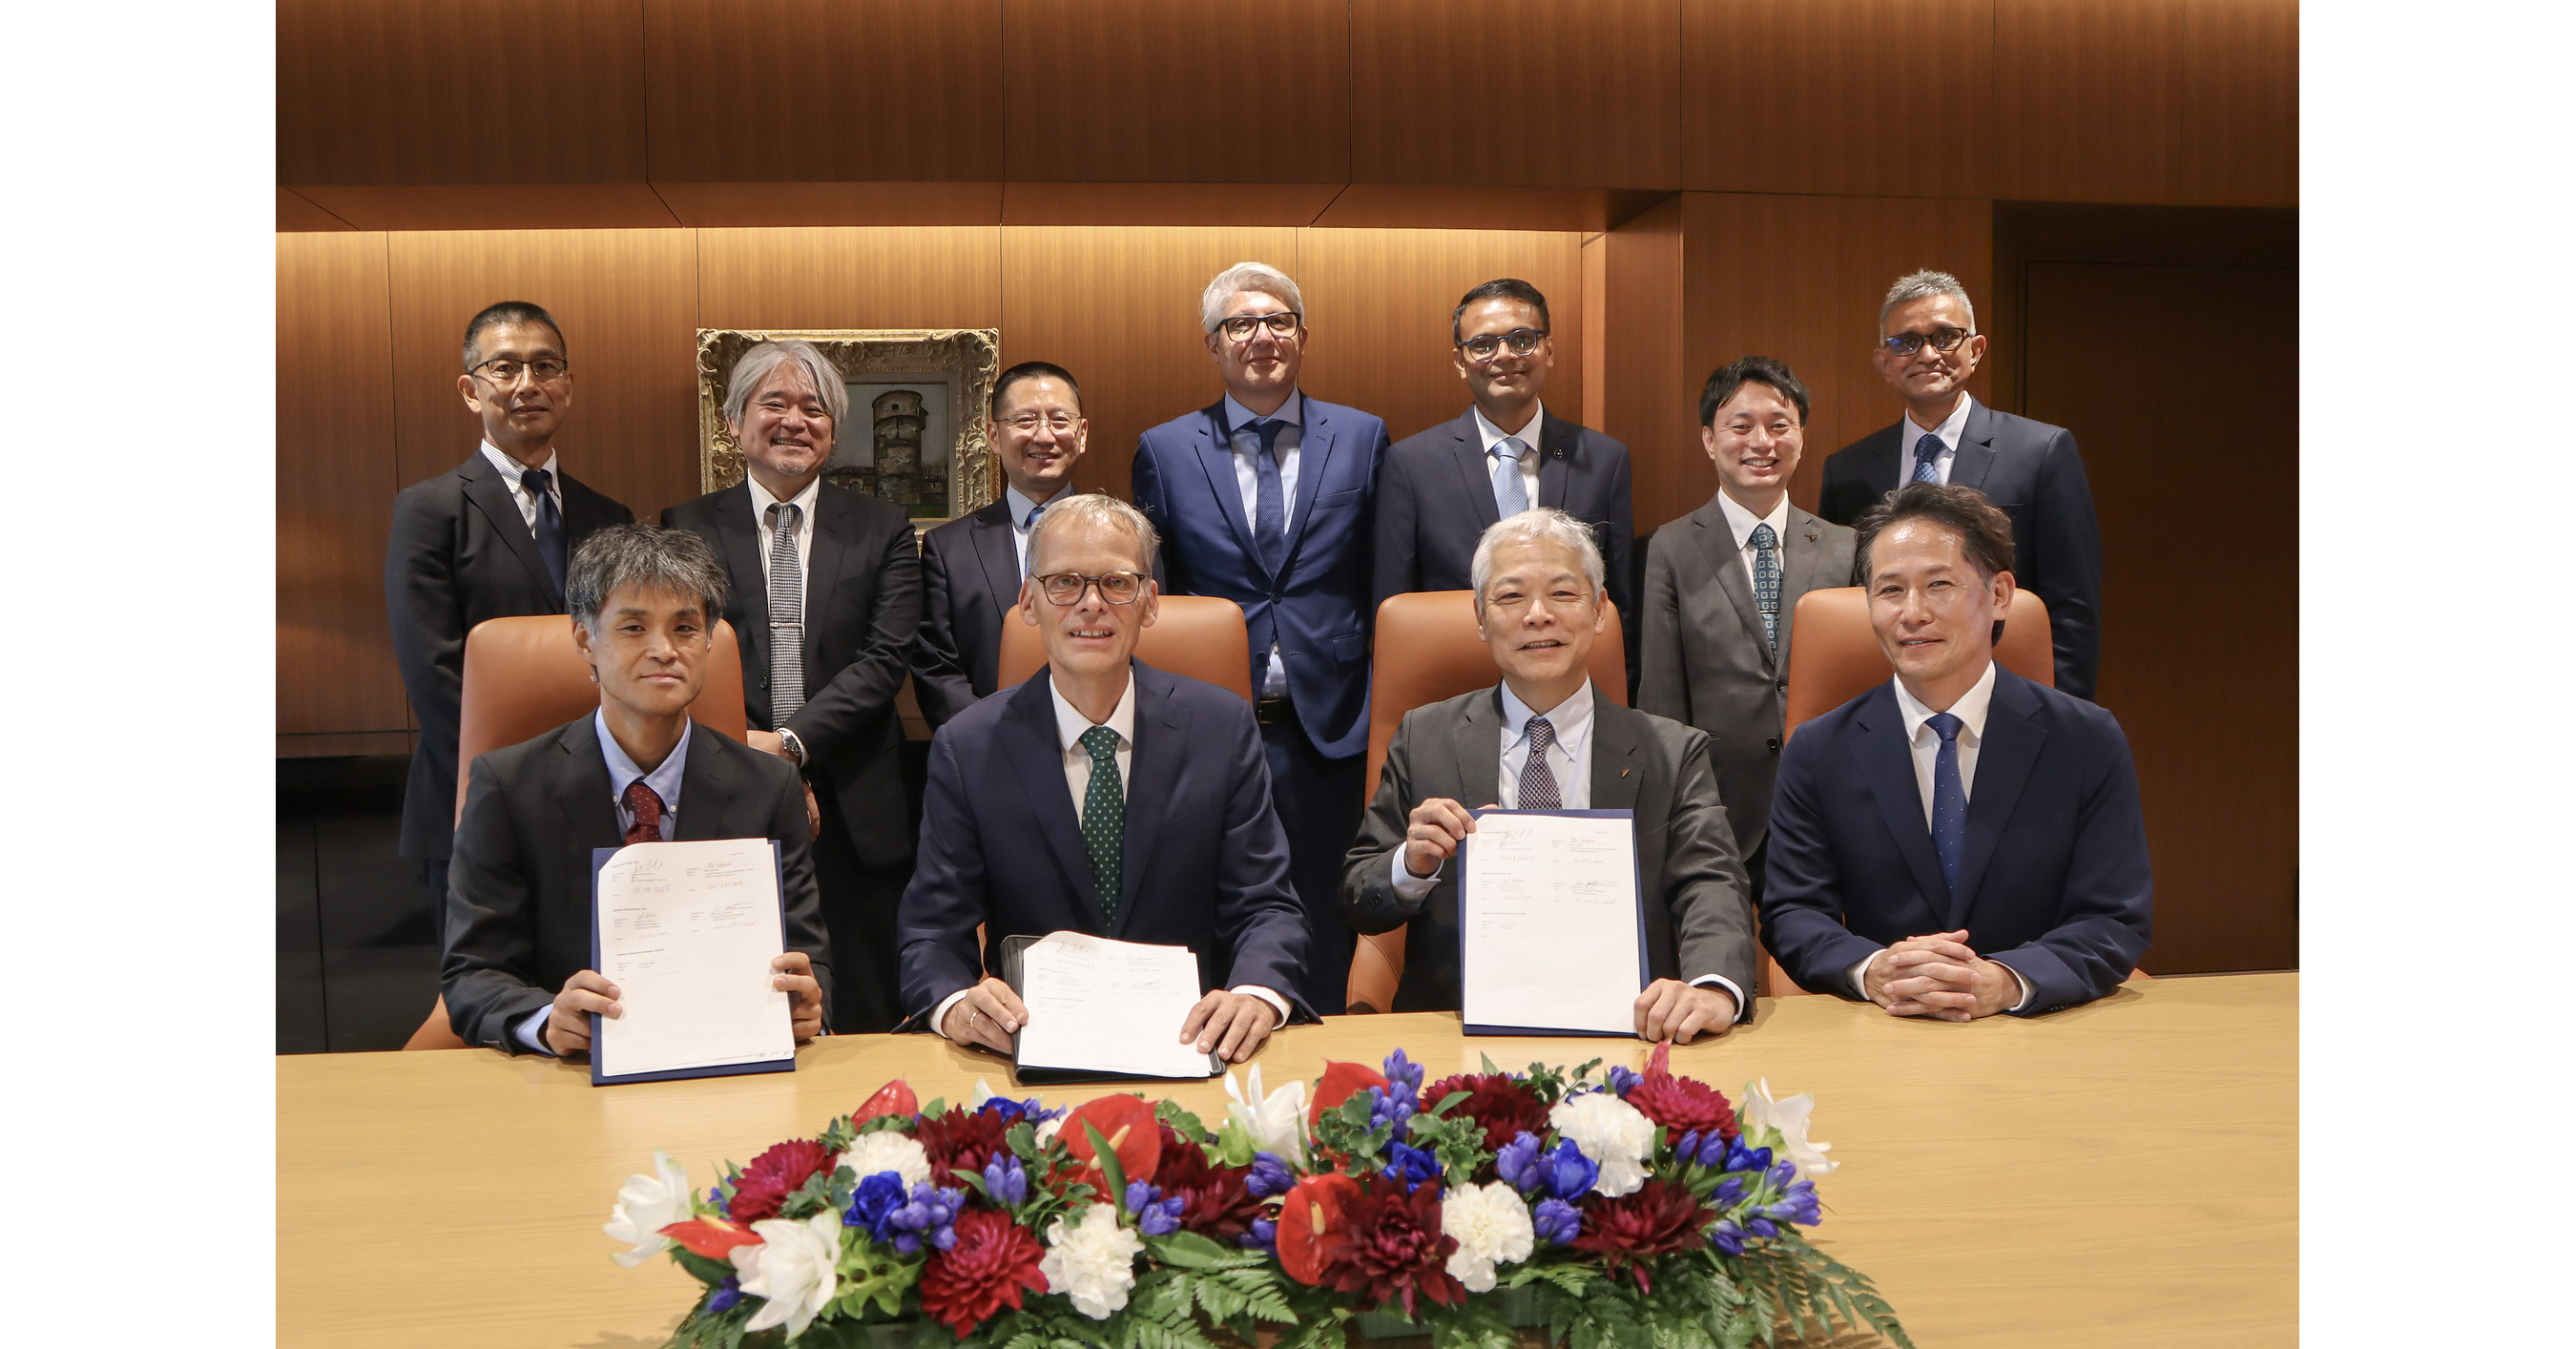
Hitachi Energy and Daikin agreed on a long-term supply relationship starting in 2027, with Daikin Chemical Europe providing C4-FN specialty gas (produced in Frankfurt) for Hitachi Energy’s SF6-free EconiQ high-voltage switchgear. The EconiQ approach cuts CO2-equivalent emissions by 99% versus conventional SF6-insulated equipment while maintaining performance, and the portfolio has drawn 4,000+ orders across 40 countries. The added European production capacity is aimed at securing long-term supply resilience for a growing market as Hitachi expands multi-sourcing for key inputs.
Analysis
The investable point is not the gas itself; it is the de-risking of a constrained supply chain for a product category that sits at the intersection of grid capex, regulation, and utility qualification cycles. That matters because customers buy this equipment years in advance and hate single-source dependencies; a second European production node should improve conversion of backlog into shipments and reduce the risk premium attached to long-dated orders. For HTHIY, the benefit is more on mix quality and order confidence than near-term EPS; for DKILY, this is strategic optionality into a high-spec industrial material with sticky qualification once embedded.
The catalyst path is slow. In the next 1-3 months, the market will likely treat this as an ESG-positive supply announcement unless management can tie it to faster order growth, higher backlog, or improved lead times. Over 6-18 months, the upside case is that European localization helps Hitachi win utility frameworks that previously favored incumbents with more diversified sourcing; the downside case is that qualification slips, utility capex pauses on higher rates, or regulators move slower than expected on SF6 phaseout enforcement.
Contrarian take: consensus may overpay for the 'green technology' headline while underestimating the real economic moat, which is procurement reliability and supply assurance. If that is true, this is more supportive of valuation durability than a step-change rerate. The thesis is falsified if EconiQ order momentum stalls, the 2027 capacity ramps late, or management stops emphasizing supply constraints as a growth limiter.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.55
Ticker Sentiment
Key Decisions for Investors
- Build a modest long HTHIY on pullbacks, 6-12 month horizon; thesis is backlog conversion and reduced supply-chain risk, not immediate earnings uplift. Cut if EconiQ order growth does not re-accelerate over the next two quarters.
- Add DKILY only as a small satellite position, 12-18 months; the upside is strategic positioning in a qualified specialty chemical chain, but revenue contribution is likely too small for a large allocation. Reassess if the Frankfurt capacity timeline slips beyond 2027.
- No chase in the broad clean-tech basket on this headline; use it as a watch item for European grid-capex beneficiaries rather than a broad sector signal.
More News
- Oil falls as crude flows remain 'surprisingly strong'
- Trump & Xi to Meet Amidst Friction on Wars, Tech, Trade
- US Diesel Tops $6.50 a Gallon as Wars Worsen Global Fuels Crunch
- Trump ‘open’ to meeting Iranian President Pezeshkian- Fox reporter
- Here are the 3 big things we're watching in the stock market this week
- Tech leads shares higher in Asia, oil eases