
Results from Phase III Study of Trastuzumab Botidotin versus T-DM1 in HER2-Positive Breast Cancer Published in JCO
Source: PR Newswire
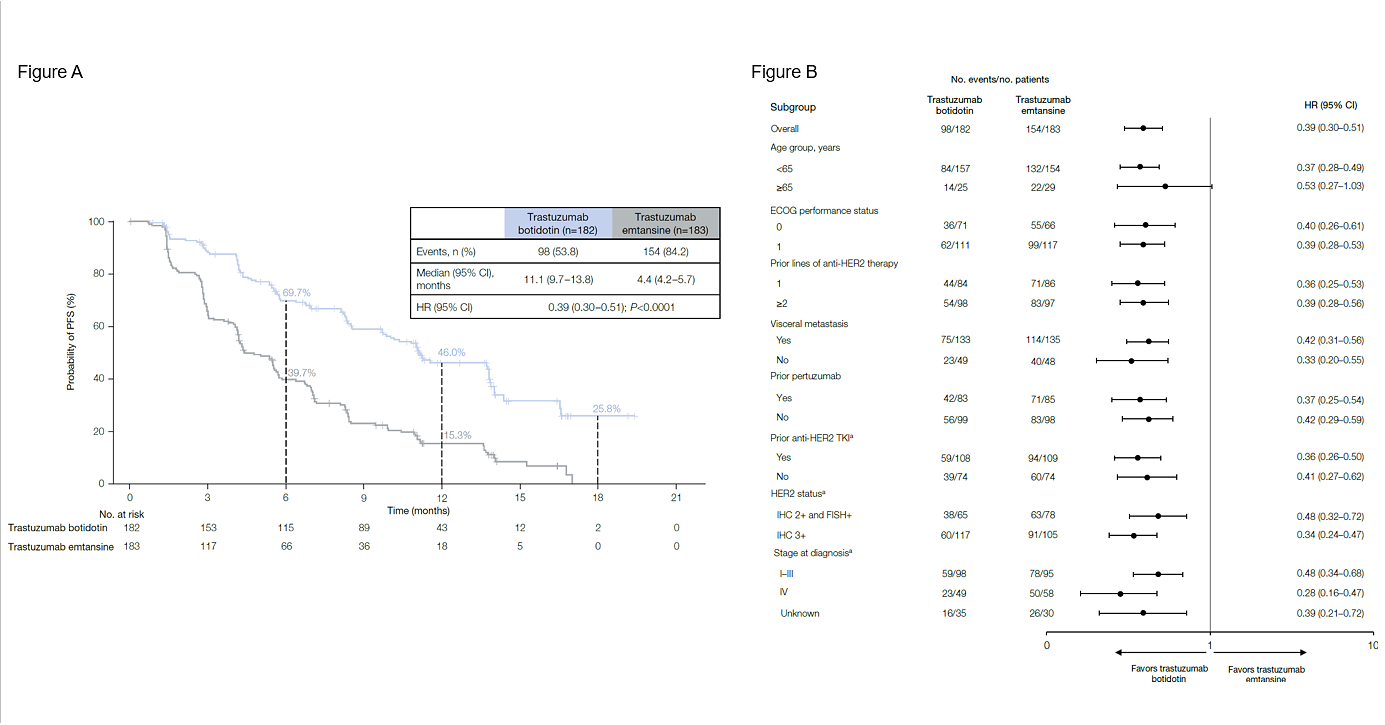
Kelun-Biotech's phase III trastuzumab botidotin trial in HER2-positive unresectable or metastatic breast cancer showed median PFS of 11.1 months versus 4.4 months for T-DM1, corresponding to a 61% reduction in progression or death risk (HR 0.39). The ADC also delivered a 76.9% objective response rate versus 53.0% and median response duration of 12.2 versus 5.7 months, with an immature but favorable overall-survival trend indicating a 38% lower risk of death. The drug has received China NMPA approval for second-line or later HER2-positive breast cancer, validating Kelun-Biotech's domestically developed ADC platform.
Analysis
The investable read-through is strongest for 6990.HK’s China commercialization credibility and, secondarily, for parent 002422.SZ through asset-value recognition. The clinical delta supports displacement of legacy T-DM1 where reimbursement, hospital formulary access, and local pricing favor a domestic ADC; however, it does not establish competitiveness against Enhertu, the clinically relevant global benchmark in much of the second-line HER2 market. The publication is therefore a valuation de-risking event, not yet evidence of a large international revenue opportunity.
Near-term share performance will depend less on the dataset than on launch execution: NRDL inclusion or provincial reimbursement progress, prescription ramp in top oncology centers, net-price realization, and ocular-event-related discontinuation in real-world practice. A rapid uptake trajectory could re-rate 6990.HK’s ADC platform and improve partnering leverage for its earlier-stage pipeline; weak net sales despite favorable clinical adoption would expose the market’s tendency to capitalize China approvals before durable cash conversion is visible.
For AZN and 4568.T, the impact is limited unless botidotin demonstrates activity after prior topoisomerase-I ADC treatment or generates comparative data versus Enhertu. The more important second-order effect is competitive pressure on Roche’s residual Kadcyla franchise in China, although that product is already strategically superseded in many markets. Consensus may overstate the threat to global HER2 incumbents: a trial against an older comparator and immature survival evidence leave meaningful efficacy, sequencing, and regulatory gaps before ex-China substitution is plausible.
Over 6-18 months, the key upside optionality is platform validation translating into licensing economics rather than standalone domestic sales. That thesis is falsified if quarterly product revenue fails to accelerate after reimbursement/formulary milestones, ocular toxicity materially constrains dose intensity, or the post-topoisomerase-ADC study does not show credible activity. Given limited independent commercial data in the release, the immediate move should be treated cautiously rather than chased.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.78
Key Decisions for Investors
- Maintain a watch-to-buy stance on 6990.HK rather than chase publication-driven strength; initiate only after the next two reported periods show sequential product-sales acceleration and stable gross margin. Upside is platform multiple expansion from demonstrated launch execution; risk is that approval value is already reflected while net pricing and hospital access lag.
- Use 002422.SZ as the more liquid indirect exposure only if disclosed ownership economics and consolidated contribution confirm meaningful look-through value from 6990.HK. Avoid assuming a one-for-one read-through: parent-level pharmaceutical operations can dilute the biotech catalyst.
- Do not position short AZN or 4568.T on this development. A China-only challenge to T-DM1 is insufficient to impair Enhertu-driven earnings; reconsider only if botidotin produces head-to-head data versus Enhertu or credible post-Enhertu sequencing data within 12-18 months.
- Set catalyst alerts for China reimbursement/formulary decisions, first full-quarter commercial sales disclosure, and dose-interruption/discontinuation rates from real-world use. Failure to meet management’s implied launch trajectory or evidence of persistent ocular toxicity would be the signal to avoid or reduce 6990.HK exposure.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- Fortinet’s stock is taking a dive after earnings. Here’s why.
- RBC Capital cuts Sprouts Farmers Market stock rating on margin concerns
- Microsoft's Big Bets on AI Start to Pay Off