
Shanghai Electric získala první zahraniční zakázku na dodávku vysokovýkonných plynových turbín pro malajský projekt o výkonu 500 MW
Source: PR Newswire
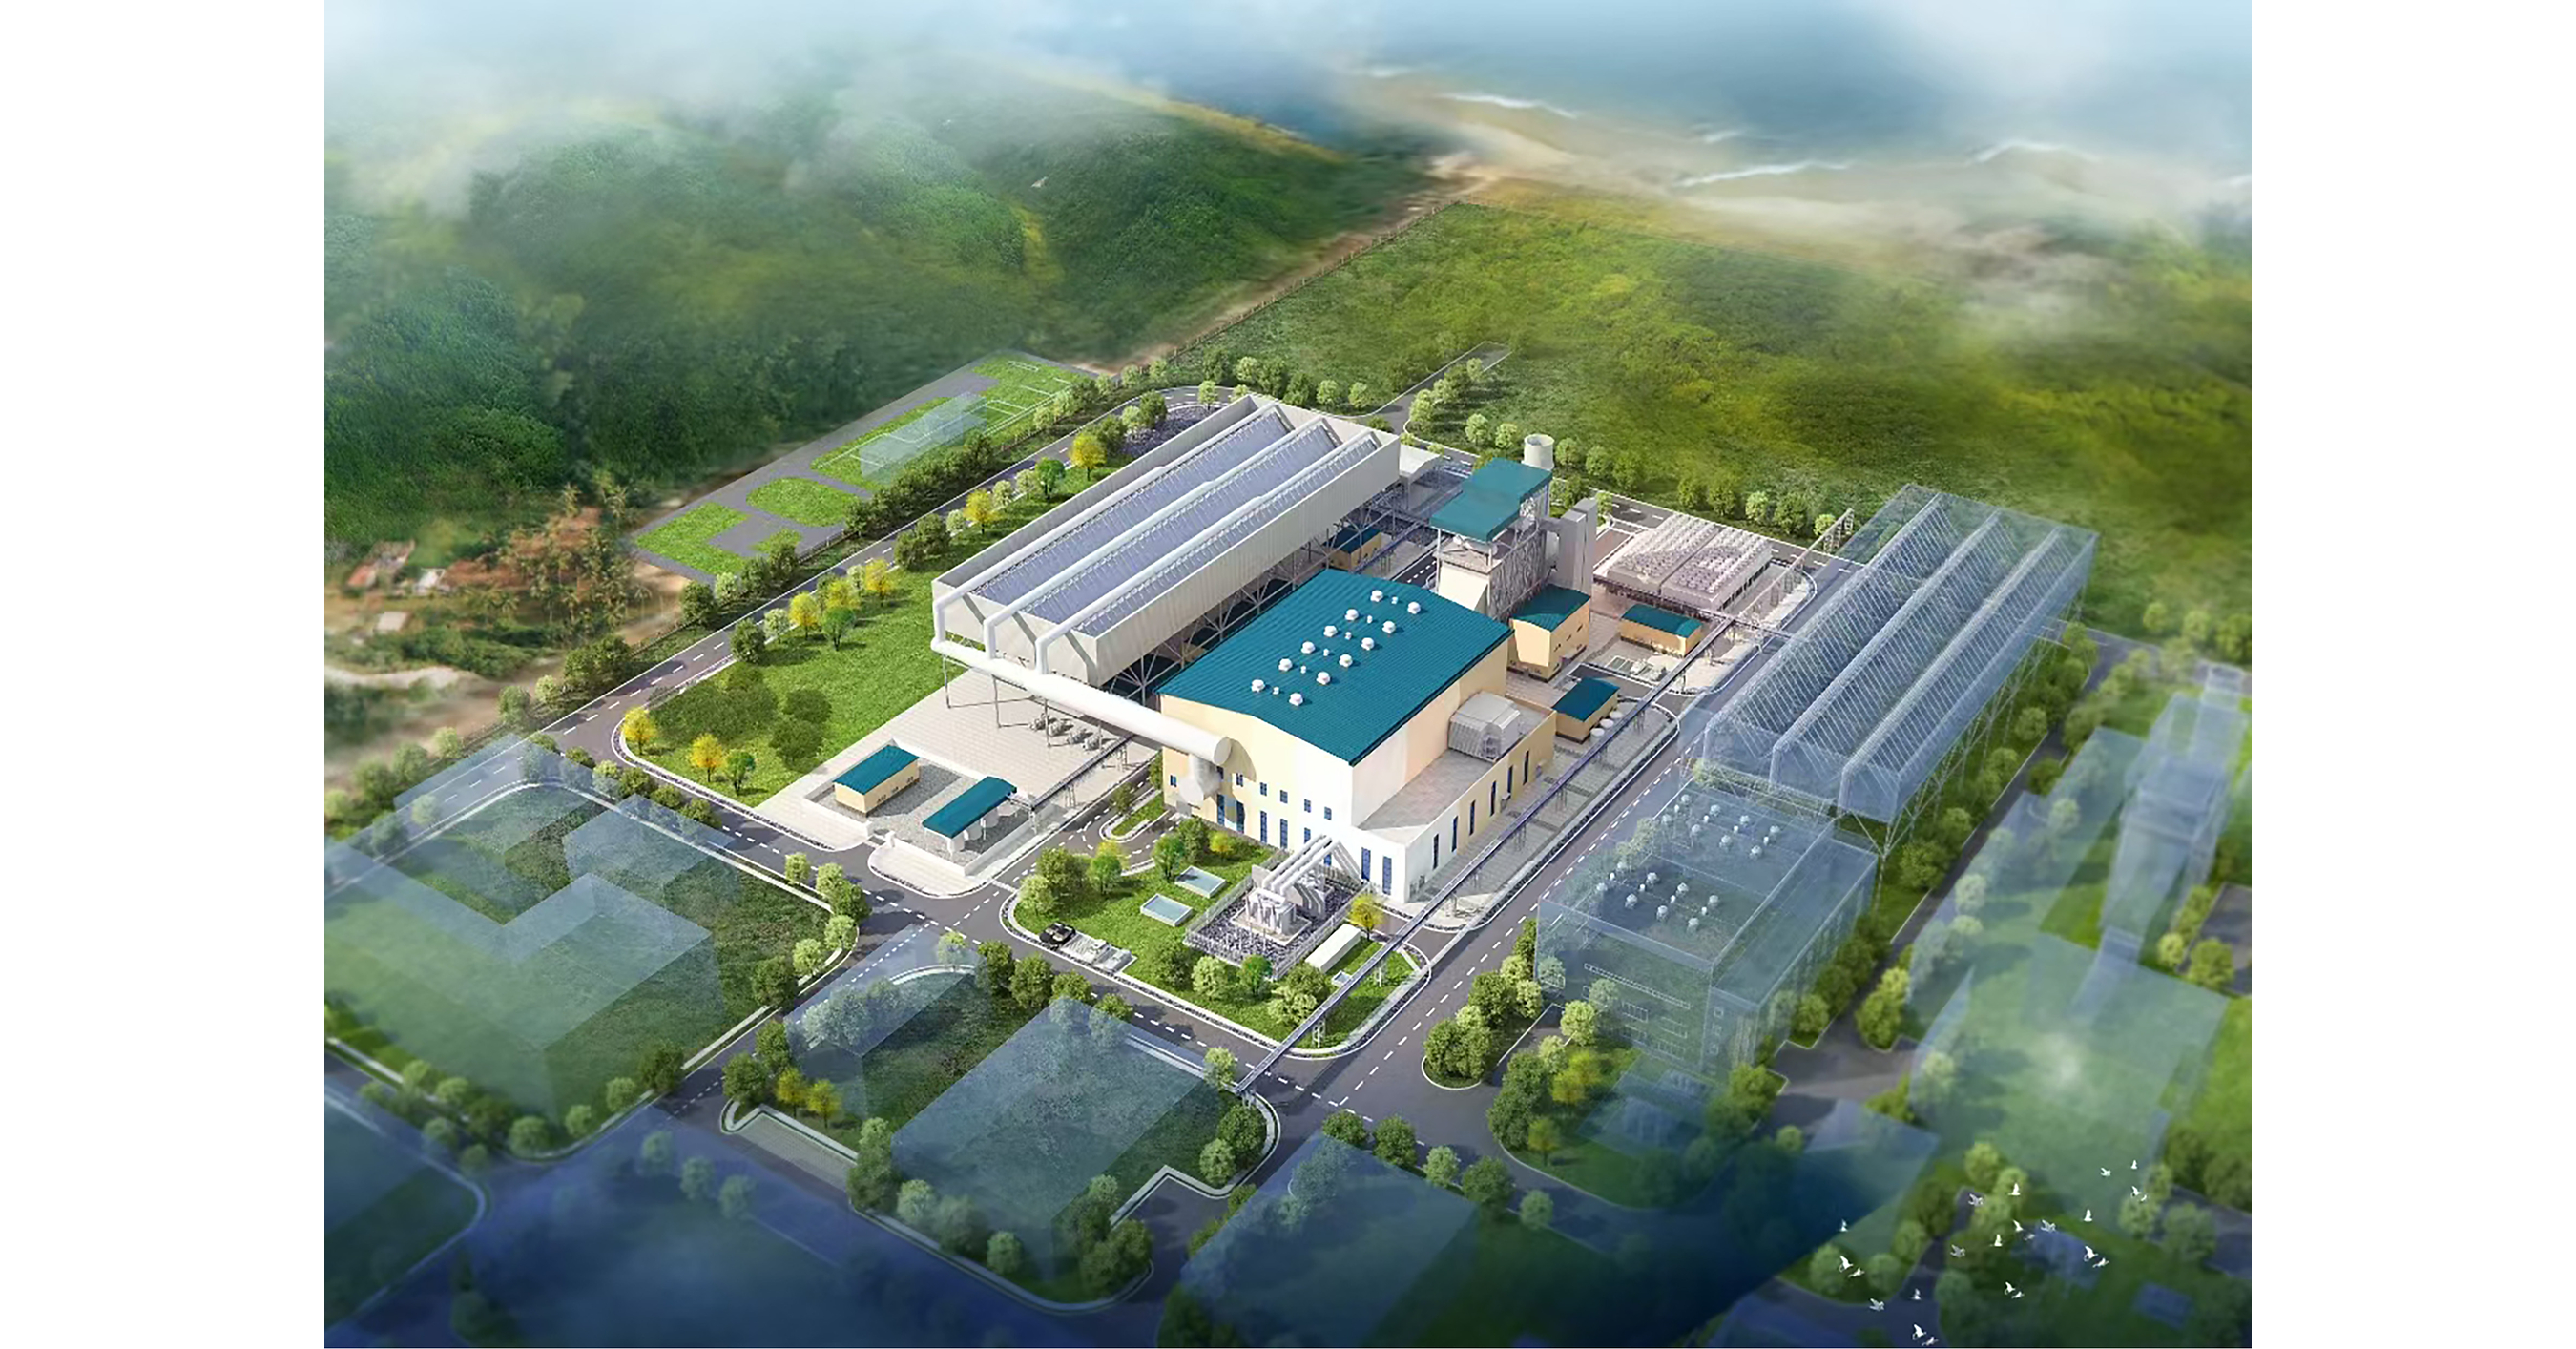
Shanghai Electric won its first overseas high-power gas-turbine contract, supplying an EPC turnkey solution and 25-year service agreement for the 500MW Sarawak Samalaju CCGT project in Malaysia. The contract covers internally manufactured gas and steam turbines, generators, heat-recovery steam generators and cooling systems, expanding the company’s international credentials in heavy-duty turbines. Shanghai Electric has delivered 103 turbine units totaling more than 21,000MW of commissioned capacity and reports interest from developers in Indonesia, Thailand, the Philippines and Vietnam.
Analysis
The economic value is less in the initial equipment award than in establishing an export operating reference for Shanghai Electric's heavy-duty turbine platform. A successful availability record could lower bankability barriers with Southeast Asian IPPs and create follow-on bids where Chinese EPC financing and local-content flexibility matter more than Western installed-base advantages. The LTSA should improve revenue durability and mix over time, but it also transfers outage-performance and parts-cost risk to Shanghai Electric; this is not equivalent to high-margin service revenue until contract pricing, guarantees, and warranty provisions are disclosed.
Near-term equity impact should be limited: EPC revenue recognition is likely phased against procurement and construction milestones, while meaningful service economics arrive only after commissioning. The more relevant 1-3 month catalyst is whether this converts into independently announced pipeline wins in Indonesia, Vietnam, Thailand, or the Philippines; one contract is a reference, whereas two or three would imply real share displacement. A 6-18 month concern is that aggressive Chinese pricing to secure export references could raise working-capital needs and dilute project margins, particularly if customers require deferred payment terms.
GE Vernova (GEV), Siemens Energy (ENR.DE), and Mitsubishi Heavy (7011.T) face little immediate earnings risk from one project, but the event is a watch signal for Asian mid-scale CCGT tender pricing. Consensus may over-credit the strategic milestone: gas turbines are purchased on heat rate, forced-outage history, financing, and lifecycle guarantees, so the thesis fails if Shanghai Electric cannot demonstrate bankable performance data or if its export bids require materially lower pricing. Conversely, verified repeat orders would justify reassessing Chinese turbine suppliers such as Harbin Electric (1133.HK) and Dongfang Electric (1072.HK) as beneficiaries of export substitution.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Key Decisions for Investors
- Maintain a watch, not a core position, in Shanghai Electric (2727.HK) until contract value, expected gross margin, advance-payment terms, and performance-guarantee exposure are disclosed. Upgrade to a tactical 6-12 month long only if subsequent Southeast Asian turbine awards are announced without a rise in receivables or contract-liability stress; falsify on margin-guidance cuts or a material working-capital outflow.
- For portfolios long GEV or ENR.DE, do not hedge on this development alone. Set a competitive-risk trigger if Chinese suppliers win at least two additional ASEAN heavy-duty turbine tenders over the next 12 months or if tender pricing implies a greater than 10% discount to Western OEM benchmarks; that would support a selective GEV/ENR.DE underweight versus 2727.HK.
- Monitor 1133.HK and 1072.HK for read-through, but require evidence of order conversion rather than taking sympathy exposure. A repeatable Chinese export-financing package could shift investor attention toward their overseas order books; absent named awards and margin terms, the likely effect remains narrative-driven rather than earnings-material.
- Use 2028 commissioning as the operational checkpoint: sustained availability and no disclosed liquidated-damages issue would validate LTSA annuity assumptions, while delays, forced-outage disclosures, or receivable extensions would materially impair the export-reference thesis.
More News
- Trump says U.S. may keep Iranian oil 'like Venezuela' as Gulf-Iran Hormuz talks stall
- Baker Hughes sees no slowdown in energy projects despite higher rates as AI buildouts stoke LNG demand
- U.S. stock futures slide on calls to slow AI development, M.East escalation
- Diplomacy stumbles with postponement of meeting on Strait of Hormuz proposal
- Oil prices rise after Saudi Arabia shut down critical pipeline that bypasses Strait of Hormuz
- Z.ai shares tumble over 10% after $5 billion fundraising, its second major raise in two months