
Distributed Energy Infrastructure Prepares for National Expansion with ISO Certification and Multi-State Licensing
Source: PR Newswire
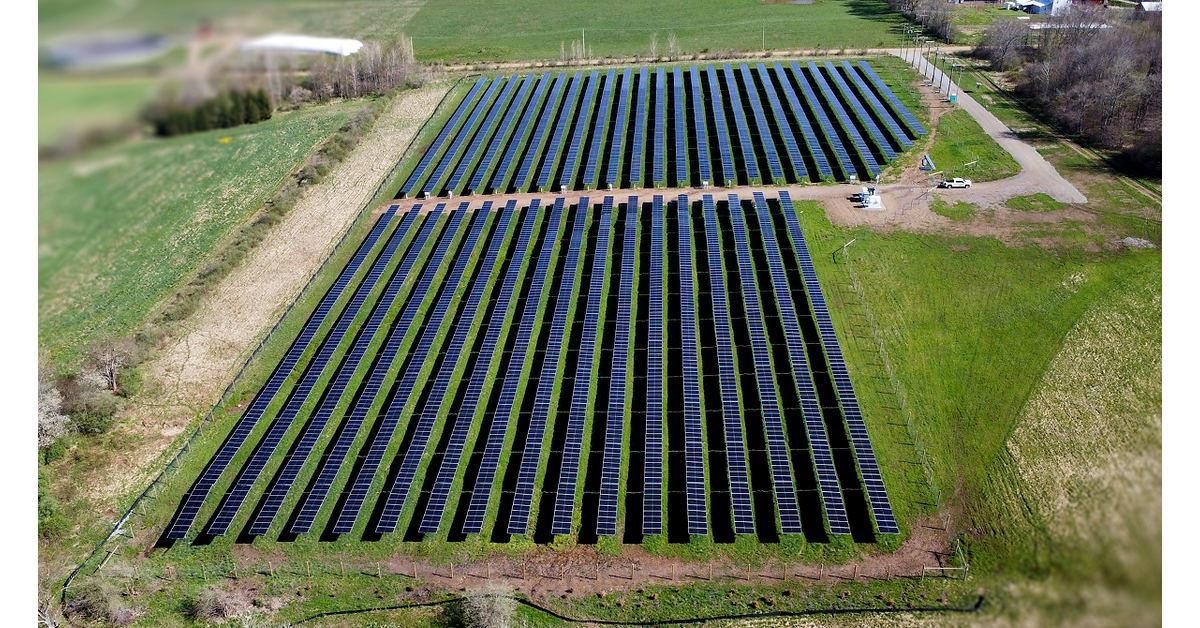
Distributed Energy Infrastructure (DEI) achieved ISO 9001:2015 certification and expanded contractor licensing to Virginia, positioning the EPC firm to pursue projects across a 30+ state footprint with more consistent delivery. The company says multi-state licensing can reduce time and cost versus separate state exams, supporting faster bid responsiveness for developers and asset owners. Overall, the operational/quality milestones are incremental positive for DEI’s growth plans, but no financial figures or guidance were provided.
Analysis
This is a procurement/qualification story, not a demand or pricing inflection. ISO 9001 and broader state licensing reduce friction in vendor prequalification, but they do not change the two real bottlenecks in solar-plus-storage: interconnection timing and equipment/working-capital constraints. The near-term market impact is likely negligible unless the company converts credentials into backlog, which is the only path to a durable gross-margin or cash-conversion improvement.
The second-order winner is the class of national developers and asset owners that value one EPC counterparty across multiple states; they can lower transaction costs and cut the odds of schedule slippage. Smaller regional EPCs are the likely losers if clients consolidate approved-vendor lists around firms that look bankable, insured, and administratively simple. Among public proxies, the read-through is mildly constructive for higher-quality contractors with utility-scale exposure such as MTZ, PRIM, and MYRG, but this is a relative, not absolute, tailwind.
The contrarian point is that the market often overprices "credibility" announcements when the binding issue is execution capacity, not paperwork. If anything, this should be faded as a moat narrative unless management later shows multi-state backlog wins, better gross margins, or lower claims/surety costs over the next 1-3 quarters. Falsifiers are simple: no backlog conversion, no margin uplift, or evidence that larger competitors win the same bids on price anyway.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- No immediate trade in TAN/ICLN or other renewables ETFs; treat this as a non-catalyst until DEI shows backlog conversion in the next 1-2 earnings cycles.
- Watch MTZ, PRIM, and MYRG for commentary on vendor prequalification, surety capacity, and utility-scale backlog quality; only buy a dip if gross margin and backlog both hold over the next quarter.
- If the sector rallies on "national expansion" headlines, consider fading strength in higher-beta solar names and staying in the highest-quality EPCs; the edge is execution, not certification.
- Set a catalyst alert for any DEI contract wins in 30+ states or measurable margin improvement over the next 3-6 months; absent that, the story stays informational rather than investable.
More News
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
- Cerebras Is About as Big as Nvidia's Data Center Business Was Nearly a Decade Ago. The Similarities Mostly End There.
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Research Workflows, Report Format Selection, and Interactive Synthesis
- Can ChatGPT Analyze a 10-K? A Verification Workflow