
Zensar registered 4.1% sequential constant currency revenue growth for Q2FY27
Source: PR Newswire
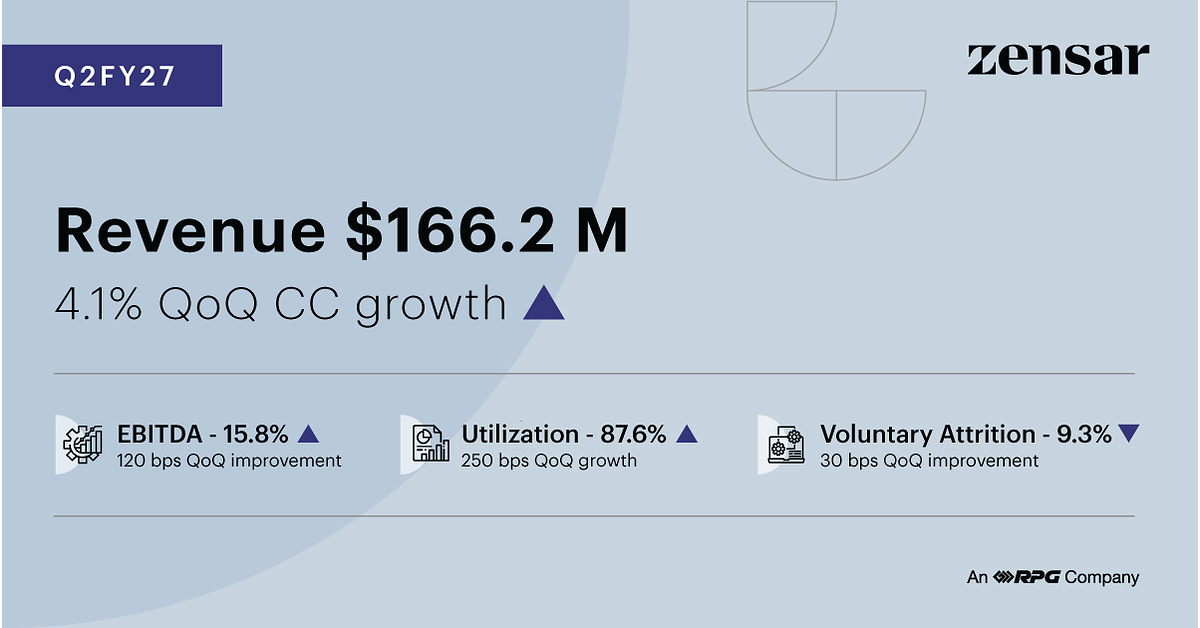
Zensar Technologies reported Q2FY27 revenue of $166.2M, up 4.1% sequentially in constant currency, while EBITDA margin rose 120 bps QoQ to 15.8%. Banking and Financial Services grew 17.1% year over year in constant currency, offset by a 21.6% decline in Telecommunications, Media and Technology. Management said AI-influenced deals accounted for 36% of the quarter’s order book and cited continued client investment in AI and digital modernization.
Analysis
The result strengthens the case that execution and mix—not a broad-based demand recovery—are driving the near-term improvement. BFSI is the clearest growth engine, while the sharp TMT contraction and continuing healthcare weakness make headline growth less diversified than management’s “broad-based” framing suggests. That concentration raises the risk that a few large programs or client decisions disproportionately affect the next quarter.
The margin rebound is valuable only if it persists alongside growth. Verify whether it reflects utilization, delivery mix, or temporary cost timing; AI productivity could support margins, but competitive pass-through may transfer part of those savings to clients. Likewise, AI-influenced order-book share is not equivalent to recognized revenue: production conversion, deal size, implementation timing, and renewal economics remain unproven. Near term (days), the release may support sentiment, but the absence of guidance, cash-flow detail, and valuation context limits confidence in repricing. Over 1–3 months, monitor order conversion and segment mix. Over 6–18 months, scaled AI delivery could differentiate Zensar, while also increasing substitution and pricing pressure across IT services. Larger providers such as TCS, Infosys, HCLTech, and Wipro remain competitive alternatives for enterprise programs.
Contrarian read: the market may over-credit AI pipeline language and underweight the persistent weakness in TMT and healthcare. The thesis improves if BFSI momentum broadens and margins hold without relying on lower investment; it is falsified by renewed margin compression, slowing BFSI growth, or continued TMT deterioration. Company-specific valuation, cash-flow, and order-book conversion data are needed before sizing a directional position.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Key Decisions for Investors
- Do not chase the initial earnings reaction without valuation and cash-flow context. Keep Zensar on an event-driven watchlist; consider a measured long only if the next quarter confirms revenue conversion and sustains the margin improvement.
- For a relative-value expression, assess a small long Zensar versus a diversified Indian IT-services exposure only after confirming that BFSI growth persists and TMT weakness stabilizes; avoid assuming AI order-book share translates directly into near-term sales.
- Over the next 1–3 months, track reported revenue from AI-led work, order-book conversion, utilization or delivery-cost commentary, and whether margin gains are repeatable rather than timing-related.
- Reassess or exit the constructive thesis if margins reverse, BFSI growth materially slows, or TMT remains a significant drag in subsequent results. Verify these indicators against reported figures rather than management’s AI adoption claims.
More News
- Marvell to buy Lumentum in $115 billion deal in AI data-center bet
- Marvell, Lumentum tout historic $115B deal to create ‘category leader' in AI connectivity
- Palantir reports booming U.S. commercial revenue growth, topping government for first time
- Anthropic releases amended IPO prospectus with third-quarter financials
- Coinbase has been battered over the past month. Morgan Stanley says steer clear
- The AI boom is facing another supply crunch. This time it’s the amount of capital available to feed Silicon Valley’s endless need for cash