
Holland America Line Opens 2028 Alaska Season with Rare Voyages and New Ways to Explore the Great Land
Source: PR Newswire
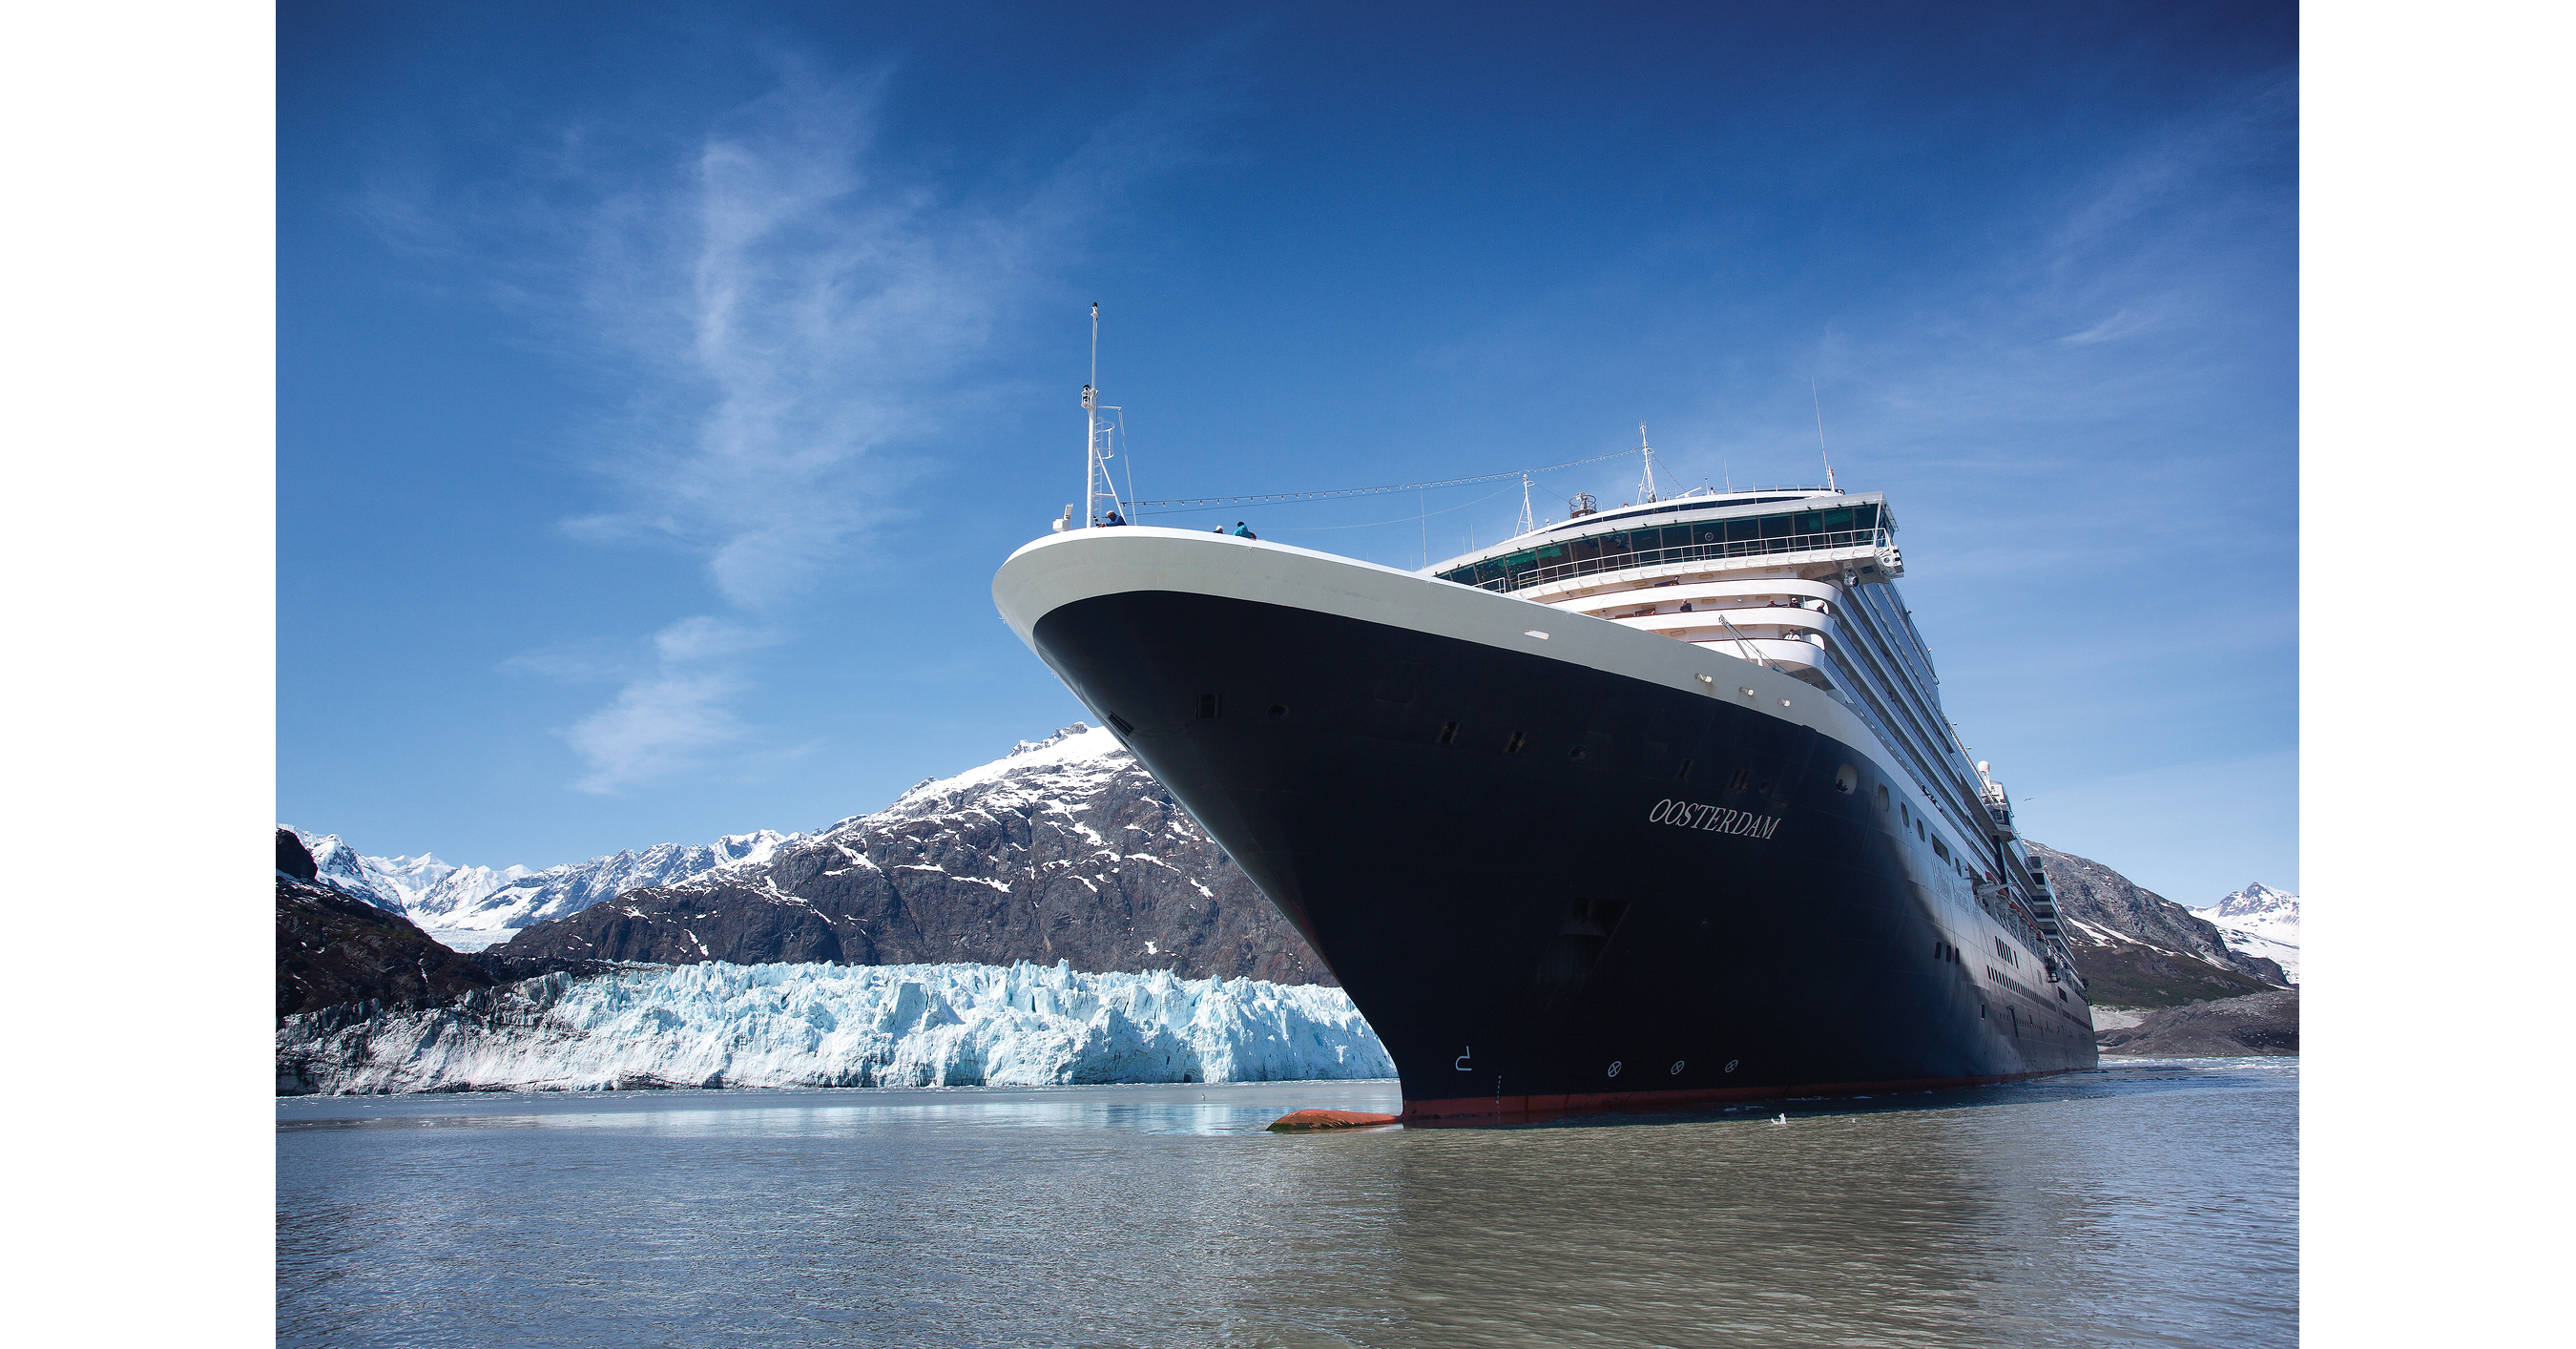
Holland America Line opened bookings for its 2028 Alaska season, highlighting new itineraries (including a rare 11-day California-to-Alaska voyage), first-time scenic cruising through Nootka Sound, and the Alaska debut of the reimagined Oosterdam after its Evolution transformation. The update emphasizes fleet investment and onboard enhancements (e.g., Solo Verandah staterooms, Bridgeview Suites, Grand Dutch Café) plus an early-booking promotion offering shore credit, specialty dining, beverage package, premium Wi-Fi, and a best-price guarantee. While largely promotional with no financial metrics, the expansion of its Alaska program supports a constructive demand outlook for the company’s premium cruise offerings.
Analysis
This is more of a signaling event than a fresh earnings catalyst. The economic value sits in mix, not volume: Alaska is one of the few cruise niches where premium pricing and shore-excursion attach rates can stay sticky, so the upside for CCL is higher yield per berth and better onboard spend rather than a meaningful near-term capacity change. The fact that the company is leaning hard on differentiated itineraries and a refurbished ship suggests management is defending share in a segment where product quality, not just price, drives conversion.
Competitive spillover is modest but real. RCL and NCLH can match Alaska demand, but they do not get the same incremental branding lift from HAL’s historical positioning, so this is more about CCL protecting a profitable niche than stealing a category-defining advantage. The second-order winner is any supplier tied to ship refurbishment and premium onboard features, but those flows are too diffuse to trade directly.
The risk is that investors over-interpret a long-dated booking announcement as evidence of current demand strength. The real test is booking curve quality and yield discipline over the next 1-3 quarters; if CCL starts discounting to fill the inventory, the Alaska premium story loses its value. A consumer slowdown would hit later bookings first, and cancellations on long-lead itineraries would show up before sailing dates, so this is a months-long, not days-long, catalyst path.
Contrarian view: the market may already grant cruise lines too much credit for “premium” product refreshes. Unless management can show higher net yields and better load factors on the reimagined ships, this is probably headline-positive but not thesis-changing. The stock reaction should fade if there is no accompanying guidance upgrade or evidence that Alaska mix is accretive to margins.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Ticker Sentiment
Key Decisions for Investors
- Do not chase CCL on the announcement; if the stock pops 2-3% on the headline, use strength to trim or sell near-dated upside because the cash-flow impact is mostly 2028-dated.
- Put CCL on a watchlist for the next earnings/booking update: get constructive only if management shows higher Alaska yields, stronger deposit growth, and no rise in promotional intensity.
- Relative-value setup: if subsequent booking commentary confirms premium outperformance, consider a small long CCL / short NCLH pair over 1-3 months; thesis fails if NCLH shows similar yield inflection or CCL starts discounting.
- No options expression unless there is a bigger move: prefer a call-spread sale or covered-call overwrite into any event-driven rally, with risk capped by a surprise improvement in forward booking metrics.
More News
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
- Cerebras Is About as Big as Nvidia's Data Center Business Was Nearly a Decade Ago. The Similarities Mostly End There.