
Aritzia Reports Second Quarter Fiscal 2027 Financial Results
Source: PR Newswire
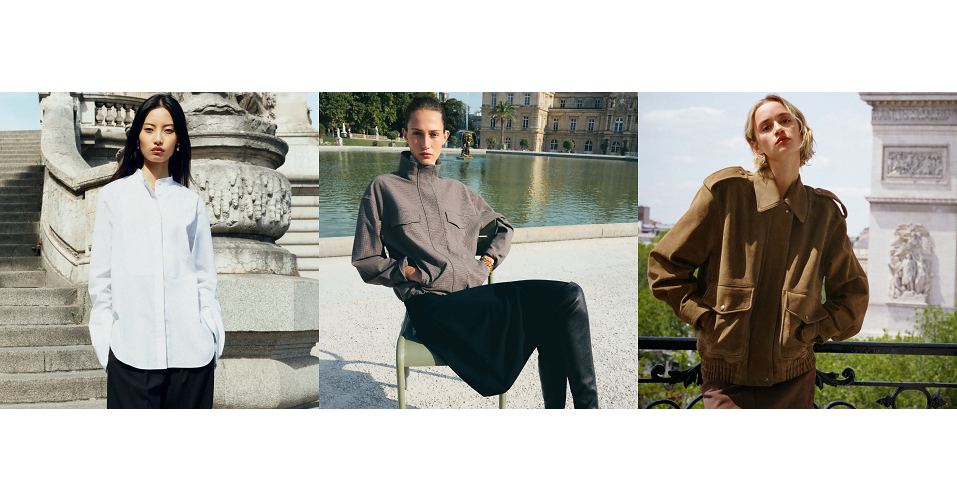
Aritzia's Q2 2027 net revenue rose 44.1% to C$1.17 billion, comparable sales grew 34.5%, and adjusted EBITDA nearly doubled to C$246.2 million, lifting its adjusted EBITDA margin by 590 bps to 21.0%. Reported net income of C$201.7 million included C$97.4 million in tariff refunds; excluding those refunds, adjusted gross margin increased 490 bps to 48.7%. Aritzia raised its Fiscal 2027 revenue outlook to C$4.78–C$4.88 billion, or 29%–32% growth, and expects adjusted EBITDA margin of approximately 20.0%; it also repurchased C$125.3 million of shares in Q2.
Analysis
Core operating momentum looks real rather than tariff-accounting driven: adjusted gross margin expanded excluding refunds, while comparable-sales strength and SG&A leverage indicate both pricing/markdown discipline and fixed-cost absorption. The key market risk is extrapolating that unusually strong demand curve. Management’s Q3 growth outlook implies a meaningful step-down from Q2, and higher expected SG&A leverage pressure makes the next quarter a test of whether growth can remain profitable as comps normalize.
The tariff refund is a one-off earnings and cash benefit, not a forward margin run-rate; tariff exposure and de minimis changes remain a possible offset to ongoing initial-markup gains. Inventory growth below sales growth is reassuring directionally, but absolute inventory is still substantial: track aging, markdowns and sell-through as the US expansion broadens. Store openings and distribution investment can compound returns if new-boutique productivity holds; otherwise leases and capex create operating leverage in reverse. Buybacks support per-share results near term but compete with a rising investment program for capital.
Near term, the October 8 call and October 27 Investor Day are catalysts for demand quality, boutique productivity and tariff assumptions. Over 6–18 months, US concentration and execution on new stores are the main structural upside and downside. Contrarian risk: the headline earnings acceleration may be over-read because reported profit includes refunds, but the stronger signal is the ex-refund margin improvement; conversely, consensus may underweight normalization from exceptional comps. RL is Ralph Lauren Corporation and is not the company reporting these results.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.72
Ticker Sentiment
Key Decisions for Investors
- ATZ: Prefer a conditional long/add-on-weakness rather than chasing the print. Reassess after the October 8 call; add only if management supports the Q3 outlook with healthy comparable-sales trends and confirms ex-refund margin progress. No price-based entry is offered without current market data.
- Use the October 27 Investor Day as a catalyst checkpoint: seek evidence on new-boutique productivity, payback discipline and sustained digital economics. Falsify the expansion thesis if guidance is cut, comparable sales weaken materially, or markdowns push adjusted gross margin below the company’s stated trajectory.
- Do not annualize the $97.4 million tariff recovery or reported gross-margin uplift. Monitor tariff/de minimis developments and realized adjusted gross margin; a reversal in initial-markup gains or renewed markdown pressure would undermine the earnings-quality thesis.
- Track inventory aging and cash allocation alongside growth: persistent inventory growth outpacing revenue, weaker operating cash flow, or buybacks crowding out planned store/distribution investment would be warning signals. The release does not establish a valuation-based risk/reward, so avoid sizing solely from the earnings beat.
More News
- Bank of Canada Rate Hike Bets Fade After Worst Year-to-Date Job Loss Since 2020
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
- Trump's diesel agreement with Putin accused of contradicting Russia sanctions law
- Trump reaches Russian diesel supply deal as U.S. fuel prices surge
- Rising fuel costs slashed Delta’s profit outlook despite strong demand
- ‘I drive a Tesla’: After Elon Musk said he’d lose his job, Delta CEO Ed Bastian says there’s ‘no tit for tat’ as airline unveils earnings miss