
Orbis Flying Eye Hospital Marks 20 Years of Partnership with Macau
Source: PR Newswire
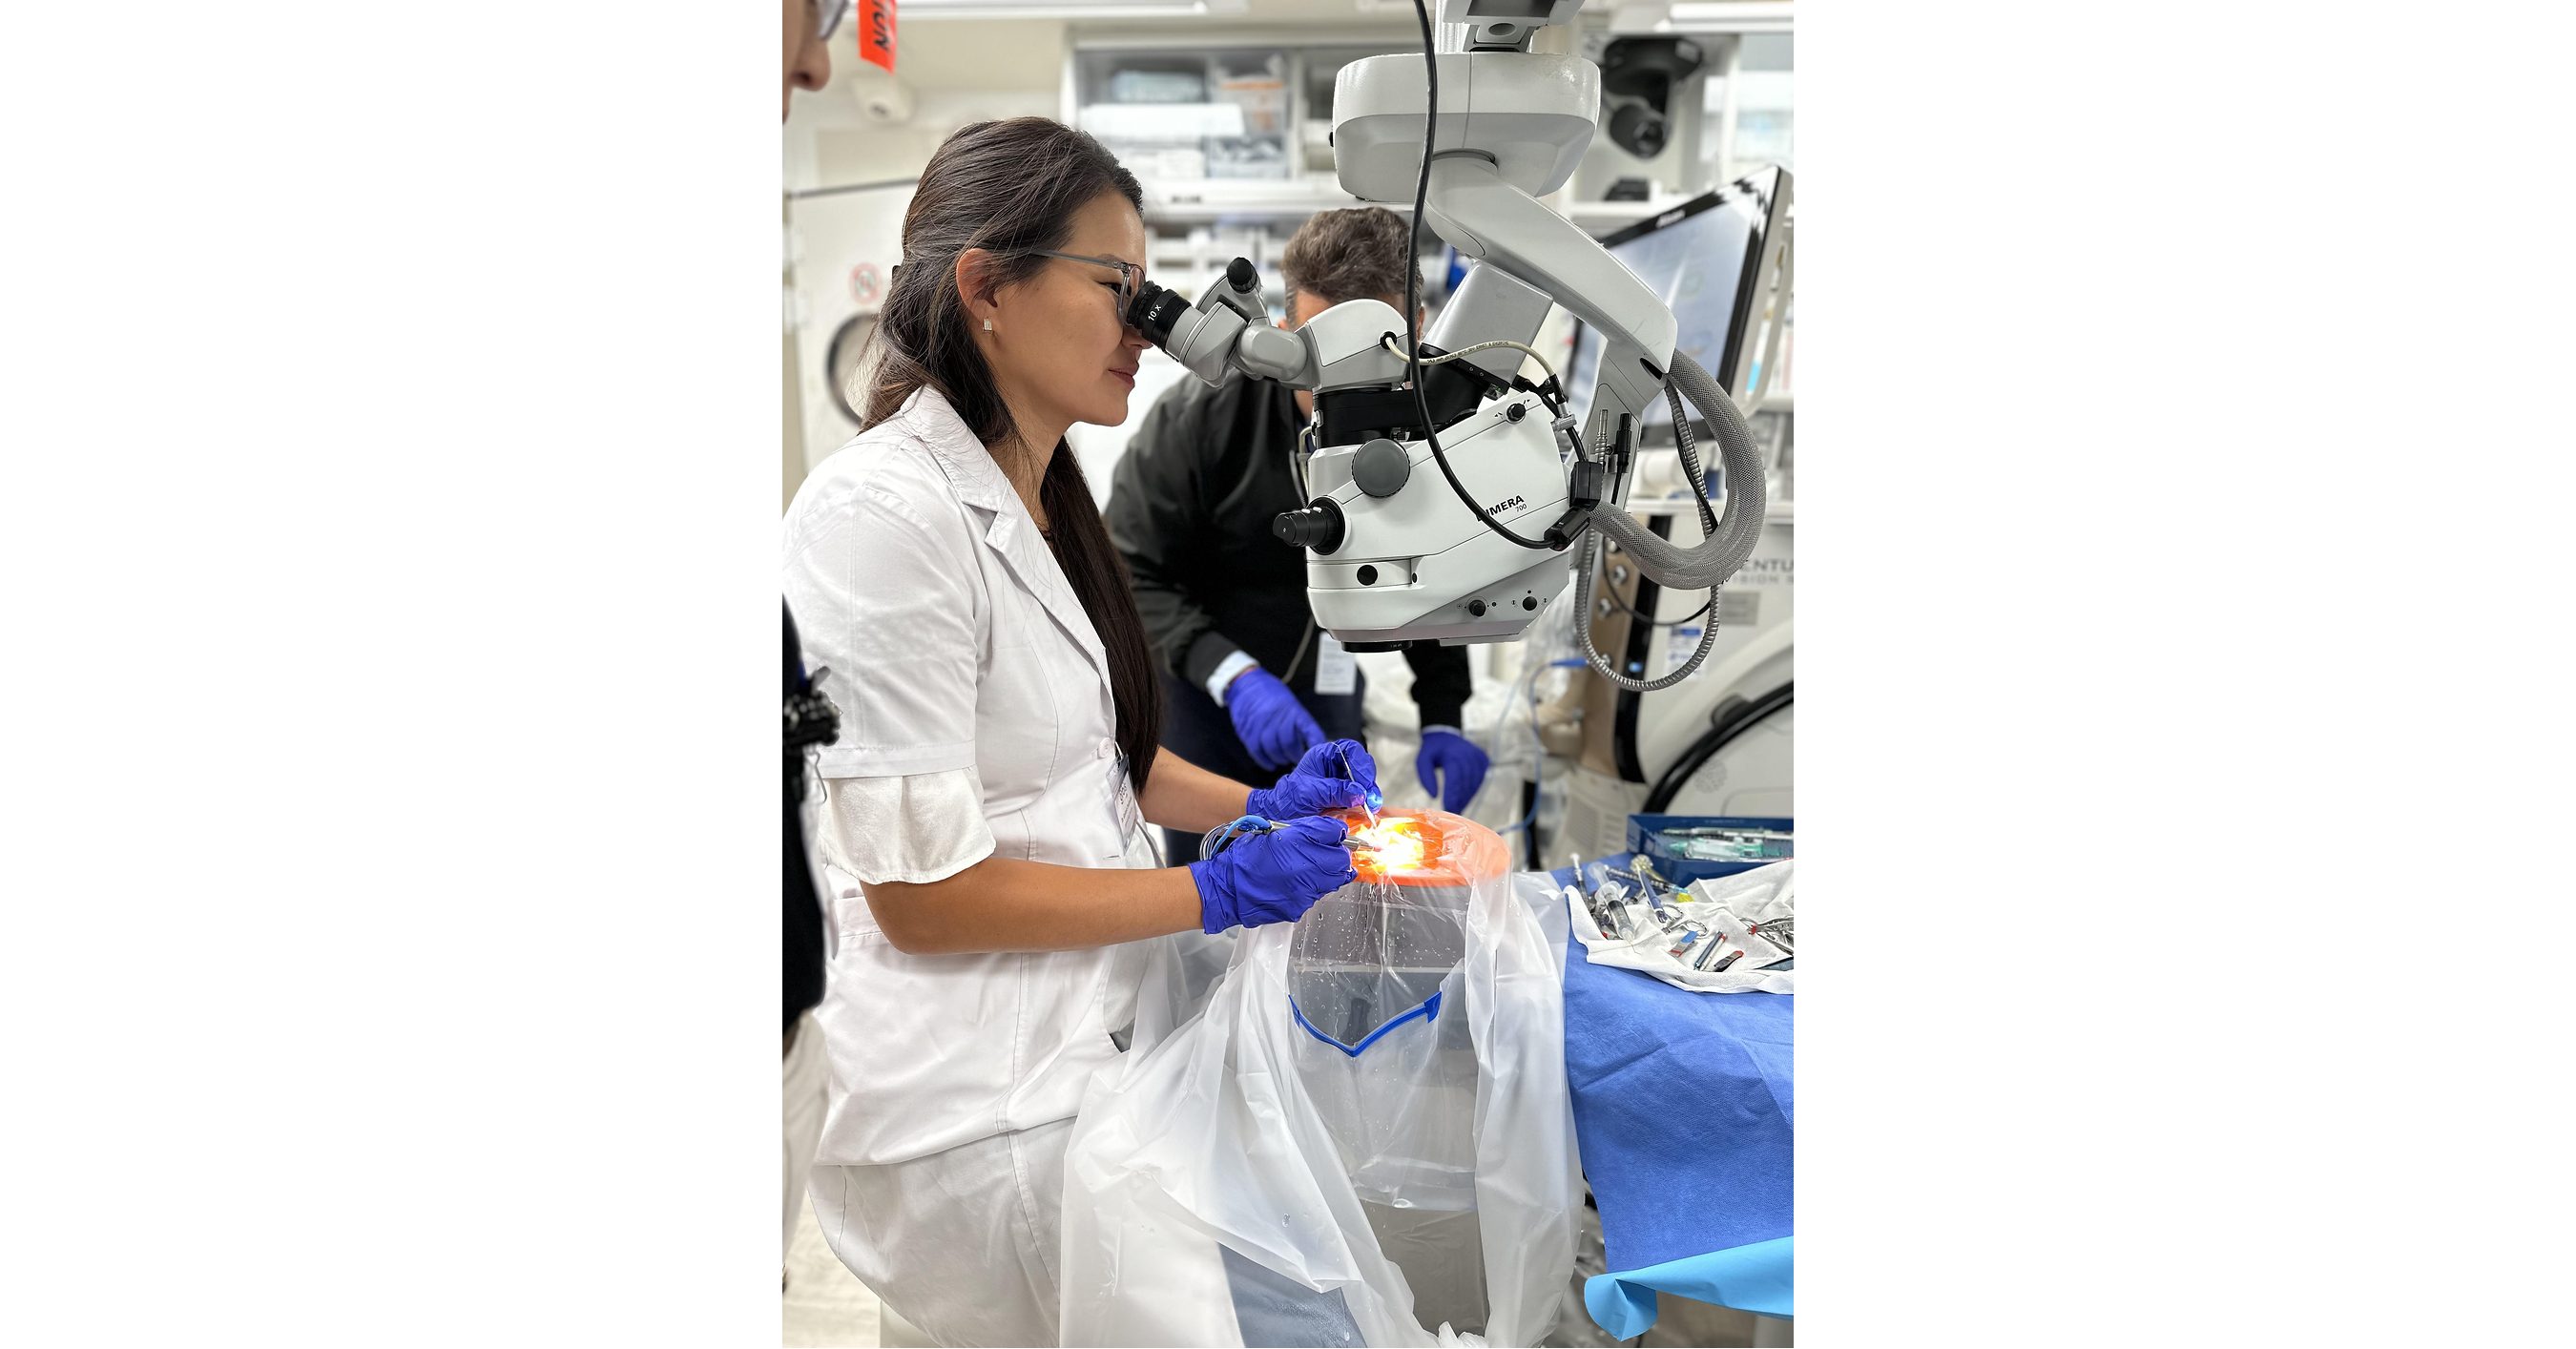
Orbis International launched its first Flying Eye Hospital simulation-based training project in Macau, bringing 70 ophthalmologists and nurses from eight China partner hospitals for advanced mentorship. The program is expected to support care for more than 245,000 patients in China annually and is integrated with Cybersight for ongoing telemedicine and e-learning. The initiative is backed by sponsors including Alcon and OMEGA and supported by Macau’s Civil Aviation Authority and Health Bureau, with Macau donors having raised over $33M since Orbis Macau began in 2006.
Analysis
This reads more like a relationship-management and distribution signal than a hard earnings catalyst. For ALC, the economic value is not the sponsorship itself; it is the repeated insertion of Alcon products and training workflows into the clinician decision stack, which can matter in procedure categories where brand familiarity and surgeon habit drive share over years. The incremental benefit is most likely in China ophthalmology channels, but it is diffuse and probably too small to move near-term estimates.
The competitive implication is that Alcon is defending its moat where switching costs are soft but real: surgeon preference, training ecosystem, and follow-on consumables. That could pressure regional peers in surgical and vision care over a 6-18 month horizon, but only if this kind of engagement converts into higher procedure throughput or better institutional access; otherwise it is just marketing spend with limited P&L leverage. The more important check is whether Alcon can translate these relationship investments into measurable China growth versus JNJ Vision / Bausch + Lomb / Carl Zeiss Meditec.
Contrarian view: the market may over-interpret these philanthropy-driven announcements as evidence of commercial momentum when the actual financial exposure is tiny. The one thing worth watching is whether management starts referencing China procedure mix, surgeon training, or tender wins more explicitly in upcoming commentary; absent that, this is a watch item, not a trade. Falsifiers would be any weakening in China ophthalmology demand, price pressure, or evidence that local competitors are gaining share despite the ecosystem support.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.10
Ticker Sentiment
Key Decisions for Investors
- No new standalone trade on this release; treat ALC as a watch item only. Reassess if upcoming earnings show China surgical growth acceleration or commentary on higher conversion from training programs.
- If already long ALC, hold through the next print but do not add on this news; the upside from ecosystem reinforcement is likely a 6-18 month share-share story, not a 1-3 month multiple catalyst.
- Set an alert on ALC’s China ophthalmology commentary and surgical growth metrics next quarter; a miss or flat growth would falsify the thesis that these brand-building efforts are translating into commercial traction.
- For relative-value investors, consider ALC vs. JNJ (Vision exposure) or Bausch + Lomb-linked comps only if there is hard evidence of China share gains; otherwise avoid forcing a pair on non-economic PR.
- Do not trade FDX/GE/WWD solely off sponsor mentions; any revenue impact from logistics/equipment support is de minimis versus their core segment mix.
More News
- Jim Cramer: Why I am taking the other side of the trade that crushed the market Friday
- Louisiana residents are training for jobs at Meta's largest-ever AI data center: 'Why not get in now?'
- Data Centers, Aerospace, and Machined Parts: This Company's Earnings Just Made the Bull Case for U.S. Industrials
- Should You Buy Costco Stock Before Oct. 30? Here's the Clear Answer.
- By 1973, A Vietnam Vet's Logistics Company Was Down To Its Last $5,000. The Former Marine Took The $5,000 To A Vegas Blackjack Table And Made Enough To Keep The Company Going.
- Asian stocks skid, Wall Street and bonds aided by oil slip