
Tarkett launches In the Making carpet collection for creative expression
Source: PR Newswire
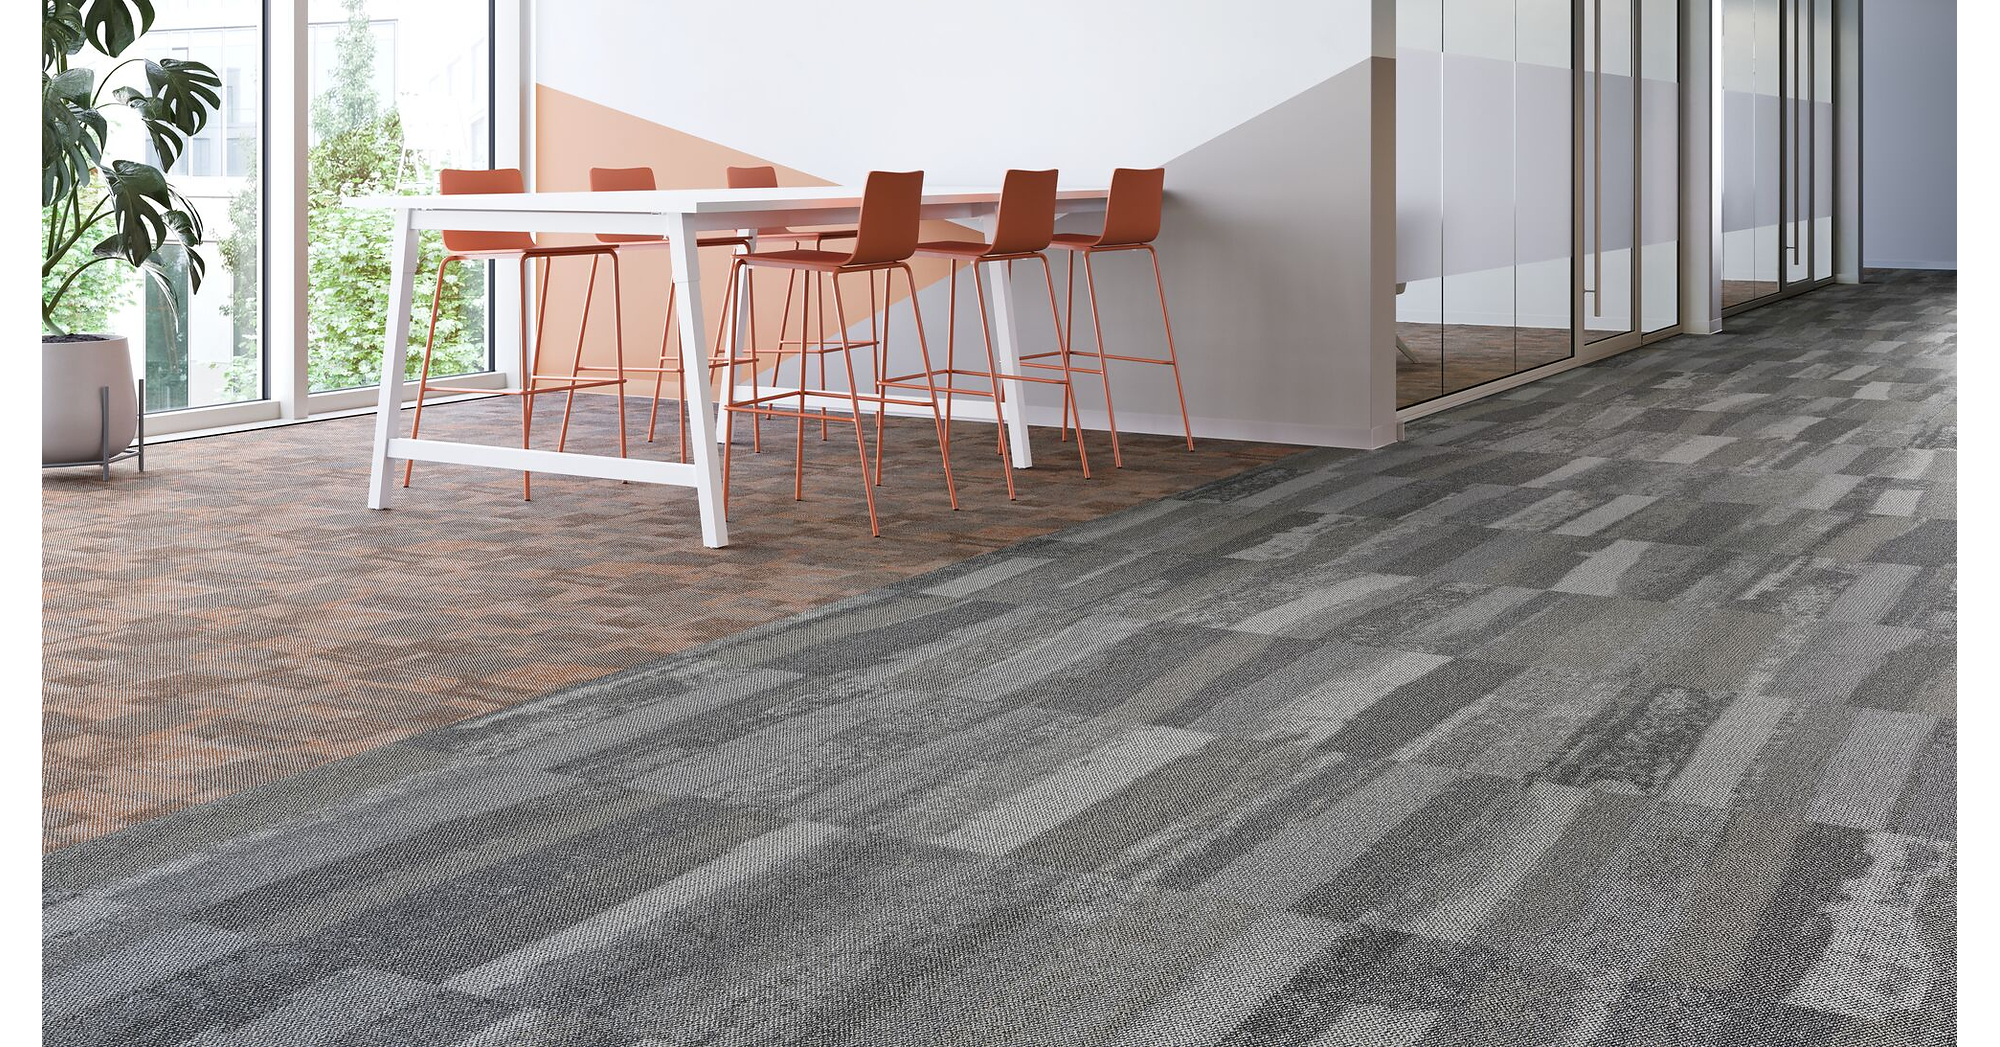
Tarkett launched its “In the Making” commercial flooring collection, featuring three carpet tile/hybrid styles (Traced, Preparation, Gestural) across 12 colorways. The release emphasizes durability and indoor-air benefits, including Powerbond hybrid carpets with moisture-barrier sealed seams and claims that dry vacuuming removes 95% of allergens, plus ethos carpet tile with up to 78% recycled content and Cradle to Cradle Silver certification. The article also highlights Tarkett’s circular-economy ReStart® take-back program and notes net sales of €3.3B in 2025, but provides no financial guidance or near-term earnings impact.
Analysis
This reads more like a procurement and brand-defense update than a revenue catalyst. In commercial flooring, sustainability attributes increasingly function as table stakes in RFPs; they help a vendor stay on the bid list, but they rarely create incremental demand unless a spec changes the installed-product mix or shortens approval cycles. The near-term financial impact is therefore more likely margin support and lower churn in large accounts than a visible step-up in top-line growth.
Relative winners are the suppliers that can credibly prove recycled content, low-VOC chemistry, and closed-loop logistics at scale. That tends to favor pure-play commercial flooring names like TILE, and secondarily broader flooring platforms with commercial exposure such as MHK, if they can convert these claims into higher realized pricing or better win rates. Losers are undifferentiated carpet-tile vendors and import-heavy competitors that must discount to match the compliance narrative without having the same manufacturing economics.
The contrarian risk is that investors overestimate the commerciality of ESG language here. If office and institutional renovation budgets stay soft, this becomes a marketing overlay rather than an earnings driver; the real catalyst path is 1-3 months of backlog/order commentary and 6-18 months of nonresidential capex recovery. What would falsify the bullish read is any evidence that spec wins are not translating into higher mix, better gross margin, or a tighter backlog-to-billings trend.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- No standalone long/short in WWRL on this release; treat it as a watch item until channel checks or earnings show mix or backlog improvement.
- Relative long TILE / short MHK over 1-3 months if commercial flooring demand stays resilient; the cleaner ESG/commercial positioning should support multiple premium if orders inflect. Invalidate if TILE prints weaker backlog or guide-downs on commercial pricing.
- For a lower-conviction expression, buy 3-6 month call spreads on TILE only after confirmation that commercial renovation demand is holding; risk/reward is better if the market starts rewarding ESG credentialing with spec wins.
- Avoid extrapolating this into a broad flooring rally; if nonresidential capex rolls over, use any strength in TILE/MHK to fade the move rather than chase it.
More News
- Order to limit Starshield for Ukraine came from inside White House: Reuters reports
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- FDA approves Enspryng for thyroid eye disease treatment
- Giant Taiwanese chipmaker TSMC confirms it’s in talks with Elon Musk to join ‘Terafab’ complex in Texas: ‘The AI market continues to be very strong’
- The Tesla Roadster 2 Is Here—and It Flies
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Can Hedge Funds Use ChatGPT? A Control Framework
- Palantir (PLTR) Q4 2025 Earnings: 70% Revenue Growth, Then an 11% Single-Day Crash