
RevHD Awarded U.S. Patents for Wheel Seal Technology
Source: PR Newswire
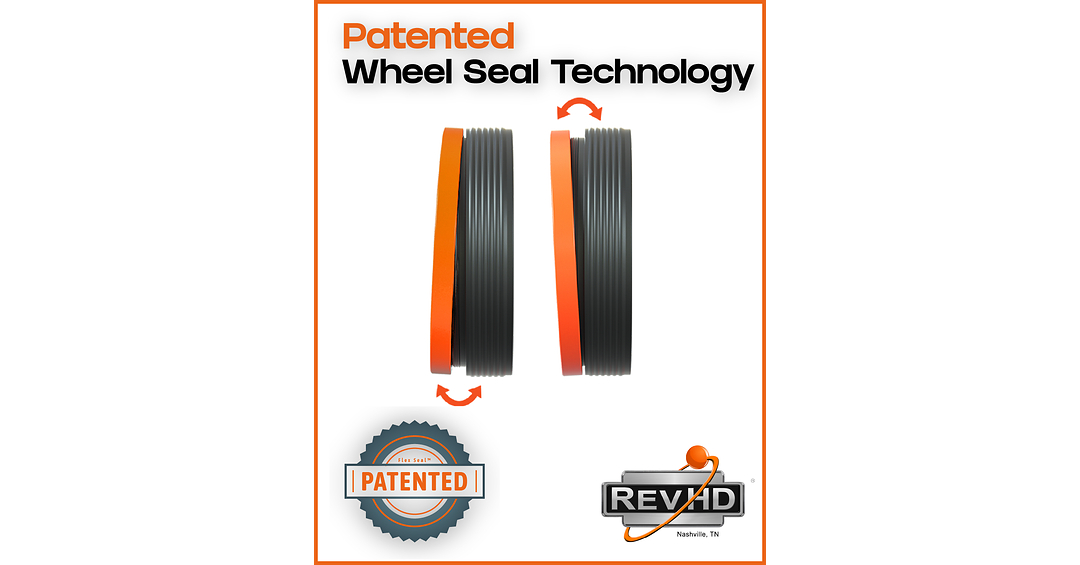
RevHD was awarded two U.S. patents for its Flex Seal™ wheel seal technology, designed to reduce installation-related failures by accommodating normal wheel-end movement and minimizing cocked seals (a common cause of premature failure). The patents cover core technology behind Rev Max and Rev 1 wheel seals and are positioned to make installation easier and more consistent for technicians. Given RevHD is privately held, the news is likely modest for markets but modestly positive for the company’s proprietary technology moat.
Analysis
This is more validation of a niche aftermarket moat than a near-term earnings event. The economic value sits in reducing install-error-driven warranty claims and technician time, which matters most for fleet operators and distributors that live on uptime, not for OEM build rates. Because the company is private, the immediate public-equity read-through is limited; any benefit to public names would come only if this changes channel share in a slow-moving, qualification-heavy maintenance market.
The likely losers are commodity seal suppliers and private-label distributors that compete on price but not on field performance or installation simplicity. If the product truly cuts comebacks, the second-order effect is less replacement demand, which can offset some volume gains for the category; that makes this more about share shift than category expansion. Public commercial-vehicle names like CVGI have no obvious direct exposure, so I would not anchor on them unless there is evidence of broader fleet capex or maintenance-cycle improvement.
Catalyst timing is long, not days: patents can support pricing power over 6-18 months, but the market will only care if RevHD can show dealer penetration, lower warranty rates, or OEM/large-fleet adoption. The contrarian miss is that patent protection alone does not create switching; in maintenance consumables, process discipline and approved-supplier lists often matter more than IP. If adoption data is absent, the right posture is watchful skepticism rather than a momentum trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.10
Key Decisions for Investors
- No direct trade in CVGI or TSTS on this news; treat as immaterial to near-term estimates unless subsequent commentary shows wheel-end aftermarket exposure.
- Watchlist: if RevHD publishes quantified warranty/comeback reduction or named fleet/dealer adoption over the next 1-3 months, re-underwrite the durability thesis for aftermarket component suppliers and potential private-label losers.
- If seeking a public proxy, prefer a small tactical long in a high-quality aftermarket maintenance name like DORM or TKR only on evidence of share gains; otherwise stay flat because the current signal is too weak to justify a risk position.
- Use the next earnings cycle to test the thesis: any mention of increased warranty expense, pricing pressure, or share loss in adjacent wheel-end consumables would falsify the 'defensible moat' narrative.
- Do not buy the patent story as a standalone catalyst; wait for measurable revenue mix, gross-margin improvement, or distributor fill-rate data before assigning valuation premium.
More News
- Order to limit Starshield for Ukraine came from inside White House: Reuters reports
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- FDA approves Enspryng for thyroid eye disease treatment
- Giant Taiwanese chipmaker TSMC confirms it’s in talks with Elon Musk to join ‘Terafab’ complex in Texas: ‘The AI market continues to be very strong’
- The Tesla Roadster 2 Is Here—and It Flies