
World Brand Lab Releases Asia's 500 Most Influential Brands of 2026
Source: Newswire
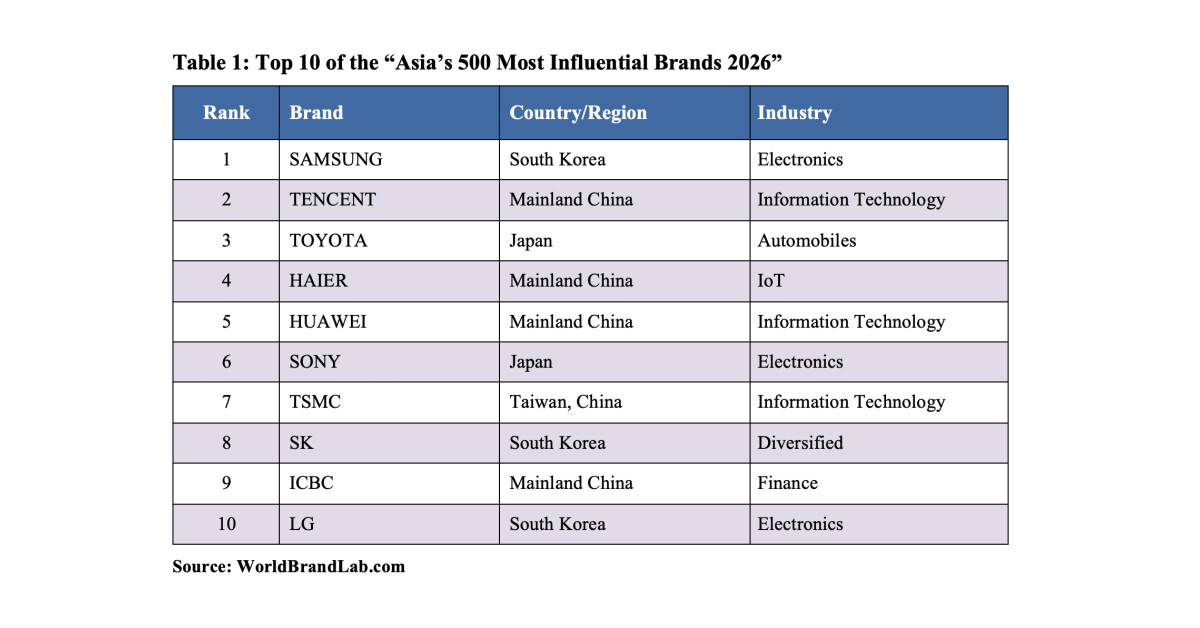
World Brand Lab ranked Samsung, Tencent and Toyota as Asia's three most influential brands in its 2026 list, which includes 500 brands across 20 countries and regions. China accounted for 223 brands, or 44.6% of the list, while Chinese consumer loyalty toward domestic brands rose to 73% from 36% more than a decade ago. The ranking incorporated an AI Influence Index for the first time, with information technology contributing 17 of the 48 new entrants as AI adoption boosts the sector's brand influence.
Analysis
This is not an investable fundamental catalyst by itself: the ranking is methodology-driven, issuer-adjacent promotional content, and has no demonstrated link to revenue, pricing, or cash flow. The relevant signal is directional only: consumer preference is becoming more locally anchored across Asia, raising the cost of share retention for foreign consumer brands and reducing the value of global brand spend unless it is paired with localized products, channels, and service ecosystems.
TM is best positioned among the named ADRs because localized manufacturing, dealer density, financing, and hybrid product fit make its Asian demand profile more defensible than premium-import competitors. The 1-3 month read-through should come from China and ASEAN retail-sales/registration data, transaction-price trends, and incentive spending; a sustained mix shift toward domestic Chinese EVs would pressure TM's unit growth and force greater discounting even if total regional auto demand remains healthy.
For TSM, the AI-branding angle is economically irrelevant; the actionable issue is whether Asian AI adoption converts into incremental leading-edge silicon demand rather than marketing expenditure. That requires evidence in hyperscaler capex, accelerator orders, and utilization/pricing at advanced nodes over the next two earnings cycles. SONY has the more nuanced exposure: AI-driven content discovery can reduce customer-acquisition costs for PlayStation and music, but recommendation-led consumption also concentrates bargaining power with platforms and could dilute catalog economics over 6-18 months.
Contrarian view: markets may over-read rising domestic loyalty as a blanket anti-foreign demand shock. Japanese and Korean incumbents retain trust advantages in durable goods, while domestic preference can fragment rather than consolidate markets; the larger risk is margin competition, not necessarily volume collapse. Avoid treating the ranking as confirmation of a broad long Asia-tech thesis.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.22
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on the ranking; treat it as a watch-item rather than a catalyst, given the low fundamental impact and lack of independently verifiable financial linkage.
- Maintain TM as the preferred liquid Japan auto exposure versus a basket of China EV names only if China/ASEAN registrations and TM regional incentives remain stable through the next two monthly releases. Exit or hedge if China retail share declines for two consecutive months while incentives rise, signaling margin defense rather than resilient demand.
- For TSM, wait for confirmation from next-quarter advanced-node utilization, wafer pricing, and AI accelerator supply-chain commentary before adding. A long TSM position is attractive only if management indicates sustained tight leading-edge capacity; evidence of utilization normalization or weaker N3/N2 pricing would falsify the incremental AI-demand thesis.
- Monitor SONY's next two earnings reports for PlayStation active-user engagement, first-party software mix, music streaming margins, and marketing expense. Consider a tactical long only if AI-enabled distribution improves operating leverage without elevated content or promotion spend; rising opex with flat engagement would argue for avoiding the name.
More News
- An unaffordable car market highlights Iran’s cost-of-living crisis
- Applied Materials vs. Nvidia: Which Tech Stock Is a Better Buy in 2026?
- Better Artificial Intelligence Stock: Aehr Test Systems vs. KLA Corporation
- Could US pull one-third of troops from Europe? What that would mean
- Trump vows to create an ‘AI Force’ and nods to justice system after rejecting calls to slow down industry. ‘Rather, we will cherish it’
- Australia seeks big tech support for internet safety, AI regulation