
FDA advisers are reviewing a multicancer-detection test. Medicare coverage could follow.
Source: MarketWatch
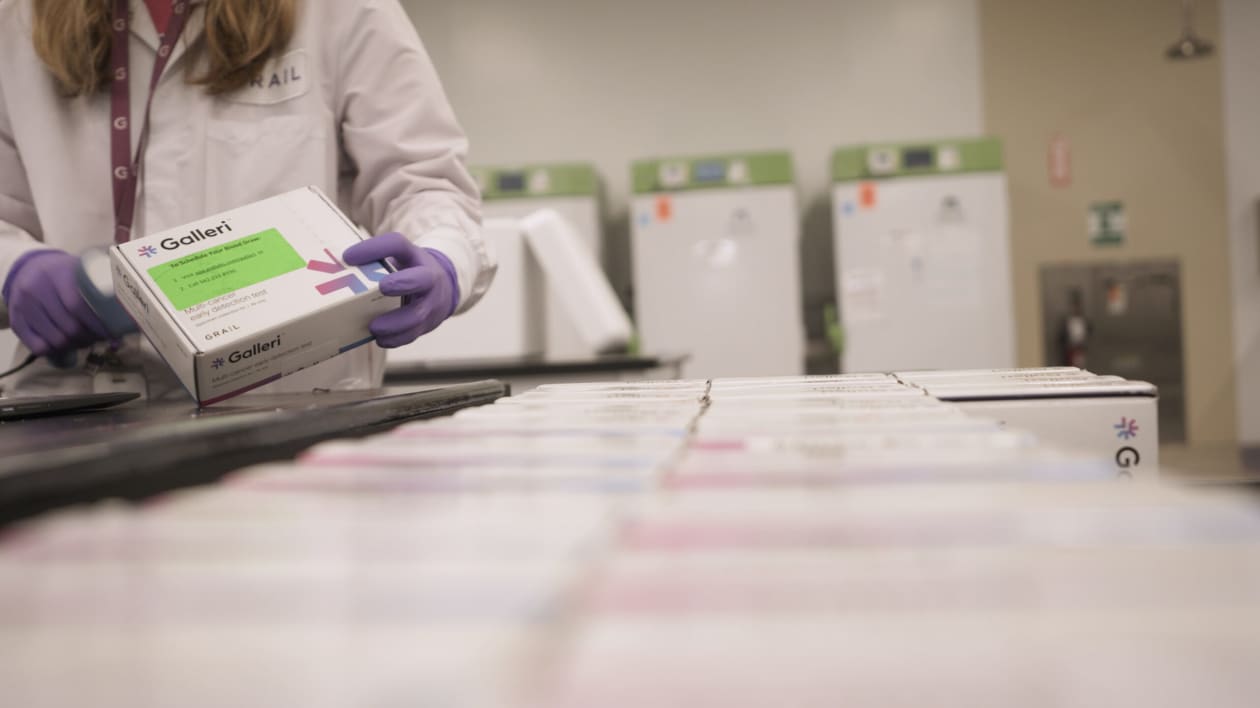
FDA advisers are reviewing Grail's Galleri multicancer-detection blood test, a potential step toward Medicare coverage that could materially expand access beyond its $949 direct-to-consumer price. Galleri is designed to detect more than 50 cancers, but a major study failed to demonstrate that it could identify cancers at later stages, creating uncertainty around clinical utility and regulatory support. The review is a meaningful catalyst for Grail and potentially Illumina, though coverage prospects remain contingent on the evidence assessment.
Analysis
The investable question is not whether an FDA discussion occurs, but whether the agency creates an evidentiary pathway that lowers reimbursement risk. A favorable procedural outcome could expand GRAL's addressable market from affluent self-pay users to primary-care channels, but Medicare coverage is unlikely to be automatic: CMS will focus on mortality benefit, downstream diagnostic utilization, and budget impact. The failed endpoint materially raises the probability of a narrow label, coverage-with-evidence-development framework, or prolonged post-market study requirement rather than broad near-term reimbursement.
GRAL has asymmetric event sensitivity over days to weeks because its valuation is dominated by adoption optionality, while ILMN's exposure is principally through its retained economic relationship and reduced strategic overhang. Yet broad coverage could initially be margin-negative for GRAL: reimbursement requires payer contracting, prior authorization infrastructure, clinical-navigation capacity, and funding of follow-up diagnostics; a low realized reimbursement rate or high false-positive workup burden would constrain gross-margin expansion. HIMS is a distribution-option beneficiary only if it can acquire eligible patients below its current CAC and attach testing without bearing clinical-liability or reimbursement complexity; there is no basis yet to underwrite material revenue contribution.
Consensus may overread any favorable adviser commentary as a Medicare catalyst. The more durable inflection is evidence that test-positive patients receive actionable treatment earlier and that payers accept the diagnostic cascade economics, likely a 6-18 month process. Thesis falsification for a bullish GRAL view: FDA requests a new randomized mortality study before commercial expansion, CMS signals noncoverage absent mortality data, or quarterly test volume grows while gross profit per test declines due to navigation and channel costs.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
-0.05
Ticker Sentiment
Key Decisions for Investors
- Treat GRAL as an event-driven watch, not a core long, into the advisory process: initiate only after regulatory language clarifies intended-use breadth and confirm that management provides realized reimbursement and gross-profit-per-test data. A broad pathway can drive a sharp multiple rerating; a study requirement creates meaningful downside because self-pay demand alone is unlikely to support reimbursement-optionality valuation.
- For a defined-risk bullish expression, use a small GRAL call spread dated 6-9 months out rather than common stock, sized to potential premium loss. Enter after the initial headline reaction fades; exit or hedge if FDA communications require prospective outcomes evidence as a condition of expanded use.
- Avoid using HIMS as a direct multicancer-screening proxy. Reassess only if HIMS discloses an exclusive or economically material distribution arrangement, attach rates, CAC impact, and responsibility for clinical follow-up; absent those disclosures, any sympathy move is likely tradable rather than fundamental.
- Maintain ILMN exposure separately from the screening thesis. The cleaner catalyst is evidence that higher GRAL volume translates into incremental sequencing consumable pull-through or value realization; without disclosed volume economics, ILMN's sensitivity is too indirect to justify a paired long ILMN/short GRAL trade.
More News
- FDA Advisory Committee Votes In Favor of Approval of GRAIL's Galleri® Multi-Cancer Early Detection Test
- OpenAI’s agent hacked Australia’s Medicare website—the latest rogue AI incident that the company didn’t know about for months
- Oil industry warns a diesel export ban will raise fuel prices as Trump weighs restrictions
- SoftBank shares jump over 7% after $11.1 billion bond issuance to fund OpenAI bet
- Australia says OpenAI agent hacked Medicare portal
- US aviation sanctions disrupt Iran flights, push travellers overland
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Reading Conviction in the Tape: What Level 3 Order Book Data Really Tells Discretionary PMs
- AI Tools for CFA Charterholders: An Evidence Standard