
The Bascom Group Completes $62.5 Million Refinancing of Viceroy Observatory Park in Denver, CO
Source: PR Newswire
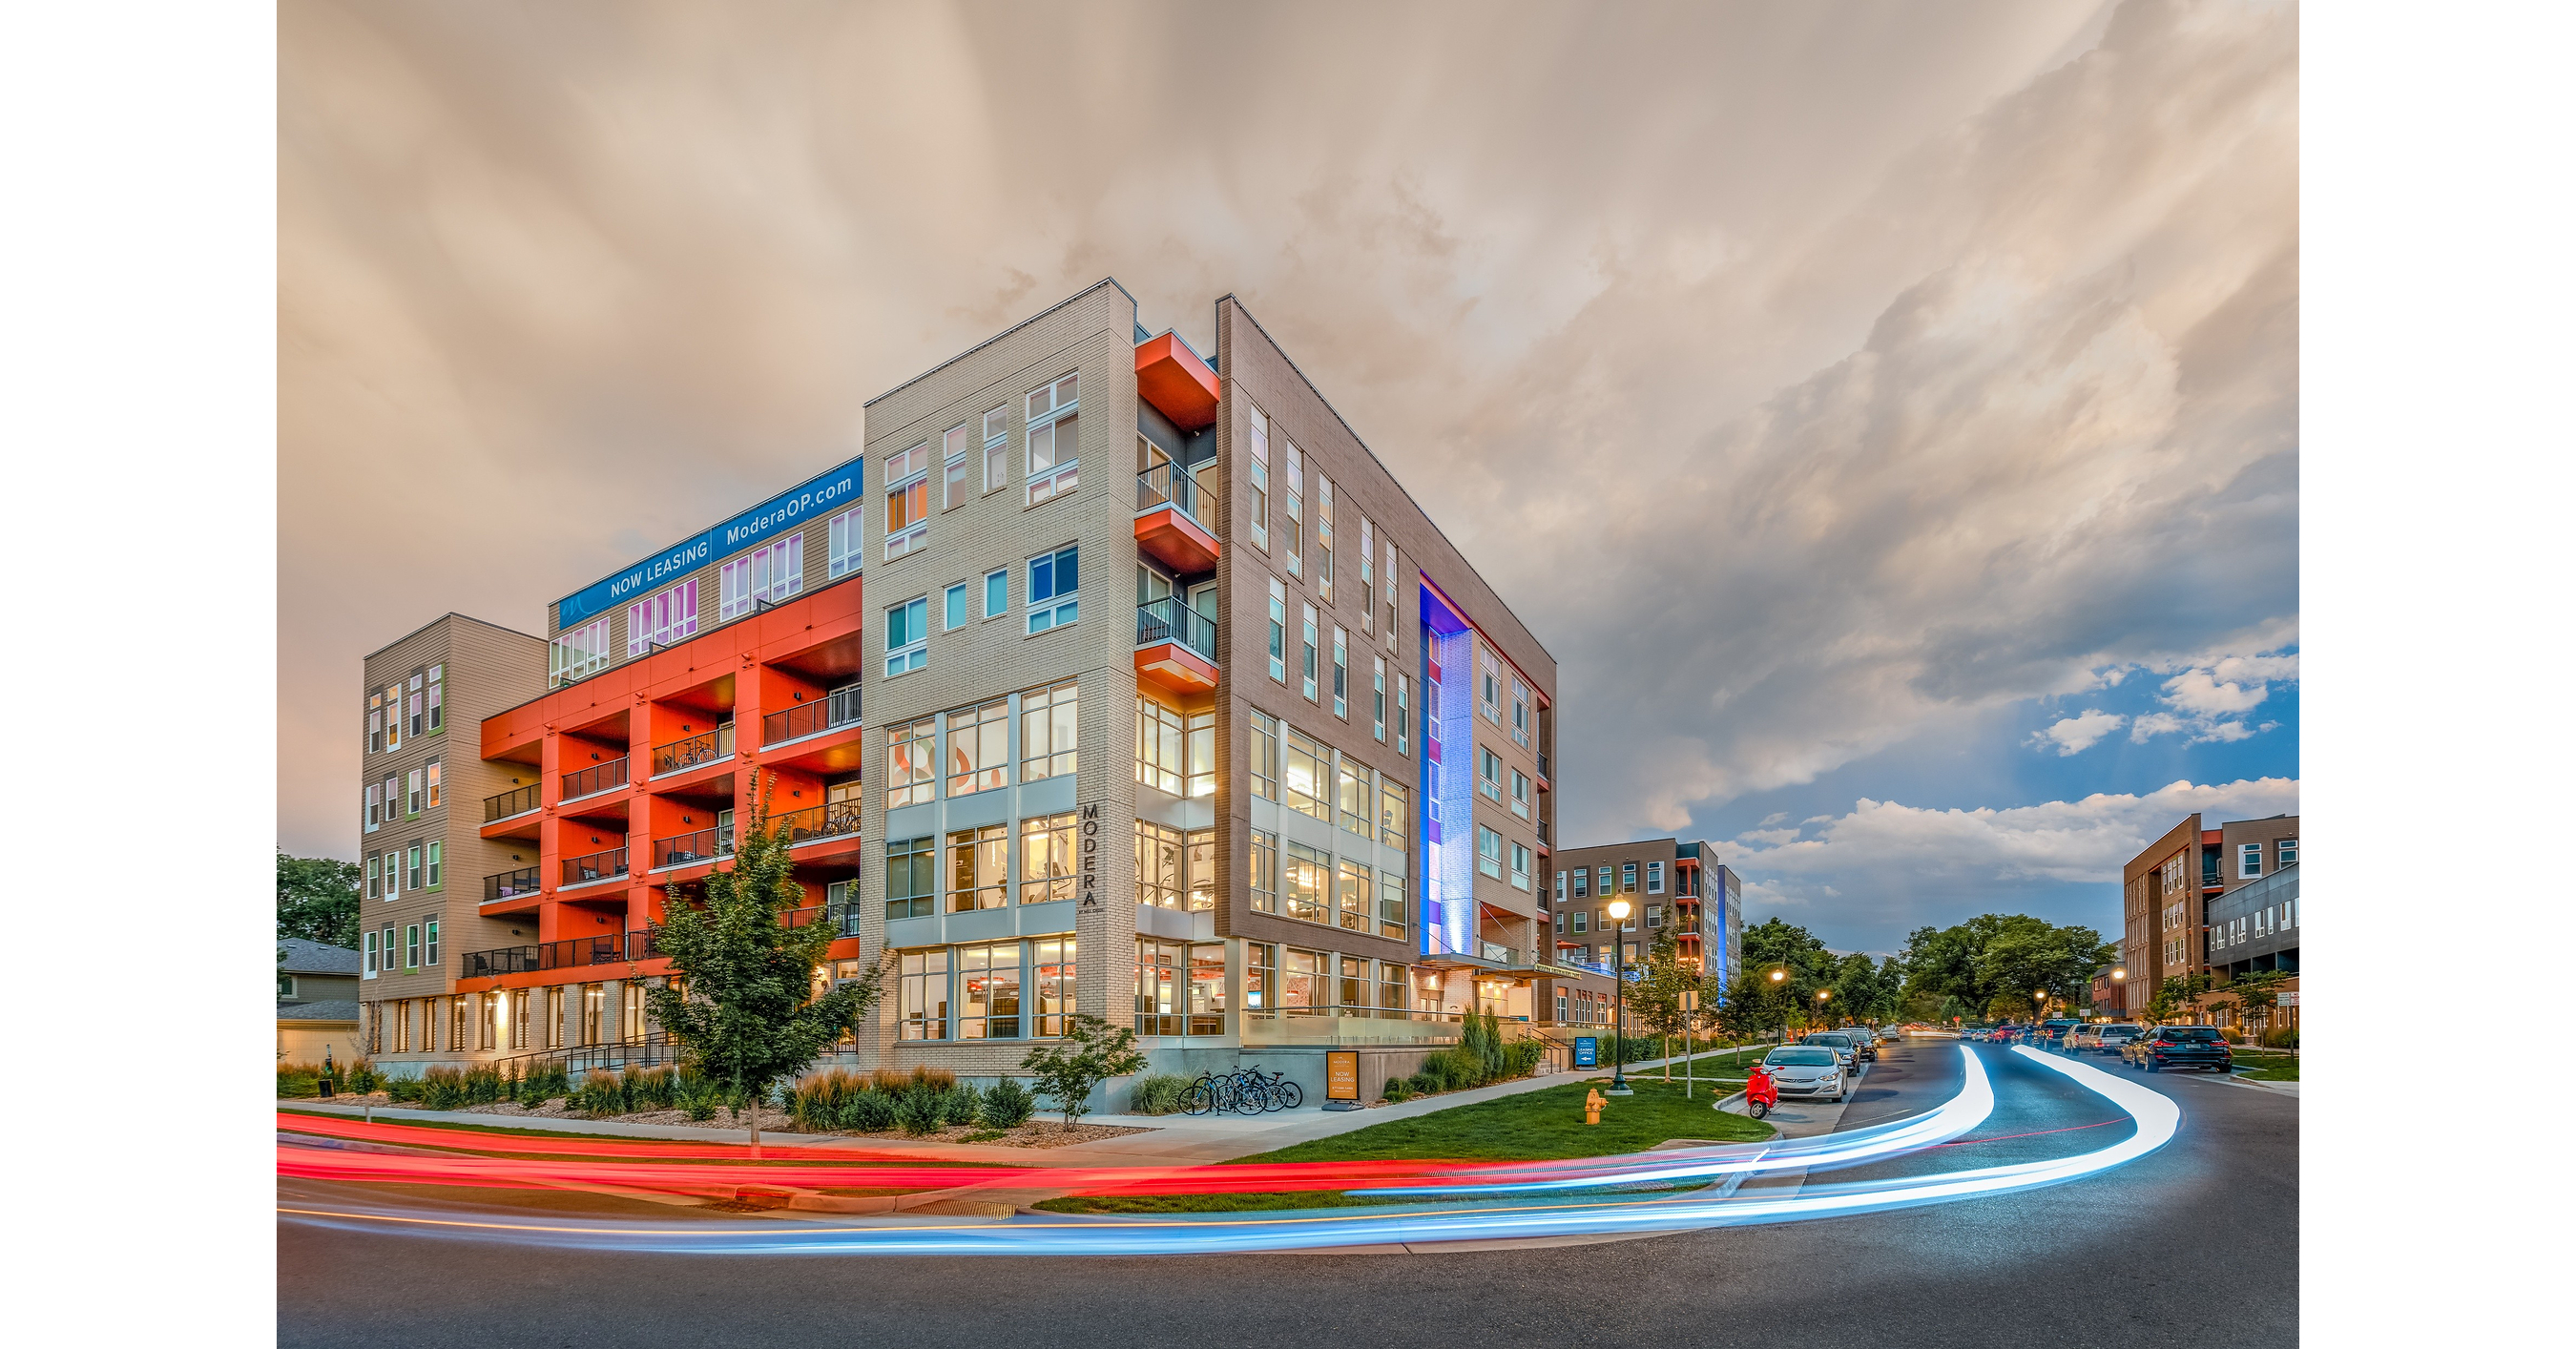
Bascom completed a $62.5 million refinancing for its 275-unit Viceroy Observatory Park in Denver, replacing a loan that matured in October 2026 with a two-year initial term and three one-year extension options, reducing near-term maturity risk. Denver multifamily conditions show early rebalancing: trailing 12-month absorption was 7,346 units versus 6,481 completions, occupancy rose 40 bps year over year to 93.9%, and rents gained 0.6% quarter over quarter but remained 2.9% below a year earlier. Bascom said it will continue executing its business plan amid capital-market headwinds.
Analysis
Denver multifamily: early stabilization, not yet a rent recovery. The key second-order signal is that debt was available for a seasoned, well-located asset despite a difficult capital-markets backdrop; this modestly lowers the probability that near-term maturities force distressed sales among comparable owners. But one refinancing of a high-quality property does not establish broad lender appetite, and the two-year initial term shifts rather than eliminates refinancing risk. The loan’s pricing, rate structure, amortization, covenants, and property-level coverage are undisclosed, so neither leverage nor borrower economics can be inferred from the principal amount.
For JLL, the transaction is a small execution proof point and potential pipeline indicator, not a material standalone earnings catalyst. The more consequential path is Denver operating performance: supply easing supports occupancy and pricing over the next 6–18 months, but rent remains below year-ago levels, so revenue growth may lag occupancy improvement. A renewed delivery wave, weaker employment, or higher-for-longer rates could stall recovery and pressure asset values before extensions are exercised.
Contrarian read: the release frames refinancing as confidence, but it may primarily reflect asset quality and sponsor execution. The market should not extrapolate this to weaker properties or treat two sequential quarterly rent increases as a durable inflection. Near term, this is a watch signal for credit availability, not a basis to re-rate JLL or the apartment sector.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- No standalone JLL trade: treat the refinancing as incremental evidence of transaction activity, but require a sustained improvement in JLL’s broader capital-markets volumes or guidance before changing the position.
- Add Denver multifamily exposure only on confirmation over the next 1–3 quarters: track net absorption versus completions, occupancy, effective rents and concessions. A return to positive year-over-year rent growth alongside stable occupancy would strengthen the recovery case.
- For any Denver apartment or credit exposure, verify the new loan’s rate type, all-in cost, amortization, covenants, and property-level debt-service coverage. Reassess if leasing weakens, concessions rise, or the asset cannot demonstrate coverage ahead of the initial term’s expiry.
- Falsification watch: renewed supply growth or a deterioration in Denver employment that reverses absorption and occupancy gains would undermine the stabilization thesis; do not interpret the refinancing alone as evidence of market-wide valuation recovery.
More News
- Further turmoil could be in store for tech stocks. What to watch in the week ahead
- Elon Musk once said the Cybertruck would be Tesla’s ‘best product ever.’ Now he’s winding down production
- Fox completes its $22B acquisition of Roku
- Elanco Shares Jump After Q3 Beat and Outlook Raise
- FTSE 100 today: Stocks slump as global tech rout deepens
- 10-year Treasury yield surges after much stronger-than-expected October jobs report