
DAR GLOBAL ENREGISTRE UNE CROISSANCE DE 66 % DE SON CHIFFRE D'AFFAIRES AU PREMIER SEMESTRE 2026, LA VALEUR BRUTE DE DÉVELOPPEMENT DE SON PORTEFEUILLE ATTEIGNANT 23 MILLIARDS DE DOLLARS AMÉRICAINS
Source: PR Newswire
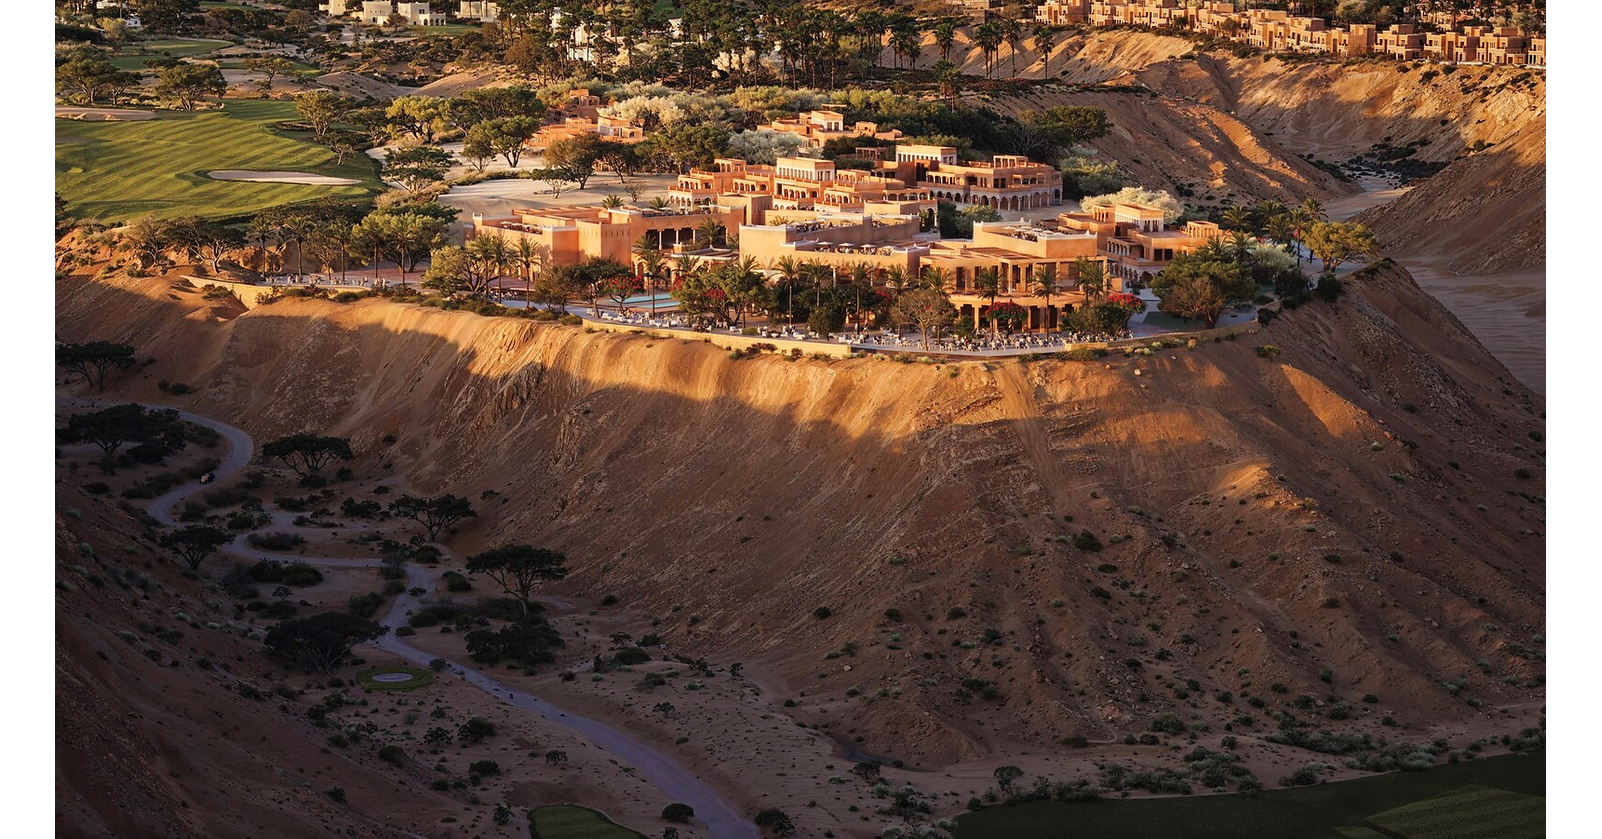
Dar Global reported H1 2026 revenue growth of 66% to $258.0 million, while net profit surged 149% to $30.4 million and EBITDA rose 73% to $46.3 million. Gross margin expanded to 34% from 31%, and portfolio GDV nearly doubled year over year to $23.0 billion, supported by $3.9 billion of contracted sales across 4,380 units. The luxury developer held $579.3 million of available liquidity and secured a $250 million syndicated term loan, while advancing major Saudi and Dubai Trump-branded developments.
Analysis
DAR’s reported growth should not be capitalized at a full-cycle luxury-property multiple until investors can reconcile contracted sales with cash collections, construction commitments, and cancellation rates. Development revenue is inherently lumpy and milestone-driven; the key near-term question is whether the company’s available liquidity comfortably covers land, infrastructure, and tower-construction obligations without another equity raise or materially higher-cost debt. The recently expanded pipeline increases execution and working-capital risk materially over the next 12-36 months, particularly if Gulf off-plan buyers slow deposits.
The Trump and Aston Martin branding strategy can support pricing power and lower sales-and-marketing intensity, but it also concentrates demand in a narrow cohort of international ultra-high-net-worth buyers. AML is a narrative beneficiary rather than a financial one: unless management discloses meaningful recurring licensing revenue, unit economics, or order-book conversion attributable to branded residences, the effect on Aston Martin earnings is immaterial. More relevant second-order beneficiaries are Dubai/Saudi contractors and building-material suppliers, although fixed-price construction contracts could transfer inflation risk from DAR to contractors.
Consensus may overvalue gross development value as if it were backlog revenue. GDV is sensitive to assumed selling prices and project timing, while development margins can compress rapidly if incentives rise or completion dates slip. Over the next 1-3 months, the equity can remain supported by presale announcements and project awards; over 6-18 months, valuation should hinge on operating cash flow, net debt including project finance, presale conversion, and whether gross margin remains above the prior-cycle level.
The bullish thesis is falsified by slowing reservation/collection disclosures, cancellation rates above historical levels, a material increase in net debt or restricted cash, or gross-margin guidance falling below the low-30% range. A sharp decline in Dubai prime-residential transactions, Saudi project-permitting delays, or a sustained rise in regional funding costs would expose the duration embedded in the development pipeline.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.78
Ticker Sentiment
Key Decisions for Investors
- DAR: maintain a tactical long only after verifying current market capitalization, free float, average daily liquidity, and the split between unrestricted versus project-restricted cash. Target a 3-6 month rerating on presale conversion and cash-flow disclosure; size conservatively given London small-cap liquidity and development-cycle risk.
- DAR risk control: reduce or exit if the next trading update shows weaker collections/cancellations, incremental debt without matched presales, or margin guidance below 30%. Avoid treating GDV growth as a standalone earnings catalyst.
- AML: no standalone trade from the branded-residence linkage. Set an alert for quantified licensing income, minimum guarantees, or evidence that the arrangement improves AML automotive order intake; absent that disclosure, the expected P&L contribution is unlikely to justify a position.
- For a cleaner regional construction-demand expression, monitor listed UAE/Saudi contractors and cement suppliers once contract terms and material pass-through mechanisms are disclosed; do not initiate solely on headline project awards because fixed-price execution can be margin-negative in an inflationary cost environment.
More News
- Asian stocks dip, bonds in focus after torrid September
- China’s Property Crisis: From Evergrande Collapse to Beijing’s Latest Measures
- Paramount Skydance prices $42 billion debt for Warner Bros deal
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
- Why is Nidec stock plunging today?