
Jack Henry & Associates, Inc. Reports First Quarter Fiscal 2027 Results
Source: PR Newswire
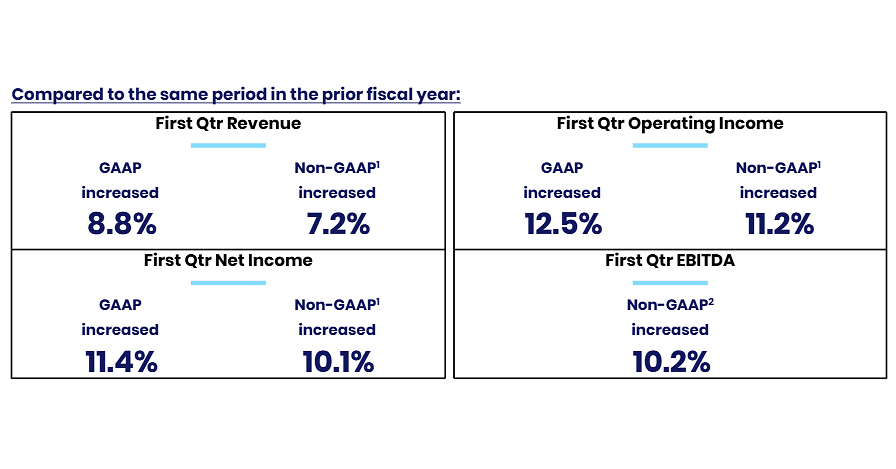
Jack Henry reported fiscal Q1 2027 revenue of $701.5 million, up 8.8% year over year, and diluted EPS of $2.28 versus $1.97, up 15.6%; non-GAAP adjusted revenue rose 7.2% and adjusted operating income increased 11.2%. Management said results exceeded its August outlook and cited strong demand, while FY2027 guidance calls for GAAP revenue of $2.698–$2.718 billion and EPS of $7.47–$7.51. The company repurchased $71 million of stock at an average $153.47 per share; cash was $25.4 million and debt outstanding was $85 million at quarter-end.
Analysis
The constructive signal is the mix shift toward cloud and transaction processing: these recurring activities can improve revenue visibility and deepen bank-client switching costs, supporting JKHY’s quality premium if growth persists. But don’t annualize the headline EPS growth: lower share count from repurchases and a lower tax rate amplified per-share growth, while deconversion revenue is excluded from adjusted results and was higher year over year. Management’s “exceeded consensus” characterization is not independently verifiable here.
The key near-term test is tomorrow’s call: validate whether the pipeline is converting into implementations and recurring volumes, and whether the full-year outlook has room to rise. Over 1–3 months, watch adjusted core growth and cloud costs; R&D rose faster than revenue, and cloud/security consumption may constrain operating leverage. Over 6–18 months, successful migration to hosted services and faster payments could strengthen retention, but also requires sustained software investment. Elevated capitalized software spending and buybacks above quarterly free cash flow, alongside higher borrowings and lower cash, make cash conversion and capital allocation worth monitoring—not yet a balance-sheet thesis.
Contrarian read: a strong quarter does not automatically warrant chasing. Annual adjusted revenue guidance implies mid-to-high-single-digit growth, and reported revenue benefited from deconversions; underlying recurring growth is the more durable valuation driver. Competitors such as Fiserv and FIS face the same bank technology spend, but JKHY’s growth does not establish share gains without client wins or retention data.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- Favor a measured long JKHY on post-call weakness rather than buying the release reaction; add only if management confirms recurring cloud/processing demand and maintains or raises FY27 adjusted guidance. No valuation data here supports a price target.
- Use the November 4 call as the immediate catalyst: verify pipeline conversion, implementation capacity, client retention/deconversions, and cloud/security cost trends. A weaker recurring-growth outlook or margin pressure would invalidate the add-on-long case.
- Track quarterly free-cash-flow conversion, capitalized software, borrowings, and repurchases together. If buybacks continue to exceed free cash flow while debt rises, treat capital returns as less supportive of per-share value than headline EPS suggests.
More News
- Jack Henry&Associates earnings beat by $0.22, revenue topped estimates
- Binance co-CEO Richard Teng says hackers used fake job interviews, AI tool to steal $6.3 billion in crypto 108511116
- AMD stock jumps 7% on earnings as data center revenue nearly doubles
- Marvell Technology could plunge on latest multibillion-dollar acquisition
- Disney Plans Thousands of Layoffs Companywide
- AMD rides data center riches to ‘largest and most profitable’ quarter in history