
JW Marriott Unveils Plans for The Ocean Cliffs at Dana Point, a JW Marriott Resort Following a Multi-Million-Dollar Transformation
Source: PRWeb
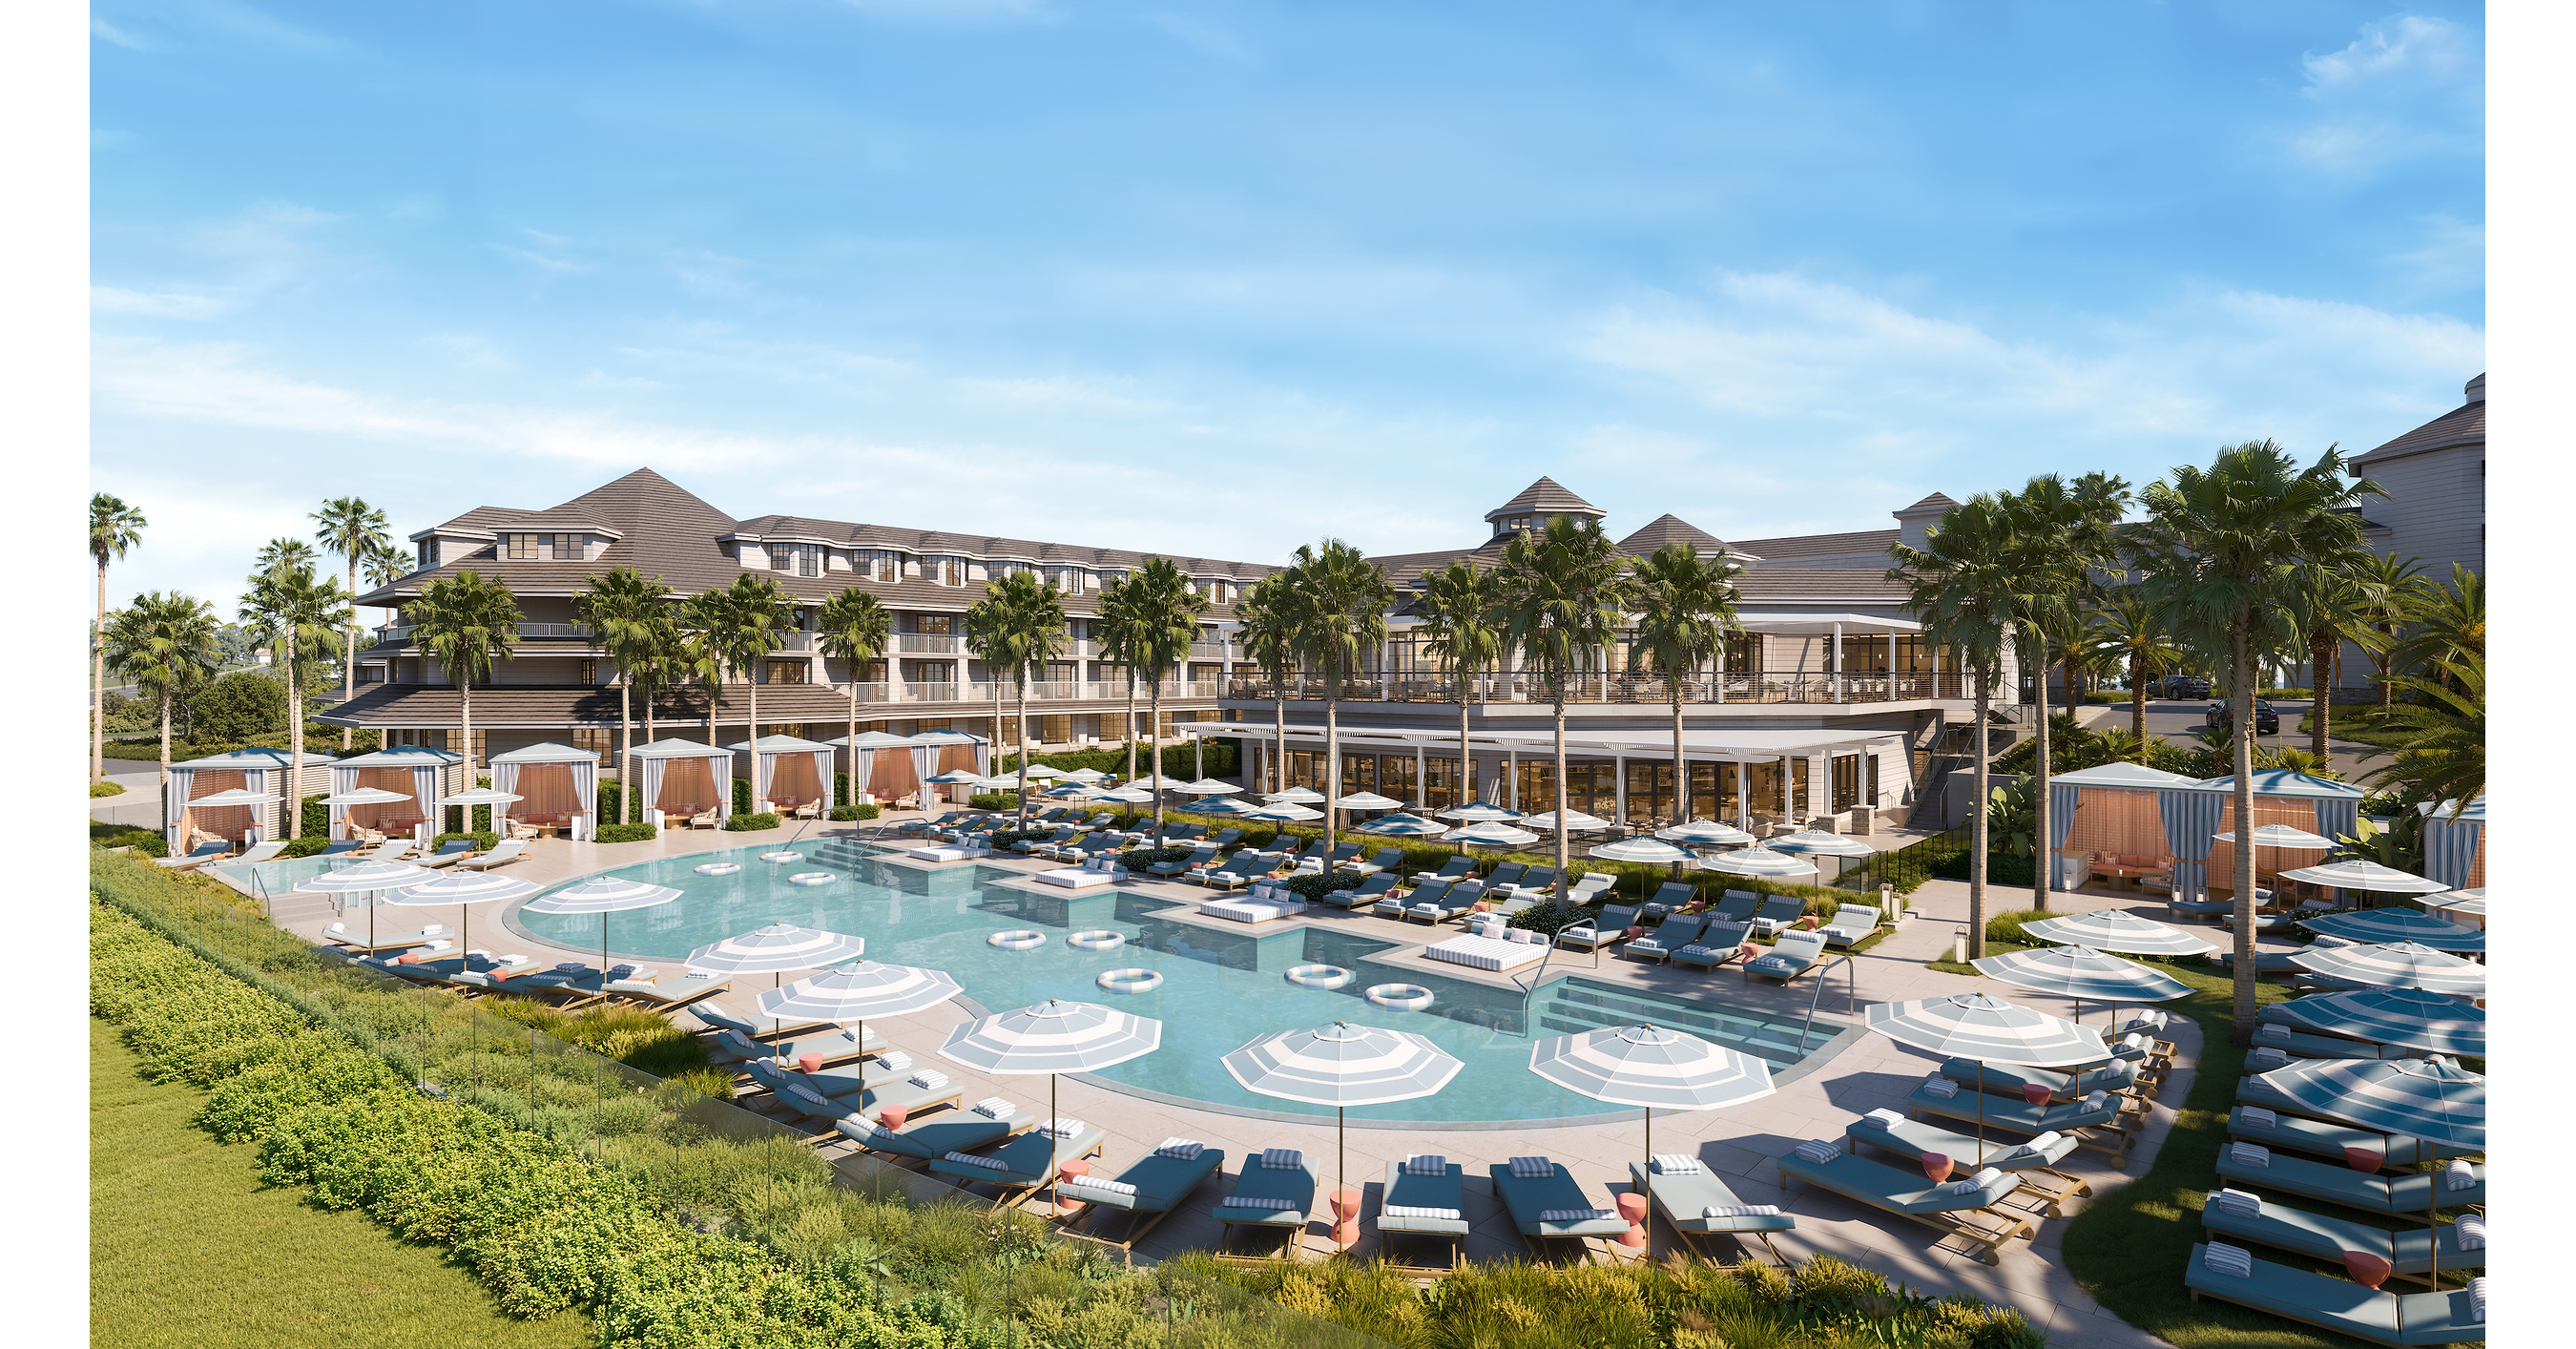
JW Marriott and Aimbridge Hospitality will reposition Laguna Cliffs Marriott Resort & Spa as The Ocean Cliffs at Dana Point, a JW Marriott Resort, through a phased comprehensive renovation. The project includes a new 6,000-square-foot ballroom, expanded multi-acre event lawn, central resort pool, signature restaurant, redesigned arrival experience, spa updates and refreshed 371 guest rooms. The upgrade is aligned with the ongoing Dana Point Harbor restoration and aims to strengthen the property's appeal for leisure, group, wedding and event travel.
Analysis
The direct earnings sensitivity for MAR is immaterial: one managed/franchised 371-room conversion will not alter systemwide RevPAR or fee guidance. The investable read is instead whether Marriott can use a higher-end flag plus Bonvoy distribution to monetize scarce Southern California coastal inventory faster than local independents and lower-tier branded competitors. A successful ramp would support the broader asset-light thesis—brand conversion and management fees can expand without MAR funding real estate—but only if the owner’s renovation spend produces a durable ADR premium rather than merely a reopening bump.
Near term, phased construction creates displacement risk and could suppress available-room revenue at the property; there is no basis to extrapolate its booking uplift to MAR’s portfolio before completion dates, renovation budget, ownership economics, and post-project rate positioning are disclosed. Over 6-18 months, group-space expansion is more consequential than refreshed rooms because meetings revenue improves shoulder-night occupancy and food-and-beverage spend, but it also raises execution risk in a market where corporate-group demand is more cyclical than leisure. Nearby luxury resorts—Hyatt’s Alila/Miraval-adjacent California offerings and Hilton’s coastal Southern California properties—face modest competitive rate pressure if the repositioning succeeds, though the local supply effect is too small to move public-company estimates.
Contrarian view: the announcement is marketing-positive but not a MAR catalyst. Investors often treat luxury-brand additions as evidence of pricing power; the relevant evidence is incremental net rooms, fee growth, and systemwide RevPAR, not a property reflag. The thesis is falsified if MAR’s next two quarterly disclosures show slowing luxury RevPAR or net-room growth, or if management flags elevated renovation disruption across comparable North American resorts.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- No standalone MAR trade on this release; maintain existing exposure only if supported by portfolio-level North America RevPAR and net-unit-growth data. Reassess after the next earnings call for luxury-segment commentary and disclosed conversion pipeline.
- Set an event-driven alert for project completion, published group-booking pace, and ADR versus Orange County luxury peers. Consider a tactical long MAR only if management identifies conversion-led fee acceleration or raises net-room-growth guidance; absent that, expected single-property impact is below materiality.
- For a broader travel view, prefer a relative-value framework rather than a directional hotel trade: long MAR versus short HLT only if Marriott’s reported international/luxury RevPAR and net rooms outperform Hilton by at least 200 bps for two consecutive quarters. Exit on convergence in RevPAR growth or a MAR guidance cut.
More News
- Budget 2026 speech
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- Google's Gemini 4 Carbon looks like a diamond in the rough
- Aker BP Q3 profit tops forecast on $870 million writedown reversal
- GE Vernova shares slip despite a beat-and-raise. What the sellers are getting wrong
- DoorDash Moves Earnings Date Forward Amid Instacart Deal Reports
From AllMind Research
- AllMind Platform Feature Updates - Fall 2026
- AI Credit Covenant Monitoring: From Clause to Review
- AI-Led Expert Interviews vs. Transcript Libraries
- Stop Treating AI Like a Chatbot: What Are Agents, SubAgents, MCP, and Skills, and How Do They Actually Work?
- Equity Research Automation Statistics: A 2026 Evidence Check