
Eightco Holdings (NASDAQ: ORBS) gibt einen Gesamtbestand im Wert von rund 380 Millionen US-Dollar bekannt, darunter Beteiligungen an OpenAI und Beast Industries sowie mehr als 16 000 ETH und fast 302 Millionen WLD-Token
Source: PR Newswire
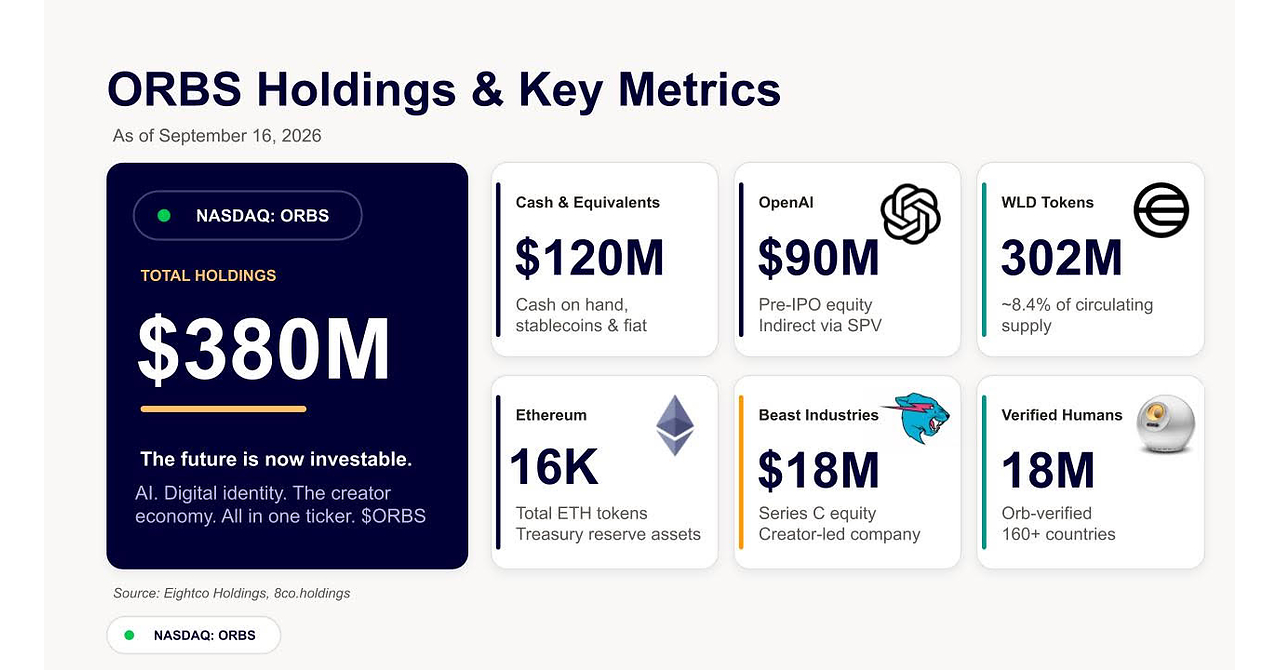
Eightco reported an approximately $380 million treasury as of September 16, including a $90 million indirect OpenAI stake, $18 million in Beast Industries, 16,278 ETH, nearly 302 million WLD tokens, and roughly $120 million in cash and stablecoins. The company repurchased more than 26 million common shares during the quarter under its previously announced $125 million buyback authorization. WLD represents about 29% of treasury assets and 8.4% of circulating supply, creating significant exposure to digital-asset price volatility alongside concentrated private-company investments.
Analysis
ORBS should trade as a closed-end, levered venture-and-token vehicle rather than as a clean AI proxy. The relevant valuation is marked liquid assets plus a steep haircut to the OpenAI SPV and Beast stake, less corporate overhead, divided by fully diluted shares—not management’s aggregate treasury figure. The disclosed components appear sensitive to valuation methodology and timing; investors need the ETH mark, token custody/lock-up status, SPV fee stack, and post-buyback diluted share count before assigning a reliable NAV premium or discount.
The WLD concentration creates a reflexive liquidity risk: a holder of this scale can be economically long a meaningful share of tradable float, but cannot necessarily monetize it without market impact or protocol/unlock-related dilution. This makes ORBS more correlated to crypto risk appetite than to enterprise-AI fundamentals over the next 1-3 months. COIN is a second-order beneficiary only if this type of corporate-token treasury model broadens retail and institutional trading activity; there is no direct read-through yet.
The buyback is constructive only if repurchases occurred below conservatively marked NAV and were funded without impairing operating liquidity. Near term, the press-release framing can drive a retail premium; over 6-18 months, realization depends on a credible liquidity event for the private stakes and demonstrated World transaction economics, not developer-program announcements. Contrarian view: the market may overvalue the OpenAI association while underpricing the probability that WLD unlocks, biometric-data regulation, or a crypto drawdown force a persistent holding-company discount.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- Do not chase ORBS on the initial disclosure. Establish a NAV-monitoring alert: consider a tactical long only if ORBS trades at a greater than 35% discount to conservatively haircutted NAV and the company discloses fully diluted shares, repurchase average price, and restrictions/custody for WLD; target discount compression to 15-20% over 1-3 months, with exit if WLD falls 25% or additional dilution is announced.
- For existing ORBS exposure, hedge the liquid beta with a partial WLD or ETH hedge sized to the marked token share of NAV; retain only the residual exposure to private assets and buyback-driven per-share NAV accretion. Rebalance weekly because token volatility will dominate reported NAV changes.
- Avoid using ORBS as a substitute for direct AI exposure. For investors seeking liquid AI beta, maintain exposure through diversified large-cap infrastructure or software baskets rather than underwriting opaque SPV marks and micro-cap liquidity risk.
- Watch SEC filings and Nasdaq compliance disclosures over the next 30-60 days. Any qualification around valuation inputs, going-concern liquidity, token restrictions, or a share-count increase falsifies the discount-compression thesis; verified repurchases materially below NAV and independently supported private-mark appreciation are the positive catalysts.
More News
- Tokenization is set to change stock trading. These stocks could get a boost
- The Dow Is Down for a Third Straight Week and the Nasdaq Is Somehow Up
- Sportsbooks remain king this football season, but upstarts are making a run for the money
- Netflix Stock Gets Downgraded by Wells Fargo on ‘Worrying' Engagement Trends
- InMed receives Nasdaq deficiency notice on equity requirement
- Par Pacific Holdings stock hits all-time high at 87.07 USD
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Software for Buy-Side Teams: Build the Research Stack
- Augmented Intelligence: AllMind, Elevate Human Judgement With an Accessible, Powerful, Data-Driven Financial AI Toolkit