
Alaska Airlines Strengthens Hawai'i Network With 737 Expansion
Source: zacks.com
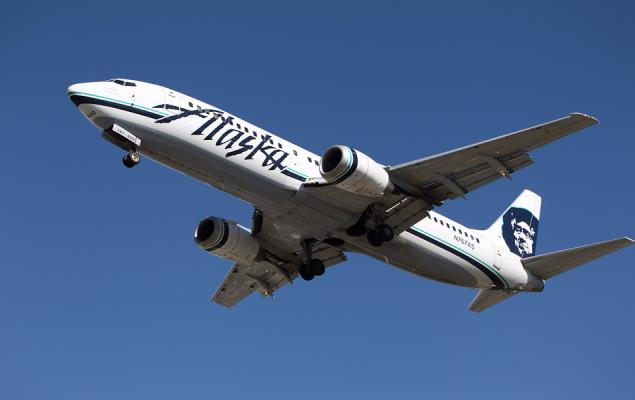
Alaska Airlines will add three daily Honolulu-Kahului round trips using Boeing 737-800s beginning Oct. 3, 2026, increasing inter-island passenger and cargo capacity. The aircraft will add premium seating, in-seat power and available Starlink Wi-Fi, while Hawaiian Airlines plans to retire its 717 fleet by 2028 in favor of Hawaiian-branded 737s. The fleet transition is intended to improve operating efficiency and customer experience, though travelers will face a longer checked-bag cutoff of 50 minutes versus 30 minutes previously.
Analysis
This is not a near-term earnings catalyst: the capacity deployment begins in late 2026, while the meaningful fleet conversion runs into 2028. The investment question is whether ALK can replace high-frequency, right-sized regional capacity without diluting unit revenue or raising trip-cost complexity; larger-gauge aircraft need stronger load factors and are less forgiving during off-peak island travel periods. Premium-seat monetization may help, but the addressable yield uplift should be treated as unproven until management discloses route-level RASM, load-factor, and ancillary-revenue performance.
The more consequential second-order effect is fleet commonality. A successful transition can lower maintenance, training, spares, and scheduling costs across the combined Alaska/Hawaiian operation, creating a structural margin lever over 2028-30; Boeing benefits only marginally because these are existing 737-800 deployments rather than incremental aircraft orders. Conversely, the removal of smaller aircraft creates a service-frequency gap on thinner routes, leaving room for Southwest (LUV) to defend or selectively gain price-sensitive inter-island traffic if ALK prioritizes capacity discipline.
Consensus may overvalue the passenger-experience narrative and undervalue execution friction. Larger aircraft can improve per-seat economics but worsen absolute cash burn when demand softens, while a longer airport-processing requirement could impair convenience on short-haul, business-oriented trips. The thesis is falsified if ALK reports sustained Hawaii load-factor weakness, incremental unit-cost pressure, or guides to lower consolidated RASM despite capacity growth; a sharper-than-expected Hawaii leisure slowdown would bring that risk forward within 1-3 quarters.
No read-through exists for EXPD, SHIP, AMZN, GOOG, or NVDA from this development. The stated cargo increment is too small and geographically constrained to affect freight intermediaries or ocean carriers, and Starlink connectivity is not a material standalone revenue catalyst for any publicly traded technology name.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Ticker Sentiment
Key Decisions for Investors
- No directional trade on the announcement. Maintain ALK as a watch item until quarterly disclosures show Hawaii capacity growth, route-level load factors, and RASM versus the system; the operational benefit is too back-ended for a 1-3 month catalyst.
- For a 6-18 month airline relative-value book, consider a small long ALK / short LUV pair only after evidence that Hawaii RASM is stable while ALK capacity rises. This isolates inter-island network execution from broad fuel and travel-demand beta; exit if ALK Hawaii unit revenue trails LUV by more than 3 percentage points for two consecutive quarters.
- Do not add BA exposure on this news. Reassess only if ALK converts fleet-standardization plans into a firm incremental 737 order or long-term lease commitment; internal redeployment has negligible order-book and cash-flow impact for Boeing.
- Set an alert around ALK's next two earnings calls for Hawaii-specific CASM ex-fuel, load factor, and premium-cabin mix. A credible cost-synergy target tied to the 2028 conversion would support a longer-duration long; absent quantified targets, treat modernization claims as narrative rather than valuation support.
More News
- AMD joins the $1 trillion club as chip rally surges - our AI Strategy saw it early
- Here's who we know is going to the Trump-Xi dinner so far
- Perpetual underdog AMD nips at Nvidia's heels as it joins the $1T club
- Intel surges 12% as CPU stocks rally. Here's what's driving the move
- Muse, Meta's extraordinarily privileged AI assistant, has a serious 0-day
- Why Intel, Arm, and Other AI Chip Stocks Soared Today