
History Says Now Is the Perfect Time to Buy Nvidia Stock
Source: fool.com
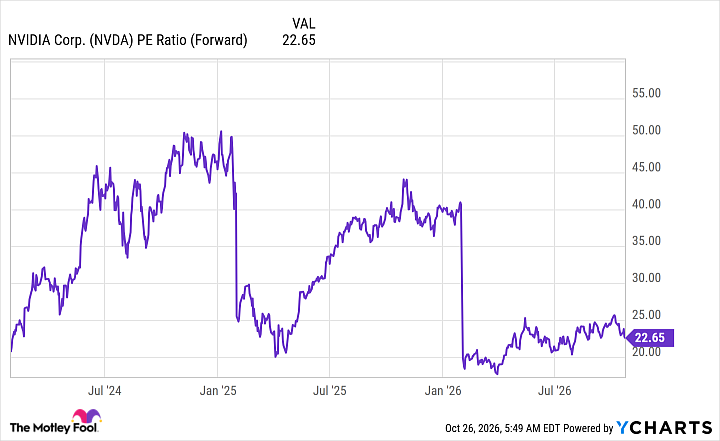
Nvidia delivered 106% revenue growth in Q2 and said it expects 70% revenue growth next year; Wall Street analysts forecast 68%. The article argues NVDA's valuation—just under 23 times forward earnings and 13.3 times next fiscal year's estimated earnings—does not reflect that outlook, and says the shares could double, while noting this is the author's view rather than a reported market consensus.
Analysis
The bullish case hinges on converting customer commitments into sustained, profitable demand—not on a low headline forward P/E. The valuation comparison is fragile: the cited 23x and 13.3x use different earnings horizons, and revenue growth guidance does not establish equivalent earnings growth. The claim that a doubled stock would trade at 26x “trailing” earnings is not supported by the forward multiples presented. Verify the estimate period, earnings denominator, and subsequent revisions before treating this as cheap.
Near term, positioning and the next earnings update can dominate the multiple: any evidence that customers are slowing or extending AI infrastructure payback periods could compress estimates before the long-term build-out thesis changes. Over 1–3 months, watch hyperscaler capex commentary, order visibility, data-center revenue, and gross-margin direction. Over 6–18 months, custom accelerators and improving utilization could shift spending away from Nvidia GPUs or constrain customers’ willingness to keep expanding capacity. Conversely, durable orders with stable profitability would make today’s market skepticism look misplaced. The article offers no independent validation of locked-in orders or the durability of 70% growth; treat those as claims to test, not certainty.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Ticker Sentiment
Key Decisions for Investors
- Consider a starter long in NVDA rather than an aggressive all-at-once position; add only if the next results and customer commentary corroborate demand visibility and earnings conversion. The thesis is falsified by meaningful guidance or estimate cuts, weakening data-center growth, or deteriorating margins.
- For a more catalyst-focused expression, consider long NVDA / short a broad Nasdaq exposure such as QQQ, sized modestly. This reduces some market beta but leaves substantial AI and valuation risk; reassess after earnings and hyperscaler capex updates.
- Do not anchor on the article’s 13.3x figure or assume revenue growth translates one-for-one into earnings. Confirm the fiscal-year period, consensus EPS revisions, and share-count assumptions before increasing exposure.
- Contrarian risk: the market may be discounting customer concentration, capex returns, and substitution by custom silicon rather than simply overlooking growth. If those risks worsen, historical year-end valuation patterns are not a reliable catalyst.
More News
- TechCrunch Mobility: A new, bigger AV boom is here
- Unicaja Q3 2026 slides show 8% profit gain, 95% payout ratio
- Nvidia: SpaceX Offers An Ignored Bonus
- If I Could Only Buy and Hold 1 "Magnificent Seven" Stock Through 2030, It Would Be This One
- Nvidia Q3 FY2027 Preview: The Fabless Model Just Got A $279 Billion Footnote
- Lumentum Earnings Preview: The AI Boom Is Already Priced In