
SUBARU OF AMERICA REPORTS AUGUST 2026 SALES INCREASE
Source: PR Newswire
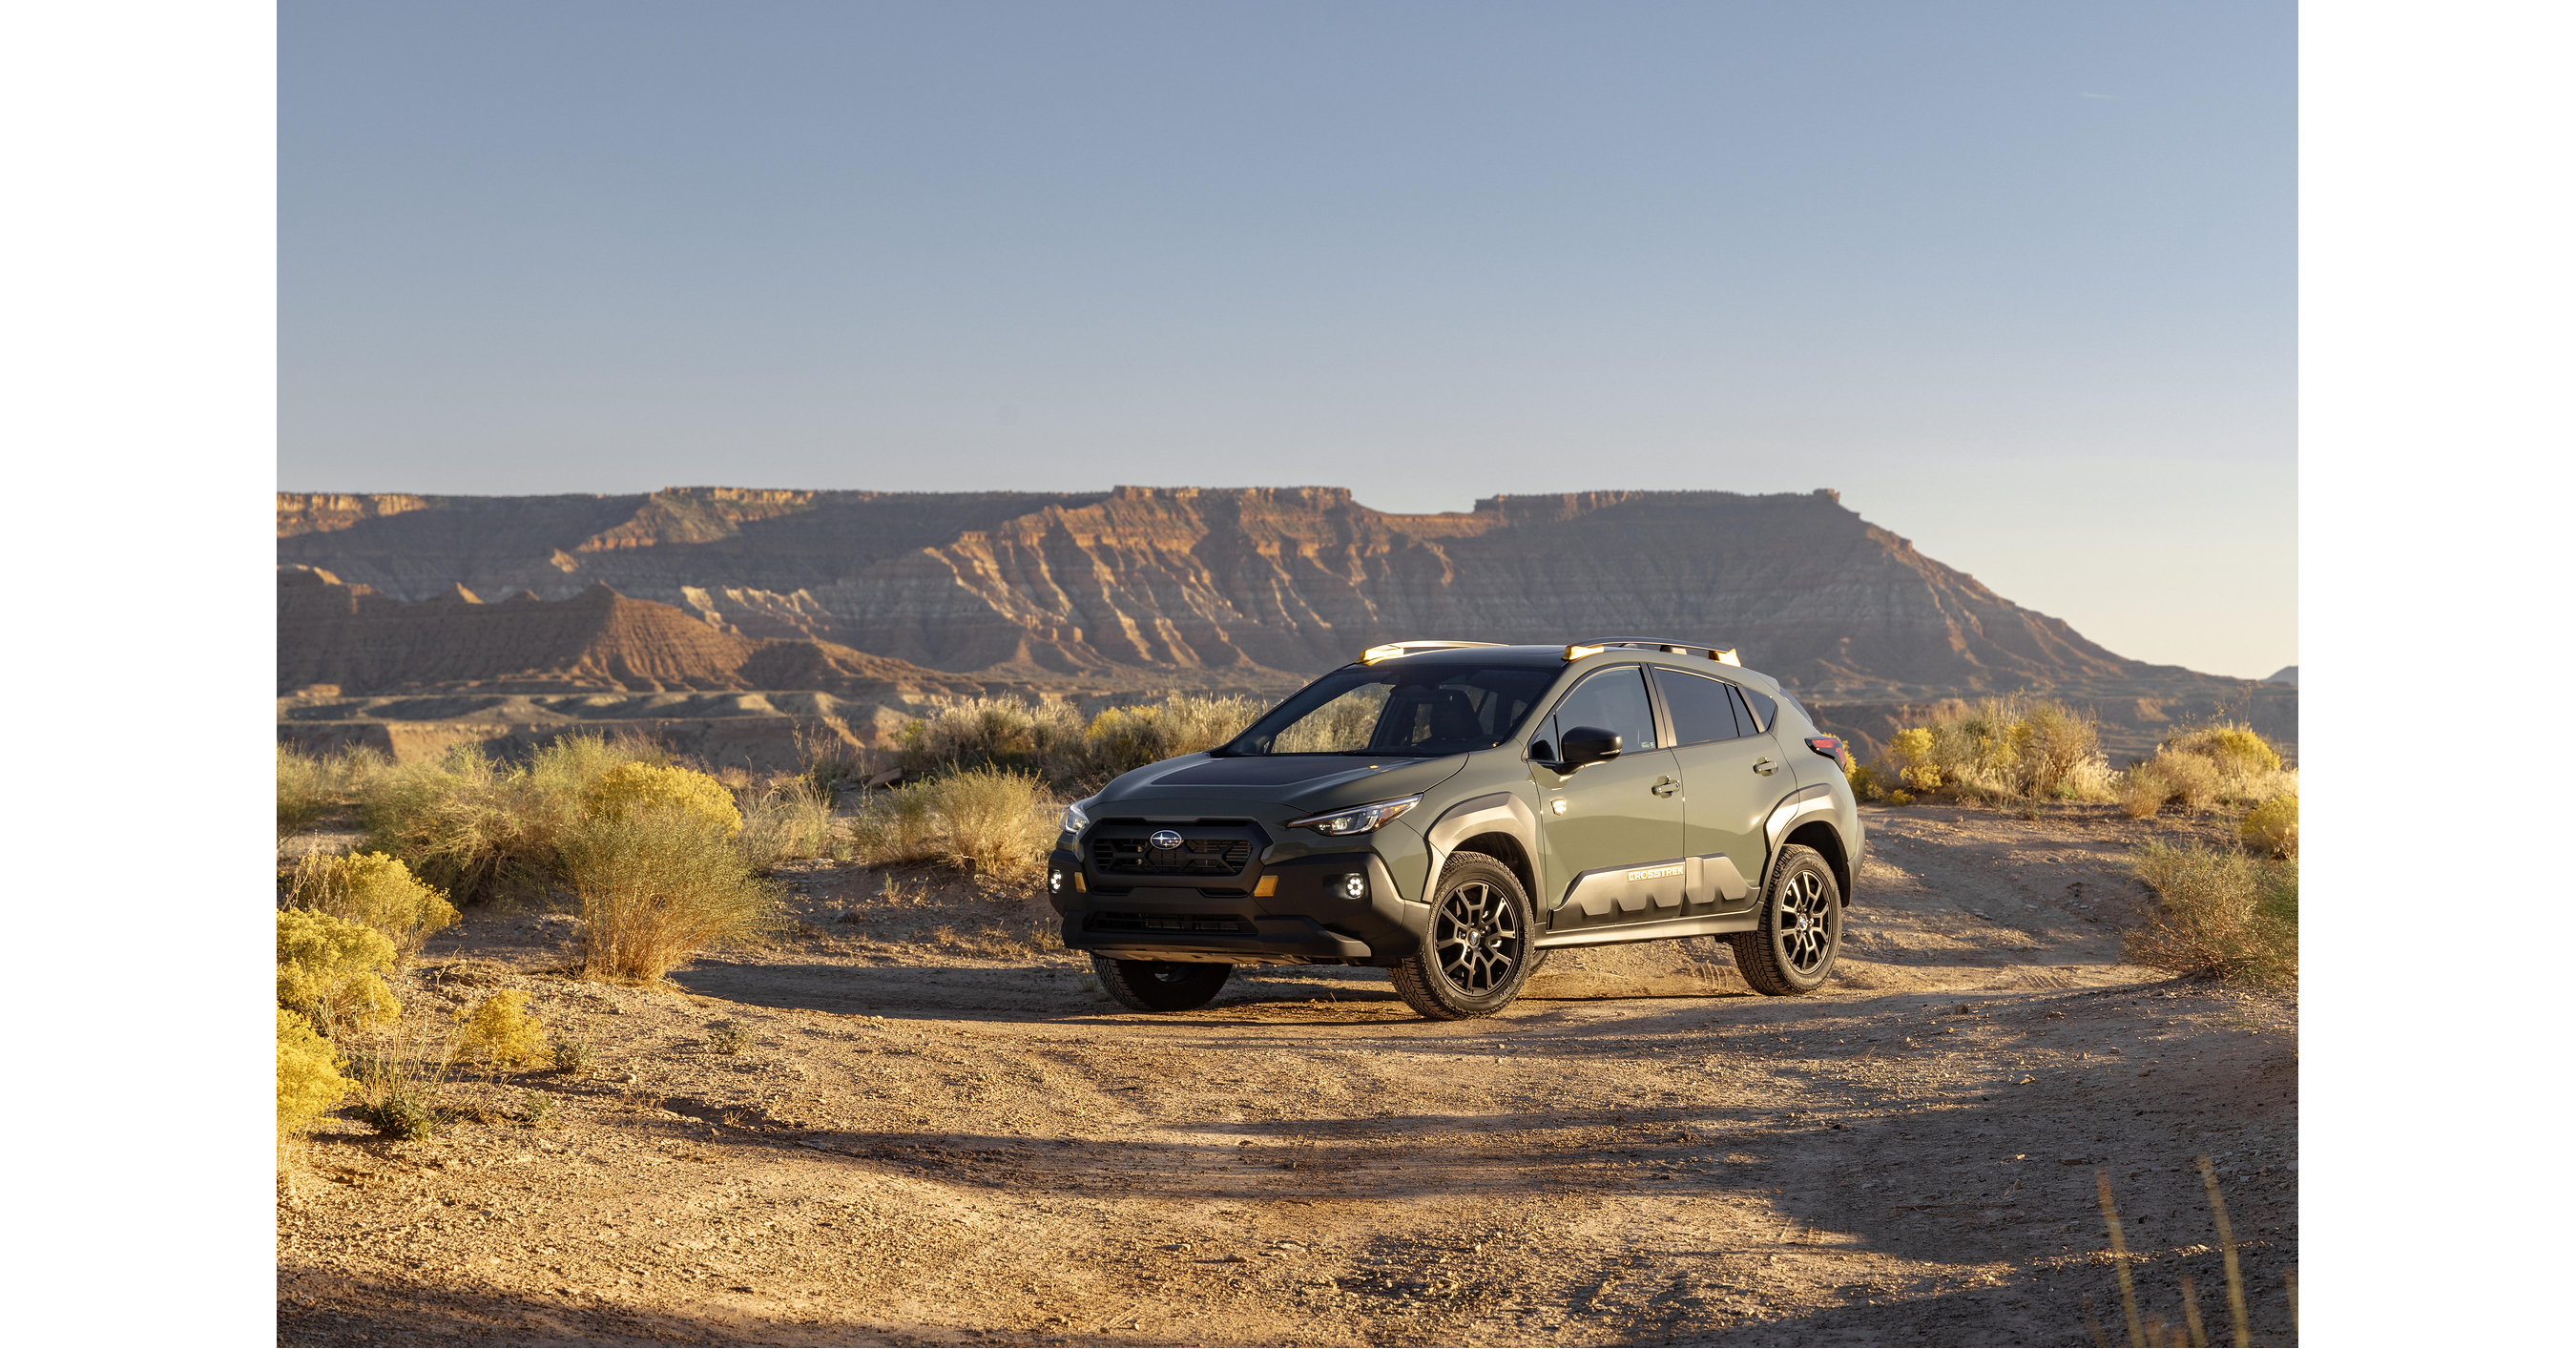
Subaru of America reported 62,028 vehicle sales in August 2026, up 1.3% YoY. Crosstrek led with 19,541 units, while Forester rose 17.8% YoY and was up 15.1% YTD; WRX was up 37.7% YTD, with Ascent and Outback also posting their best months of the year so far. Overall YTD volume declined 3% to 423,822, suggesting momentum is improving in select nameplates rather than broad demand.
Analysis
The important signal is mix quality, not the modest unit growth. Subaru is still leaning on crossover-heavy demand, which tends to protect gross margin better than discount-driven volume because it reduces rebate pressure and improves dealer profitability. If that mix holds into Q3, the market should view this as a margin stabilization story for FUJHY rather than a true demand acceleration story, so any rerating should be limited unless inventory tightens further.
Second-order, this is more of a competitive-pressure print for Honda and Toyota in U.S. compact/mid-size crossover segments than a broad win for the industry. If Subaru is defending share without heavier incentives, peers may need to lean harder on lease support to hold traffic, which would hit North American operating margins over the next 1-3 months. The weak EV contribution remains the larger structural issue: the company still looks exposed to rising compliance and product-gap risk over 6-18 months if electrified volume does not scale.
Contrarian view: the market may be overcalling this as a demand inflection when it could just be inventory normalization and model-cycle timing. The brand halo from enthusiast trims is useful, but financially secondary; the real falsifier is whether September and October retail data hold up without a step-up in incentive spend. If incentives rise or the crossover mix softens, this move should be faded quickly.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Small tactical long FUJHY on weakness, 1-2 month horizon; thesis is better mix supports Q3 margins more than headline volume suggests. Stop out if U.S. retail data or incentive spend deteriorates in September.
- Relative-value idea: long FUJHY / short HMC into the next 1-3 months if Subaru maintains crossover share and Honda has to defend with higher lease support. Better risk/reward than an outright auto-beta bet.
- Do not chase the move with options; this print is too noisy for a clean earnings-vol trade. Wait for Q3 sales and incentive data before paying up for convexity.
- Set an alert on Subaru U.S. incentive trends and Solterra share. If EV mix remains weak into Q4, trim any long exposure and treat the stock as a value trap rather than a growth story.
- No actionable read-through for GOOGL; the link to auto demand is too indirect to justify positioning.
More News
- AI Capex, Gamble or Jackpot?: Market Snapshot
- ‘I told you so’: China’s chip sector is making breakthroughs—and U.S. export controls are the reasons why
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- Hybe shares jump 10% as K-pop sensation BTS' tour lifts earnings hopes
- Giant Taiwanese chipmaker TSMC confirms it’s in talks with Elon Musk to join ‘Terafab’ complex in Texas: ‘The AI market continues to be very strong’