
Brookdale CEO Nick Stengle Receives Champion for Aging Award
Source: PR Newswire
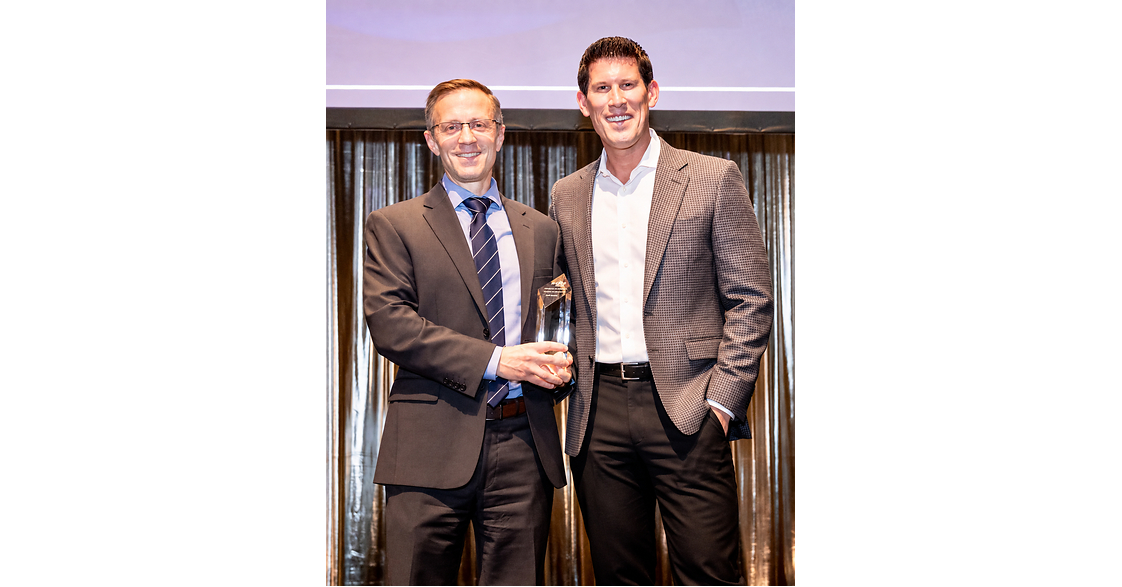
Brookdale Senior Living CEO Nick Stengle received the Connected Health & Safety Association's 2026 Champion for Aging Award, recognizing leadership in resident care, wellness and senior-living innovation. The company operates 532 communities in 41 states and can serve approximately 45,000 residents as of August 31, 2026. The recognition is reputationally positive but provides no new financial results, operating guidance or material strategic transaction.
Analysis
This is not a fundamental catalyst: the recognition has no independently verifiable implication for occupancy, rate growth, labor utilization, or leverage. BKD should not sustain a rerating on it absent evidence that its care/technology initiatives improve conversion, resident retention, or staffing costs relative to peers such as Atria (private), Sonida Senior Living (SNDA), and Welltower’s (WELL) operating portfolio.
The relevant second-order issue is whether a quality-and-technology narrative can translate into lower agency-labor dependence and higher acuity mix. Even modest operating leverage matters in senior housing: sustained occupancy gains combined with annualized resident-rate increases above wage inflation would disproportionately lift community-level margins over the next 6-18 months, while weak service metrics would instead force discounting and elevate turnover costs. The press release provides no KPIs to underwrite either outcome.
Near term, treat any sympathy bid as liquidity rather than information. The actionable catalyst path is BKD’s next earnings release: admissions/occupancy trends, RevPOR versus labor inflation, agency staffing, and net leverage are the variables that can justify a multiple change. A broader senior-housing recovery would likely benefit well-capitalized REIT landlords such as WELL and Ventas (VTR) more cleanly than BKD if operators remain constrained by labor and balance-sheet costs.
Contrarian view: the market may over-credit brand and quality accolades while underweighting execution risk in a labor-intensive, price-sensitive model. Conversely, if BKD demonstrates that health-tech investment measurably reduces turnover or raises occupancy without incremental capex, the equity could rerate sharply because the operating model has high fixed-cost absorption; until disclosed, that is an alert rather than a thesis.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.22
Ticker Sentiment
Key Decisions for Investors
- No new directional BKD position on this release; reassess only at the next earnings print when same-community occupancy, RevPOR, labor expense per occupied unit, and net leverage are disclosed.
- For a 6-12 month senior-housing recovery allocation, prefer long WELL or VTR over BKD: landlord balance sheets offer cleaner exposure to improving occupancy and rental rates, with less direct labor-execution risk.
- Set a BKD watch trigger: initiate a tactical long only if occupancy and RevPOR accelerate while labor inflation decelerates for two consecutive quarters; invalidate if guidance implies margin compression or leverage rises.
- If BKD rallies materially before earnings without corroborating operating KPIs, consider a small relative-value short BKD versus long WELL, sized as an event-driven trade; cover on evidence of sustained margin expansion or a positive guidance revision.
More News
- Ryanair CEO warns fares could rise by up to 20% in 2027 as fuel bill jumps by $2.2 billion
- Amgen (AMGN) Bets on MariTide to Crack $120 Billion Obesity Market
- Wells Fargo raises Abbvie stock price target to $340 on pipeline
- Wells Fargo raises Regeneron stock price target to $925 on execution
- The ‘haunted’ housing market’s real problem may be too few people, not too few homes, says J.P. Morgan’s David Kelly
- Evercore ISI reiterates Duolingo stock rating on user growth