
Midea hace realidad su concepto "Simplemente ideal" en IFA 2026
Source: PR Newswire
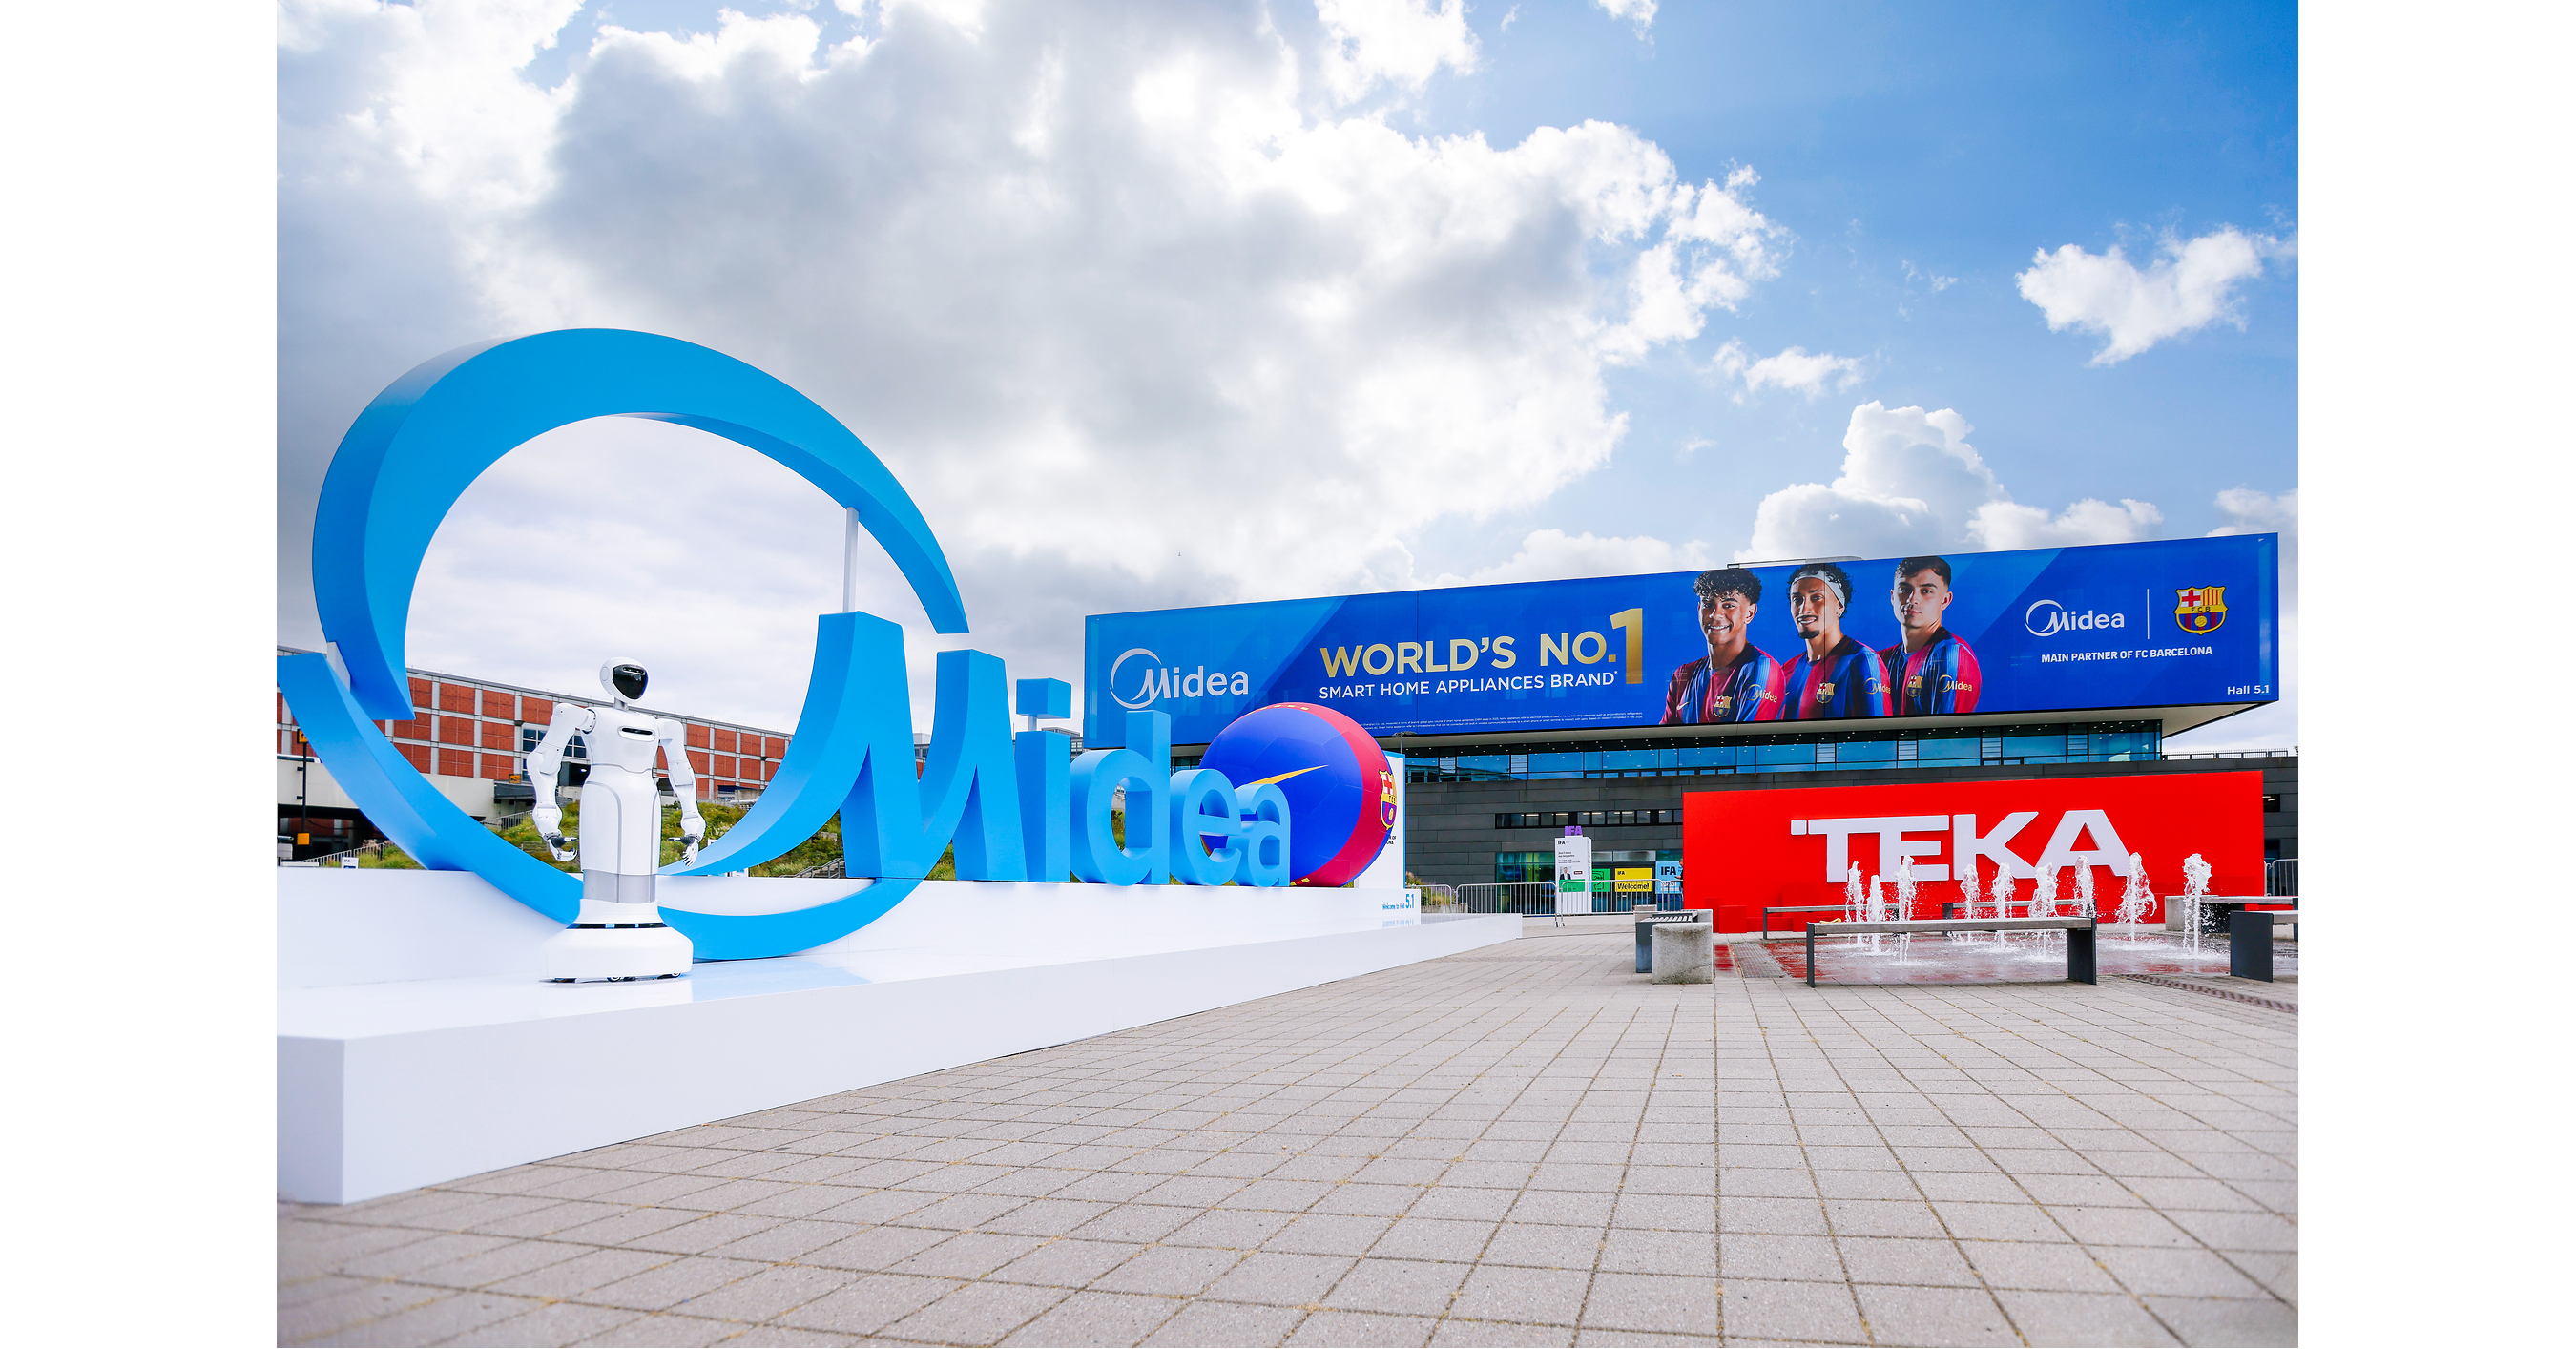
Midea unveiled its "Simplemente ideal" smart-home portfolio at IFA 2026, led by the AI-powered SMART MASTER ecosystem, AI Agent and home robot concepts. Its R290 cooling range claims 10% higher energy efficiency, while the Tri-GreenApex dishwashing system uses roughly 50% less energy than Europe’s top A energy-rating requirement. The company also highlighted a new five-year FC Barcelona partnership and expanded connected-appliance interoperability through Matter.
Analysis
The investable issue is whether Midea can convert feature breadth into higher European mix and lower channel discounting, not whether the products are technically differentiated. In white goods, connected features typically support ASP only when bundled with energy savings, installation simplicity, and retailer service; otherwise they raise software/support costs faster than gross margin. For Midea Group (000333 SZ), the near-term read-through is modest until European sell-through, not showroom placement, demonstrates that premiumization is offsetting promotional intensity.
The more consequential 6-18 month angle is refrigerant transition. R290 adoption can create a compliance and engineering moat versus lower-cost exporters, but it also increases certification, installer-training, and product-liability exposure; a delayed regulatory rollout or safety incident would erase the efficiency-led differentiation. Daikin (6367 JP), Carrier (CARR), Trane (TT), and Johnson Controls (JCI) have greater HVAC profit sensitivity than Midea, while Haier Smart Home (600690 CH) and Hisense Home Appliances (000921 CH) are the closest China-export competitive benchmarks.
Consensus may overvalue the AI label and undervalue European distribution economics. Interoperability reduces consumer friction but also weakens proprietary ecosystem lock-in, making hardware reliability, energy performance, and retailer shelf access the durable differentiators. The Barcelona sponsorship is principally a marketing-cost and brand-awareness variable; absent measurable regional share gains, it should not justify a multiple re-rating.
There is no high-conviction event trade from this release. The relevant 1-3 month catalysts are third-party European retail data, management disclosure on smart-appliance attach rates and warranty costs, and competitor pricing through the autumn promotional cycle. A bullish thesis is falsified if European revenue growth lags local appliance demand, gross margin contracts despite mix improvement, or inventory days rise; a bearish thesis is falsified by sustained share gains without incremental promotional spend.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No immediate position based solely on the product announcement; set an alert on 000333 SZ for the next earnings release to isolate Europe revenue growth, smart-product ASP uplift, warranty provisions, and channel inventory. Upgrade only if margin expansion accompanies share gains.
- Monitor a relative-value basket: long 000333 SZ or 600690 CH versus short ELUX-B SS after the next European appliance-demand data, only if Chinese exporters show sell-through-led share gains while Electrolux remains promotion-dependent. Target a 8-12% relative move over 6-12 months; exit if European demand contracts materially or Chinese brands increase rebate spend.
- For HVAC exposure, prefer an R290-transition watchlist rather than a directional trade: CARR, TT, JCI, and 6367 JP. Reassess after regulatory certification milestones and 2027 product rollouts; the key downside trigger is delayed approvals, installer constraints, or evidence that safety-related costs absorb efficiency-driven pricing.
- Treat any Midea brand multiple expansion as unearned until independently verifiable European retail-share data emerges. If 000333 SZ materially outperforms the appliance peer group before those data, consider trimming rather than chasing, as marketing-driven sentiment is unlikely to be the earnings catalyst.
More News
- Are global oil reserves sufficient to withstand renewed US-Iran war?
- OpenAI Trims Target Value & Volvo Cars Cuts 2,500 Jobs
- PG&E’s CEO says AI is ‘the best thing that could’ve ever happened to the grid’
- The mobile ambitions of SpaceX see telecom stocks get hit again. What the latest developments mean.
- Wake up! The long bond’s up two points!
- US tech stocks tumble as investors fret over AI spending