
Loar Holdings Inc. Reports Q3 2026 Record Results and Upward Revision to 2026 Outlook and Full Year 2027 Outlook
Source: Newswire
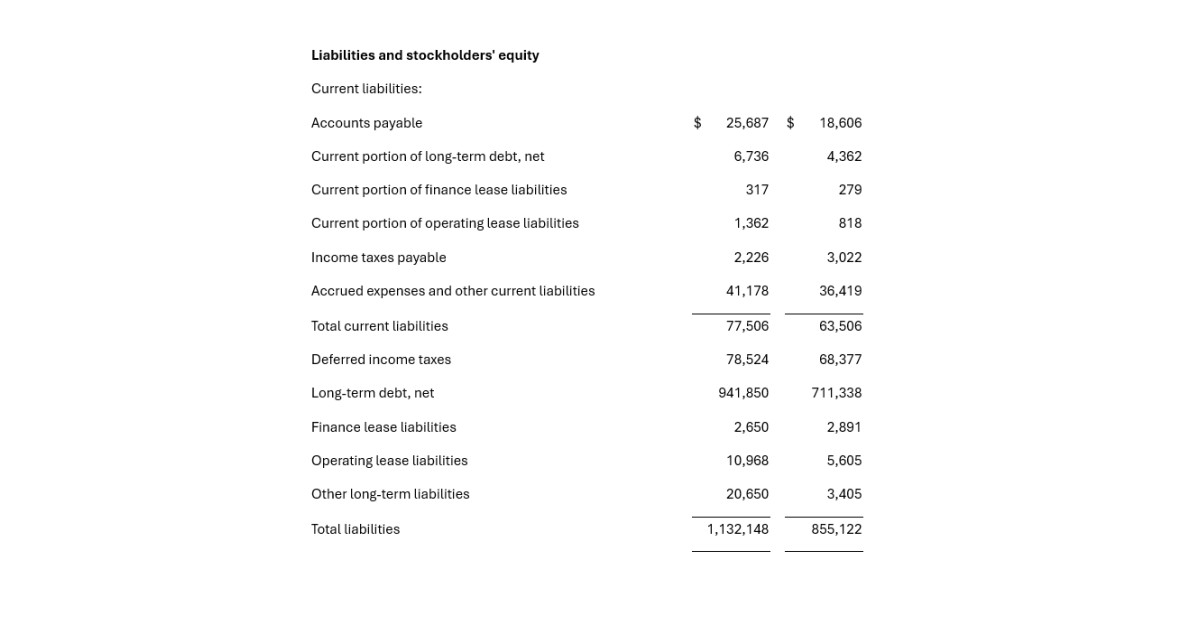
Loar reported Q3 2026 sales of $176.2 million, up 39.0%, and Adjusted EBITDA of $71.9 million, up 46.5%; Adjusted EBITDA margin expanded to 40.8% from 38.7%. GAAP net income fell to $19.6 million from $27.6 million, with diluted EPS down to $0.20 from $0.29, amid higher interest, tax and acquired-intangible amortization expenses. The company raised 2026 sales guidance to $669–$679 million and Adjusted EBITDA to $270–$275 million, and forecast 2027 sales of $745–$755 million and Adjusted EBITDA of $312–$317 million.
Analysis
The key signal is the gap between operating momentum and GAAP earnings: EBITDA growth and margin expansion are strong, but reported net income and EPS are down year over year as interest, taxes and acquired-intangible amortization absorb more of the operating improvement. That makes the 2027 step-up in net income/EPS the real underwriting test—not simply continued sales growth. With debt materially higher after acquisitions, execution must translate into durable cash generation and deleveraging; adjusted EBITDA excludes interest and several recurring costs, so it is not a substitute for cash available to shareholders.
Near term, the third 2026 outlook increase and first 2027 outlook give bulls a credible backlog-conversion narrative, but the 2027 earnings ramp is much steeper than the roughly low-double-digit sales outlook. Investors should verify the bridge in the call: organic growth versus acquired contribution, interest/tax assumptions, and whether working capital is limiting cash conversion. The stated record operating cash flow after capex is encouraging, but nine-month cash flow still includes acquisition spending and does not establish normalized post-deal conversion.
Over 1–3 months, backlog conversion and guidance credibility drive revisions; over 6–18 months, commercial aftermarket demand and OEM production rates support the niche-component supplier group, while production delays or airline capacity changes could defer shipments. The contrarian risk is that headline adjusted growth masks acquisition dependence, financing costs and substantial amortization. No valuation or market expectations are provided, so the release alone does not establish attractive entry pricing.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Ticker Sentiment
Key Decisions for Investors
- No chase at the open without price/valuation context. Treat LOAR as a conditional long on weakness only if the call confirms organic demand, backlog shipment timing and the 2027 net-income bridge; compare relative performance with aerospace suppliers such as TransDigm and Howmet rather than assuming the whole sector shares Loar’s mix.
- Use the conference call and next results as a 1–3 month catalyst check: track organic sales, order/backlog conversion, operating cash flow less capex, and net debt. A miss in cash conversion despite EBITDA growth would weaken the long thesis.
- Risk marker: debt and interest costs are rising alongside acquisition-led growth. Reassess if management lowers 2027 sales or earnings outlook, if organic growth decelerates materially, or if net debt fails to trend down as acquired businesses are integrated.
- Potential upside is operating leverage if the projected margin expansion and earnings ramp arrive without another acquisition; potential downside is multiple compression if investors discount adjusted metrics and the GAAP/cash earnings gap persists. Verify the full-year tax, interest and acquisition-related assumptions before sizing.
More News
- Tech stocks are suffering their biggest selloff since Covid, as investors see premature end to AI datacenter boom
- Elon Musk's Tesla and SpaceX lose over $420 billion in combined market cap after midterms
- Iran says tankers struck in Hormuz amid fears of new US attack
- The Iran war has cost U.S. households nearly $2,000 each. New strikes could keep the bill climbing
- Shield AI To Hit $28.8 Billion Value With $5.3 Billion Radar Acquisition
- We're raising our price target on Cardinal Health after another stellar quarter of profits