
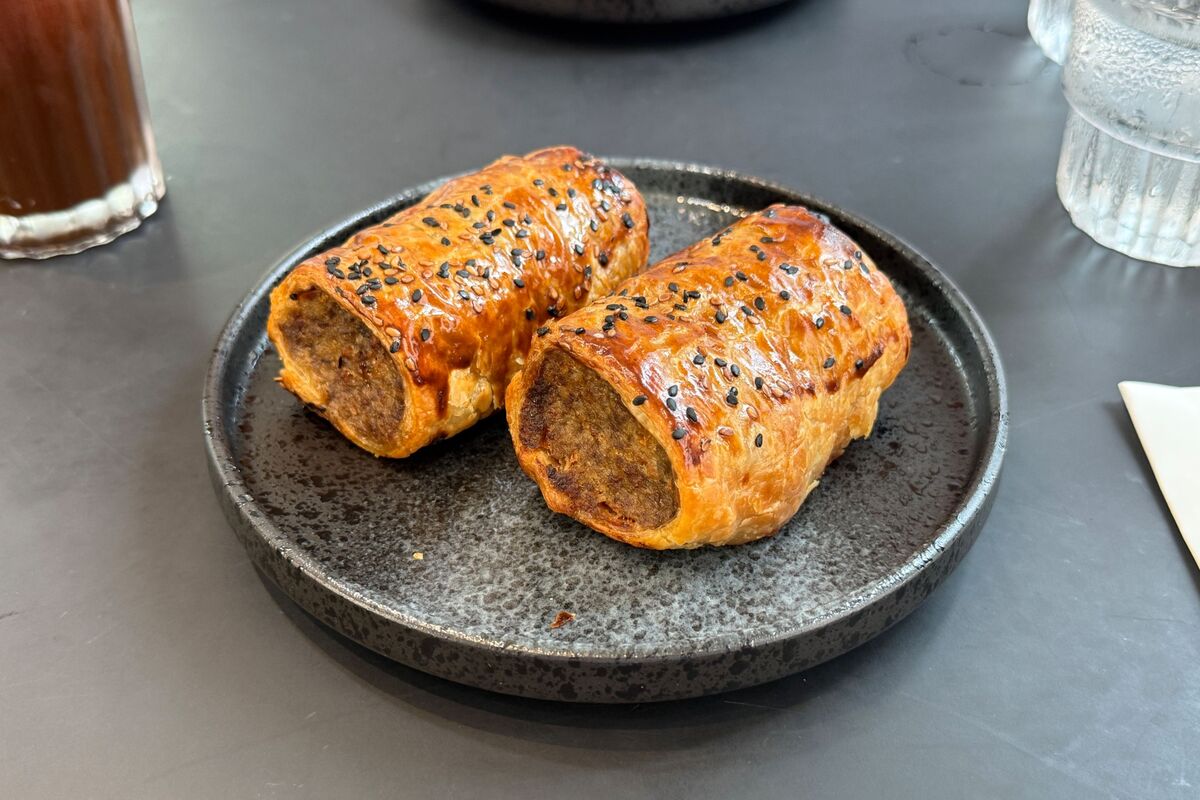
Hong Kong steak chain Flat Iron launched a new bakery focused on sausage rolls, but the debut is described as “bumbles”/“falls flat.” The article suggests the foray into a new pastry category is unexpected given the chain’s established strength in affordable casual steak dining and a pared-down menu.
Analysis
This reads more like a brand-extension test than a material earnings event. In casual dining, the first-order upside from a new category is usually small; the real variable is whether management is stretching a simple operating model into something harder to execute, which can show up later as lower kitchen throughput, more waste, and less consistent customer experience. For CBNA/TSTS, the investable question is not demand for a pastry item; it is whether the concept change quietly raises labor intensity enough to pressure unit economics over the next 1-2 quarters.
The second-order risk is competitive, not category-sized. If the trial works, the incremental winners are landlords and ingredient suppliers from more daypart traffic, but if it fails, adjacent bakery specialists likely absorb only trivial share because consumers in Hong Kong tend to reward convenience and consistency more than novelty. The more important loser could be the core steak brand itself if management attention shifts toward menu experimentation and dilutes the value proposition that originally drove traffic.
Consensus may be overrating "innovation" here. In restaurant stocks, the market usually wants either clear frequency expansion or clear margin discipline; concept creep without disclosure on payback is usually a warning sign, not a catalyst. The thesis would be falsified if CBNA/TSTS can show 2 consecutive quarters of higher transaction frequency or basket size with no margin dilution; absent that, this is best treated as a watch item rather than a tradable signal.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.25
Key Decisions for Investors
- No immediate position in CBNA or TSTS on this news; wait 1-2 quarters for evidence on traffic, mix, and restaurant-level margin before expressing a view.
- Set a watch alert on CBNA/TSTS for any disclosure of labor-cost inflation or food-waste creep; if gross margin slips by >100 bps while sales contribution from the bakery remains de minimis, consider a 3-6 month short/underweight.
- If future reporting shows the new category drives >2% incremental same-store sales without margin dilution, cover any bearish stance and reassess for a 6-12 month long case on brand extension.
More News
- Copper is outshining gold this year. Investors say the rally can survive an AI correction
- 'Cannot play hide and seek': Singapore minister's warning over haze sends agricultural stocks lower
- BlackRock, GIC among investors chasing Indian telecom major Jio's IPO as anchor bids top $26 billion
- Nscale, Anthropic Eye $45 Billion Cloud Deal as AI Trade Rebounds
- Volkswagen bet on Xpeng to save its China business. It’s not going to plan
- Gartner analyst behind tech rout: AI returns are not yet large enough to justify neocloud build-out