
ROSEWOOD HONG KONG NOMBRADO NO.1 EN LA LISTA THE 50 BEST HOTELS 2026 POR SEGUNDO AÑO CONSECUTIVO
Source: PR Newswire
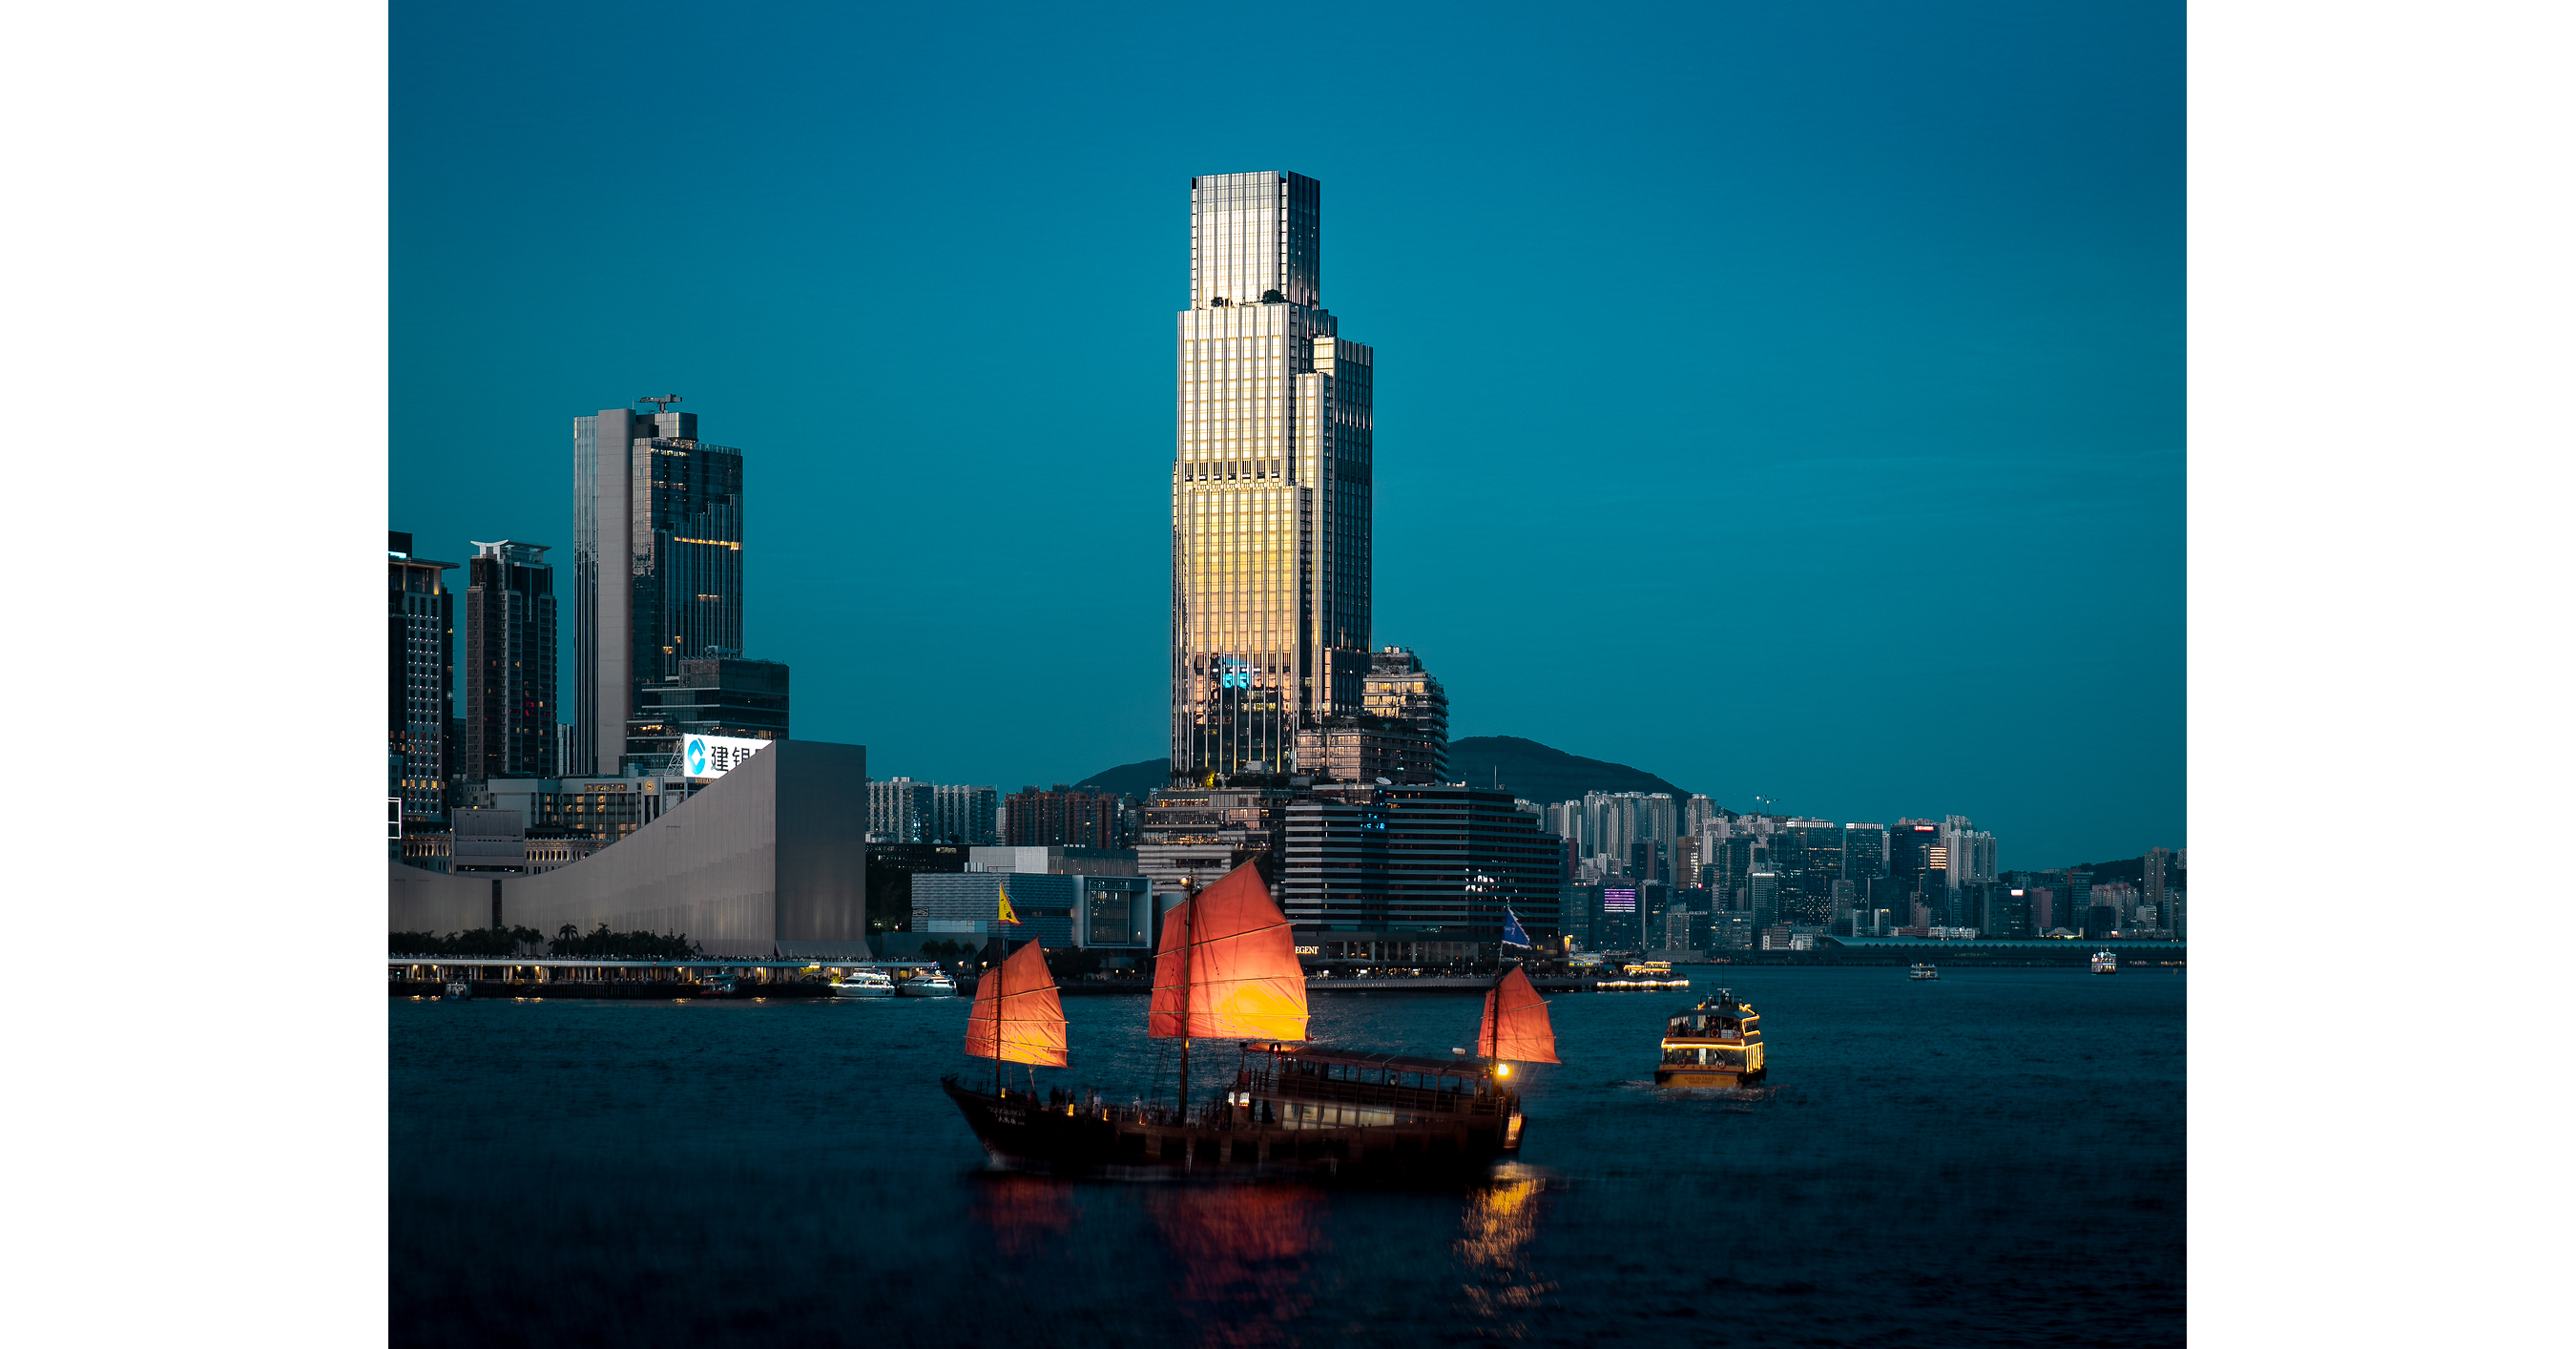
Rosewood Hong Kong was named The World's Best Hotel 2026 for the second consecutive year, retaining its No. 1 ranking after placing third in 2024. The 50 Best Hotels list recognized properties across 22 destinations and six continents, led by Europe with 21 hotels and Asia with 18. Rosewood also received the Ferrari Trento Most Admired Hotel Group Award, while Chablé Yucatán won the Bombay Sapphire Eco Hotel Award.
Analysis
This is primarily brand-equity validation rather than an earnings catalyst. For Rosewood owner AIA Group (1299 HK) and private hospitality operators, repeated third-party recognition can support premium ADR and luxury-segment mix, but the effect is too diffuse to alter near-term public-market estimates. Hyatt (H) has no direct read-through; the more relevant listed proxy is Marriott (MAR), whose luxury portfolio competes for the same high-spend international traveler, but any share shift would be immaterial absent booking and RevPAR evidence.
AXP has a modest second-order benefit through its premium travel ecosystem: award-recognized properties strengthen the perceived exclusivity of Fine Hotels + Resorts and can reinforce retention/spend among high-fee cardholders. The mechanism is qualitative and long duration, however, not a reason to change estimates before quarterly billed-business and card-member retention data. RACE's association is marketing exposure only; it does not create a measurable volume or margin pathway.
The contrarian view is that luxury-hotel accolades can be a lagging indicator of a cycle already benefiting from constrained trophy-property supply. If global premium leisure demand softens or China outbound travel fails to accelerate, operators may preserve occupancy only through higher distribution costs or promotional packages, limiting the ADR-to-EBITDA conversion investors expect. Over the next 1-3 months, watch Asia luxury RevPAR, cross-border air capacity, and AXP travel-and-entertainment spending; over 6-18 months, new luxury supply in Bangkok, Dubai, Japan, and Italy is the more material competitive variable.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on this release: impact is reputational, with no disclosed booking, pricing, or financial data sufficient to underwrite an earnings revision.
- Maintain AXP as the cleanest liquid watch proxy; add only if upcoming quarterly results show resilient T&E spend and premium-card retention alongside stable credit losses. Thesis is invalidated by a material deceleration in billed business or rising rewards expense that offsets premium-fee economics.
- Do not infer a positive read-through for H from the awards. Use luxury RevPAR and group guidance as the trigger; a sustained luxury RevPAR miss versus MAR/Hilton (HLT) would favor short H versus long MAR only if valuation dispersion remains favorable.
- Treat RACE exposure as non-investable marketing noise. Reassess only if luxury hospitality partnerships translate into disclosed client acquisition, event-driven orders, or regional demand data.
More News
- Karin Rådström is steering Daimler Truck in a new direction as the world’s biggest truckmaker faces a growing challenge from China
- France would back Dutch veteran Knot to lead ECB, wants chief economist job, sources say
- Trip.com swings to Q2 loss after $763 million antitrust penalty
- Saudi-led coalition intercepts drone headed for Mecca
- US data centers could consume more natural gas than Germany and Japan combined by 2035
- Agility is the most important skill in the AI age, says Capgemini CEO
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI for Sell-Side Models, Estimates, and Internal Data
- How to Write an Investment Memo with AI: A Decision-Record Template