
Norfolk Southern and Schneider partner to expand domestic intermodal capacity across the eastern U.S.
Source: PR Newswire
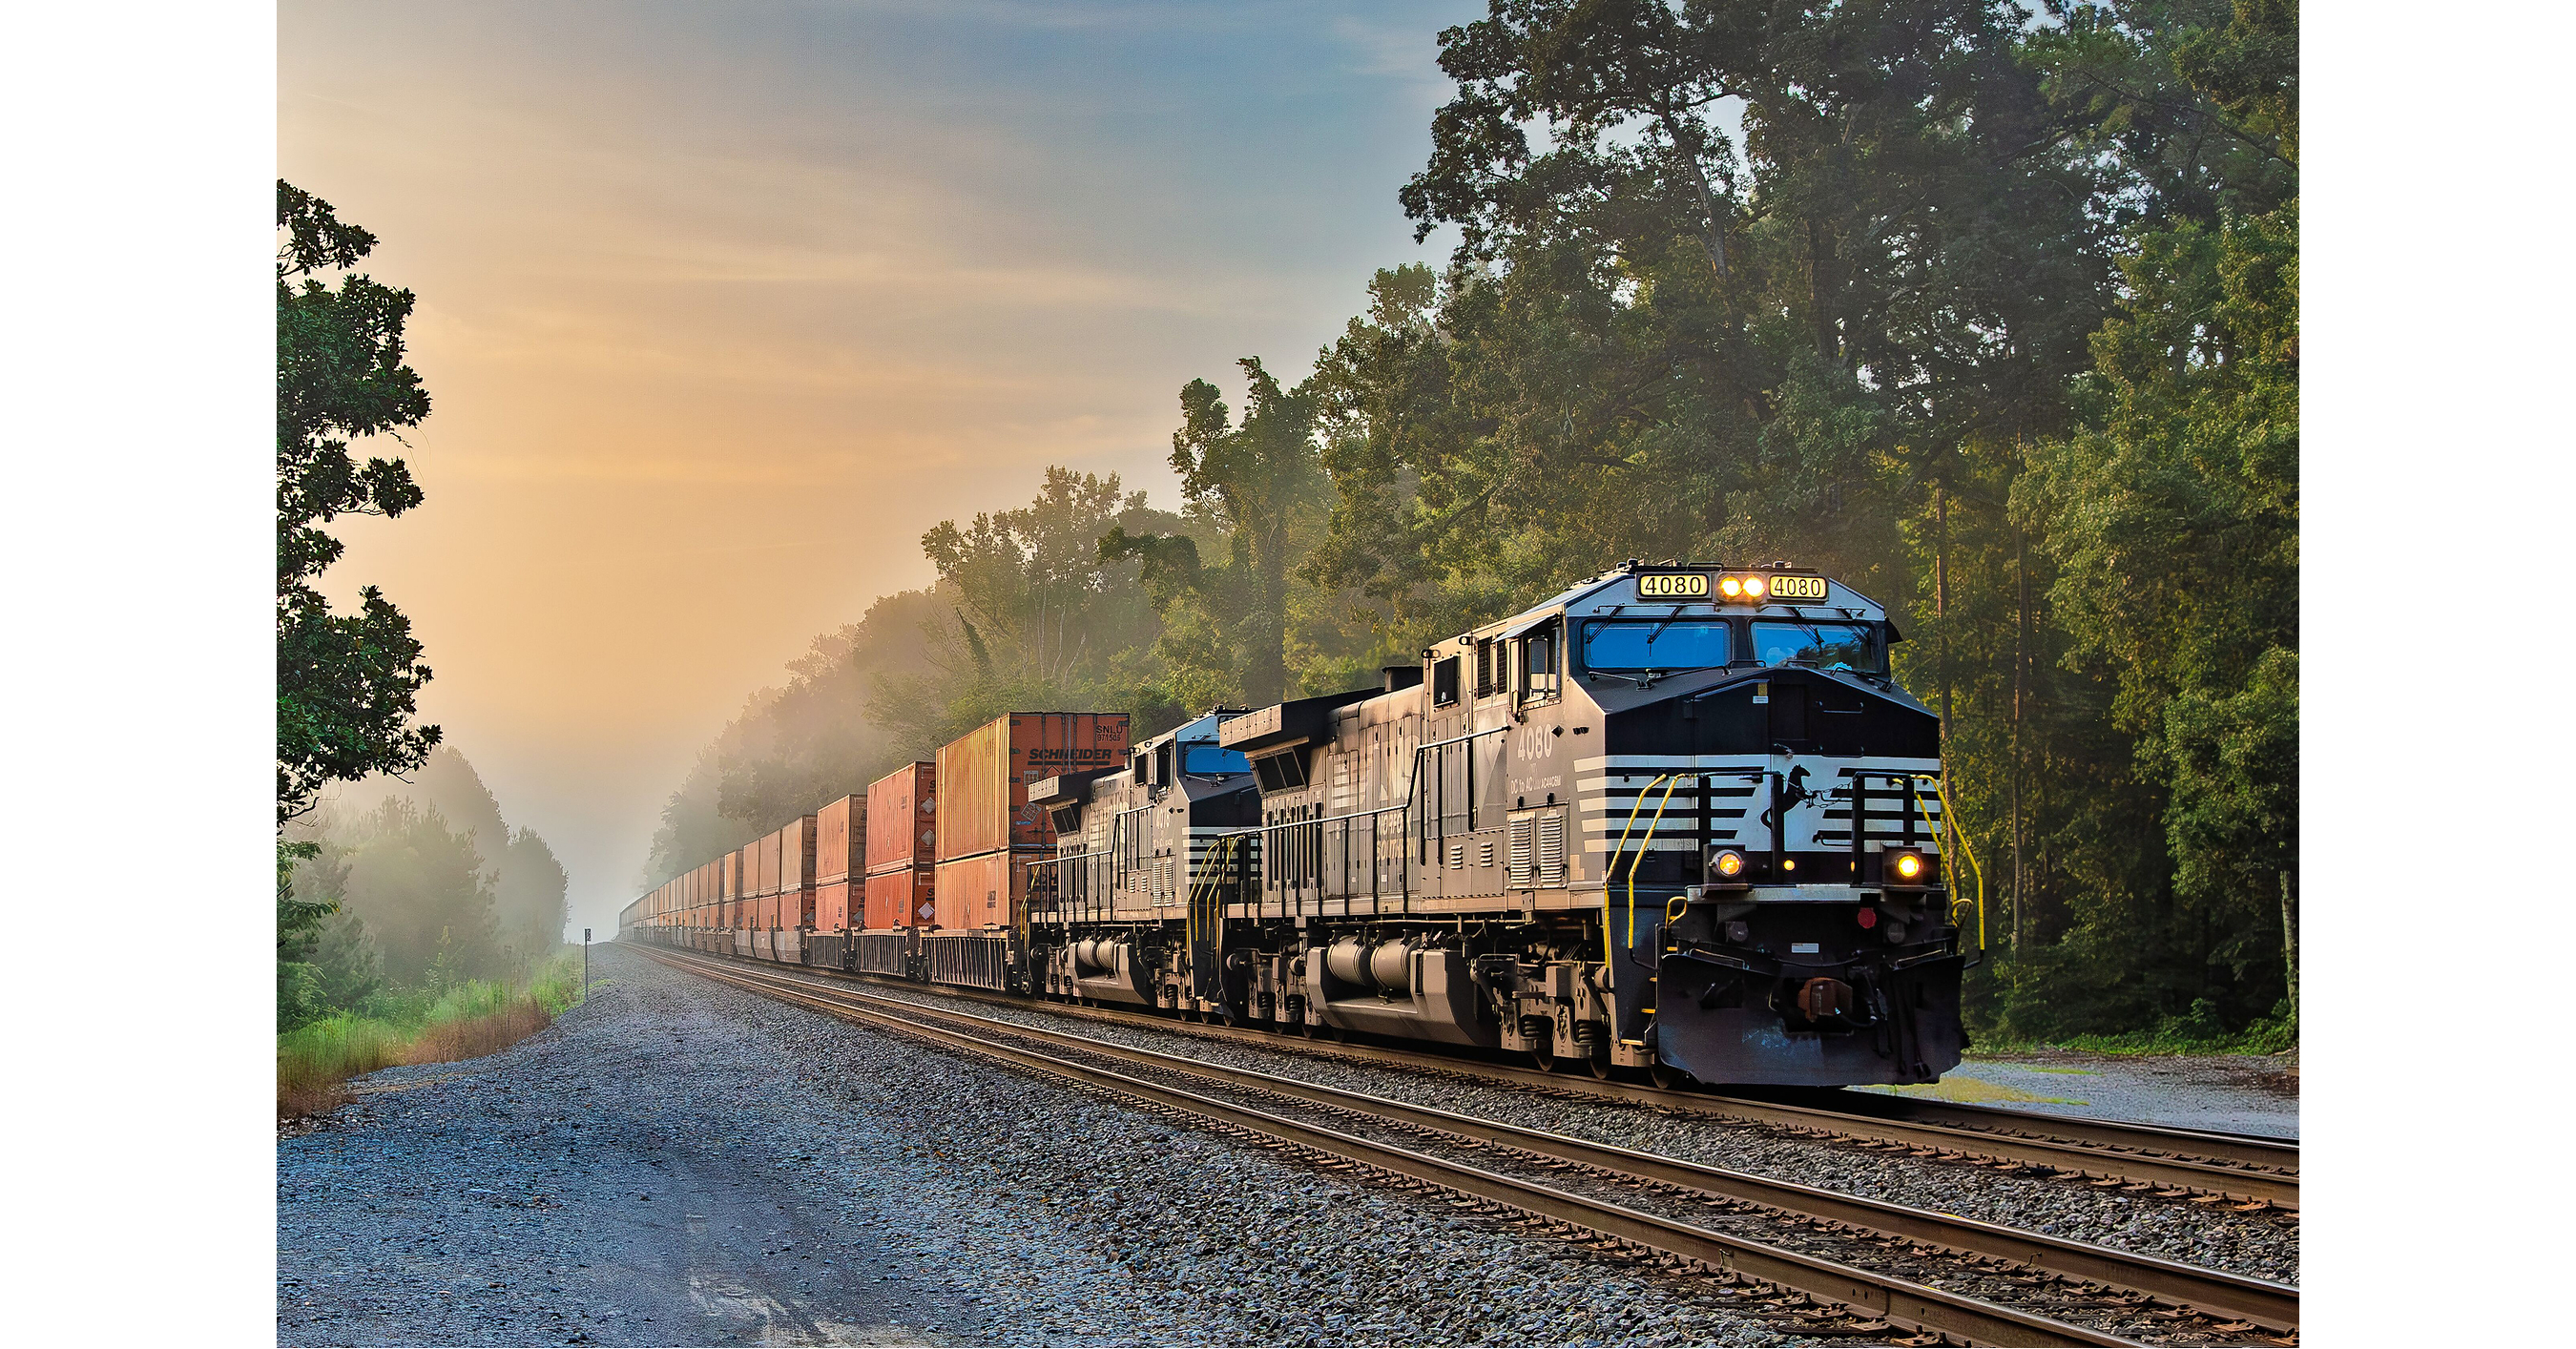
Norfolk Southern and Schneider agreed to combine Schneider’s intermodal assets and logistics capabilities with Norfolk Southern’s eastern U.S. rail network to expand domestic intermodal capacity and service options. Schneider has approximately 23,900 chassis, 26,800 containers and more than 60 North American intermodal rail hubs; Norfolk Southern said intermodal volumes grew 3% in Q3 2026. The agreement comes alongside Norfolk Southern investments across its 22-state network, including terminal expansions and double-stack clearance improvements.
Analysis
The key economic question is whether this creates incremental intermodal freight or reallocates Schneider’s existing eastern volumes from another rail provider. The latter can still benefit Norfolk Southern through better network density and utilization, but is less compelling than net truck-to-rail conversion. Schneider’s owned drayage and equipment should improve control at the rail interface; it does not eliminate exposure to Norfolk Southern’s line-haul reliability or terminal congestion.
Near term (days to weeks), the announcement is a modest positive signal, not evidence of a material earnings step-up: the release gives no committed volumes, pricing, start date, or expected investment return. Over 1–3 months, watch for service-transition execution and any quantified volume or customer wins. Over 6–18 months, successful conversion of truckload lanes could support NSC asset utilization and Schneider’s intermodal mix, while weak lane economics or capacity bottlenecks could dilute returns despite higher volume.
The contrarian risk is treating stated shipper interest and infrastructure investment as proof of profitable growth. Competitive substitution may take share from the incumbent eastern rail provider, but that provider is not identified; do not assume all announced growth is new freight. A sharp reversal in truck pricing could also make intermodal less attractive.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- No high-conviction trade from the announcement alone. Keep NSC and SNDR on a catalyst watchlist; require disclosed volume commitments, implementation timing, or evidence of truck-to-rail conversion before underwriting earnings upside.
- Conditional relative-value idea: favor NSC over SNDR only if subsequent disclosures show incremental, profitable intermodal volume and stable service. NSC may gain network utilization, while Schneider’s benefit depends on customer retention and lane-level economics; absent those data, avoid initiating the pair.
- Monitor NSC intermodal volume and service/reliability indicators, Schneider intermodal mix and operating performance, and any pricing or volume detail. Falsify the positive thesis if the transition disrupts service, NSC intermodal growth stalls, or management indicates volume gains require uneconomic pricing or further unplanned capacity spending.
More News
- DoorDash offers $17 billion for Instacart: ‘the largest companies are only eating more and more of the pie’
- Alphabet Erases $500 Billion as ChatGPT, Google AI Cut into Search
- Alphabet just had its worst day as a public company. BofA now values Google search at a lower multiple than fossil fuel stocks
- Norwegian shares surge 13% on earnings beat, guidance raise
- The U.S. and EU could break their tariff truce over a record-breaking $3.4 billion Airbus loan and a reignited 17-year dispute between aviation giants
- PC chip plunge wipes out a quarter of Intel’s value