
Red Sea Global y Dr. Sulaiman Al Habib Medical Group inauguran The Red Sea Hospital
Source: PR Newswire
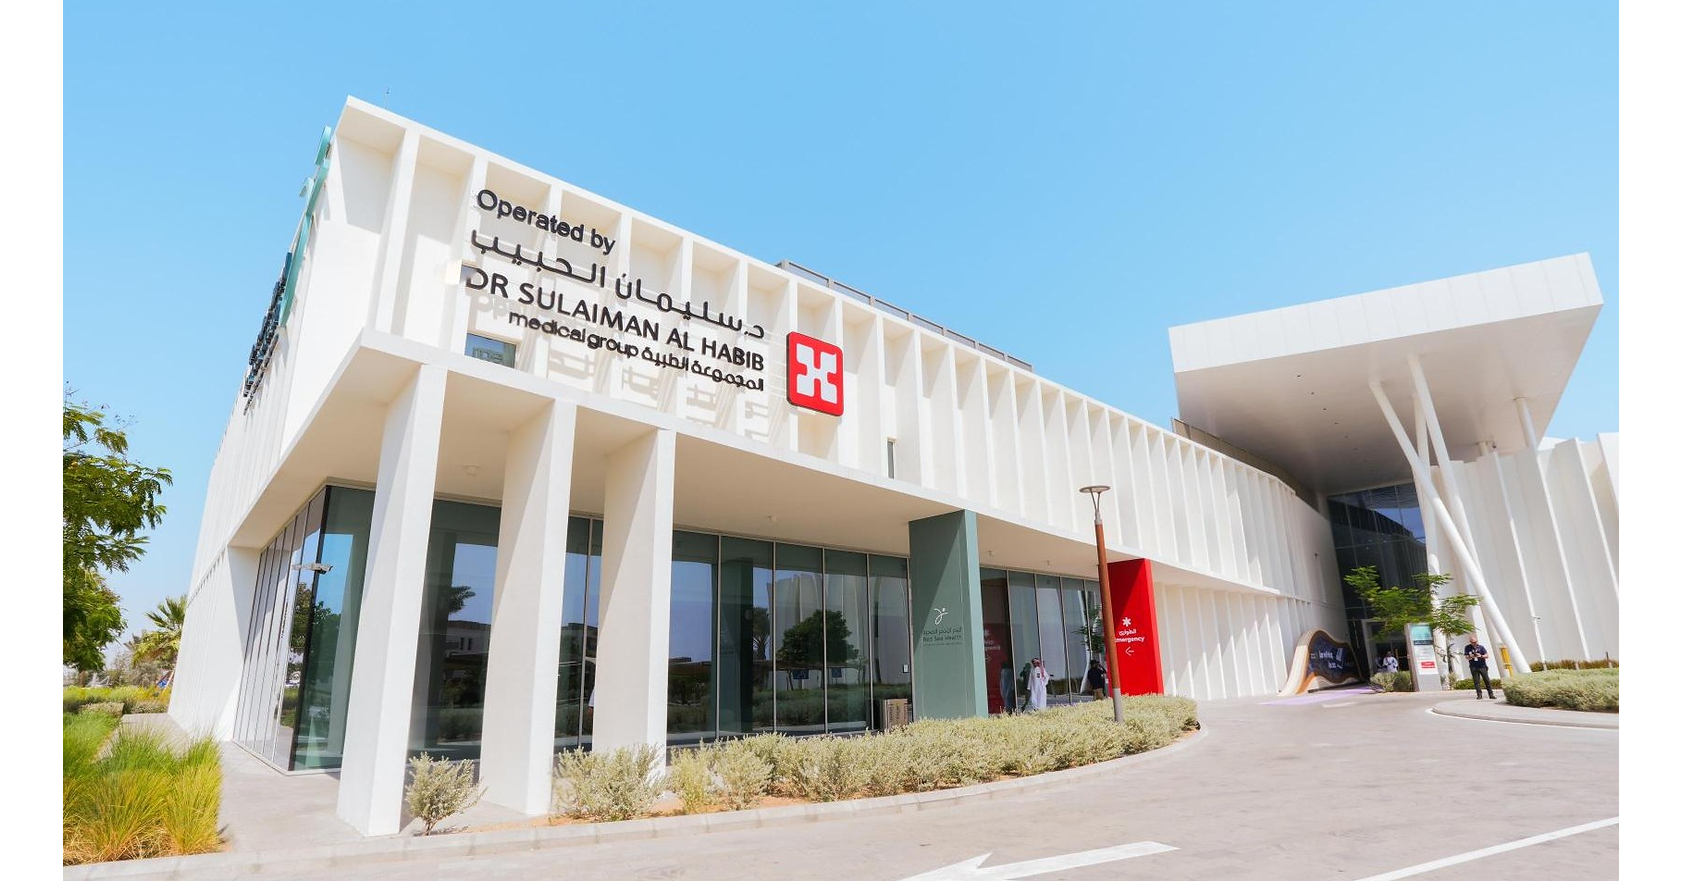
Red Sea Global and Dr. Sulaiman Al Habib Medical Services Group inaugurated The Red Sea Hospital in Saudi Arabia, establishing a clinical hub for RSG's integrated Red Sea Health ecosystem. The HMG-operated facility provides emergency, inpatient, outpatient, surgical, specialist-clinic and digital-health services, supported by six pharmacies and dedicated medical-emergency transport. The project supports Saudi Vision 2030 and destination expansion at The Red Sea, which has 11 operating hotels and plans to open six additional resorts on Shura Island in coming months.
Analysis
For Dr. Sulaiman Al Habib Medical Group (4013.SR), the economic value is less the initial facility ramp and more the validation of an asset-light operating model in Saudi giga-projects. If HMG supplies clinicians, digital systems, pharmacy procurement and referral pathways without carrying real-estate capex, incremental EBITDA margins could exceed those at a conventional greenfield hospital; however, no contract duration, minimum-volume guarantee, ownership structure or reimbursement mix has been disclosed. The near-term earnings contribution is therefore unlikely to move consensus, but the arrangement improves HMG's claim on future destination-healthcare concessions and premium-pay patient flows over 6-18 months.
The competitive implication is modestly negative for 4002.SR (Mouwasat), 4004.SR (Dallah Healthcare) and 4009.SR (Saudi German Health): HMG gains a reference site for integrated tourism, emergency and digital-health operations that may matter in future PIF-linked tenders. The larger second-order beneficiary could be Saudi private-pay healthcare pricing, as high-end destination capacity broadens demand beyond insured urban populations; that thesis requires evidence that utilization is visitor-led rather than employee-led. Consensus may overread the announcement as immediate earnings accretion: remote-site staffing, medical-evacuation readiness and subscale utilization can dilute margins during the first 12-24 months unless the operator receives a fixed management fee or occupancy support.
The key catalyst path is disclosure of HMG's commercial terms, opening of additional destination assets, and management commentary on bed count, staffing, payor mix and ramp losses at the next results cycle. Falsification for a constructive HMG view would be guidance indicating elevated start-up costs, rising personnel expense as a share of revenue, or no expansion of the operating-management pipeline; conversely, a disclosed fee-based contract with limited capex would support a higher-quality growth multiple.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Key Decisions for Investors
- No immediate directional trade on the release alone: treat 4013.SR as a watch-list catalyst rather than a forecast-changing event until contract economics, capex responsibility and utilization assumptions are disclosed.
- Over the next 1-3 months, accumulate 4013.SR only on a pullback if management confirms a fee-based or low-capex operating structure and does not raise personnel-cost or start-up-loss guidance; target a 6-18 month relative-outperformance position versus 4002.SR, with thesis invalidated by margin dilution or absent pipeline conversion.
- Monitor a relative-value pair, long 4013.SR / short 4009.SR, only if HMG demonstrates additional premium-destination mandates. The risk is that Saudi German's valuation discount already compensates for execution risk, while HMG's premium multiple leaves little room for an immaterial contract.
- Set an earnings-call alert for disclosed bed capacity, management-fee terms, pharmacy economics and payer mix. Without those data, avoid modeling revenue or assigning a multiple uplift to HMG.
More News
- All Iranian airlines to be 'shut down' from Wednesday, Bessent tells CNBC
- Taiwan benchmark Taiex rises to record intraday high as tech stocks advance
- AMD joins the $1 trillion club as chip rally surges - our AI Strategy saw it early
- Jamie Dimon says hyperscaler AI spending could hit $1 trillion next year
- 20 countries propose global oversight body to manage AI dangers
- Australia Bets on AI to Spur Economic Growth For Decades
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Portfolio Monitoring: Build an Alert Policy Analysts Can Audit
- The Great Divergence: North American Banking at the Crossroads of Monetary Policy and Agentic AI (Q4 2025 Bank Earnings)