
NEW ORLEANS MARRIOTT ANNOUNCES COMPLETION OF PROPERTY-WIDE GUEST ROOM RENOVATION AND REIMAGINED M CLUB
Source: PR Newswire
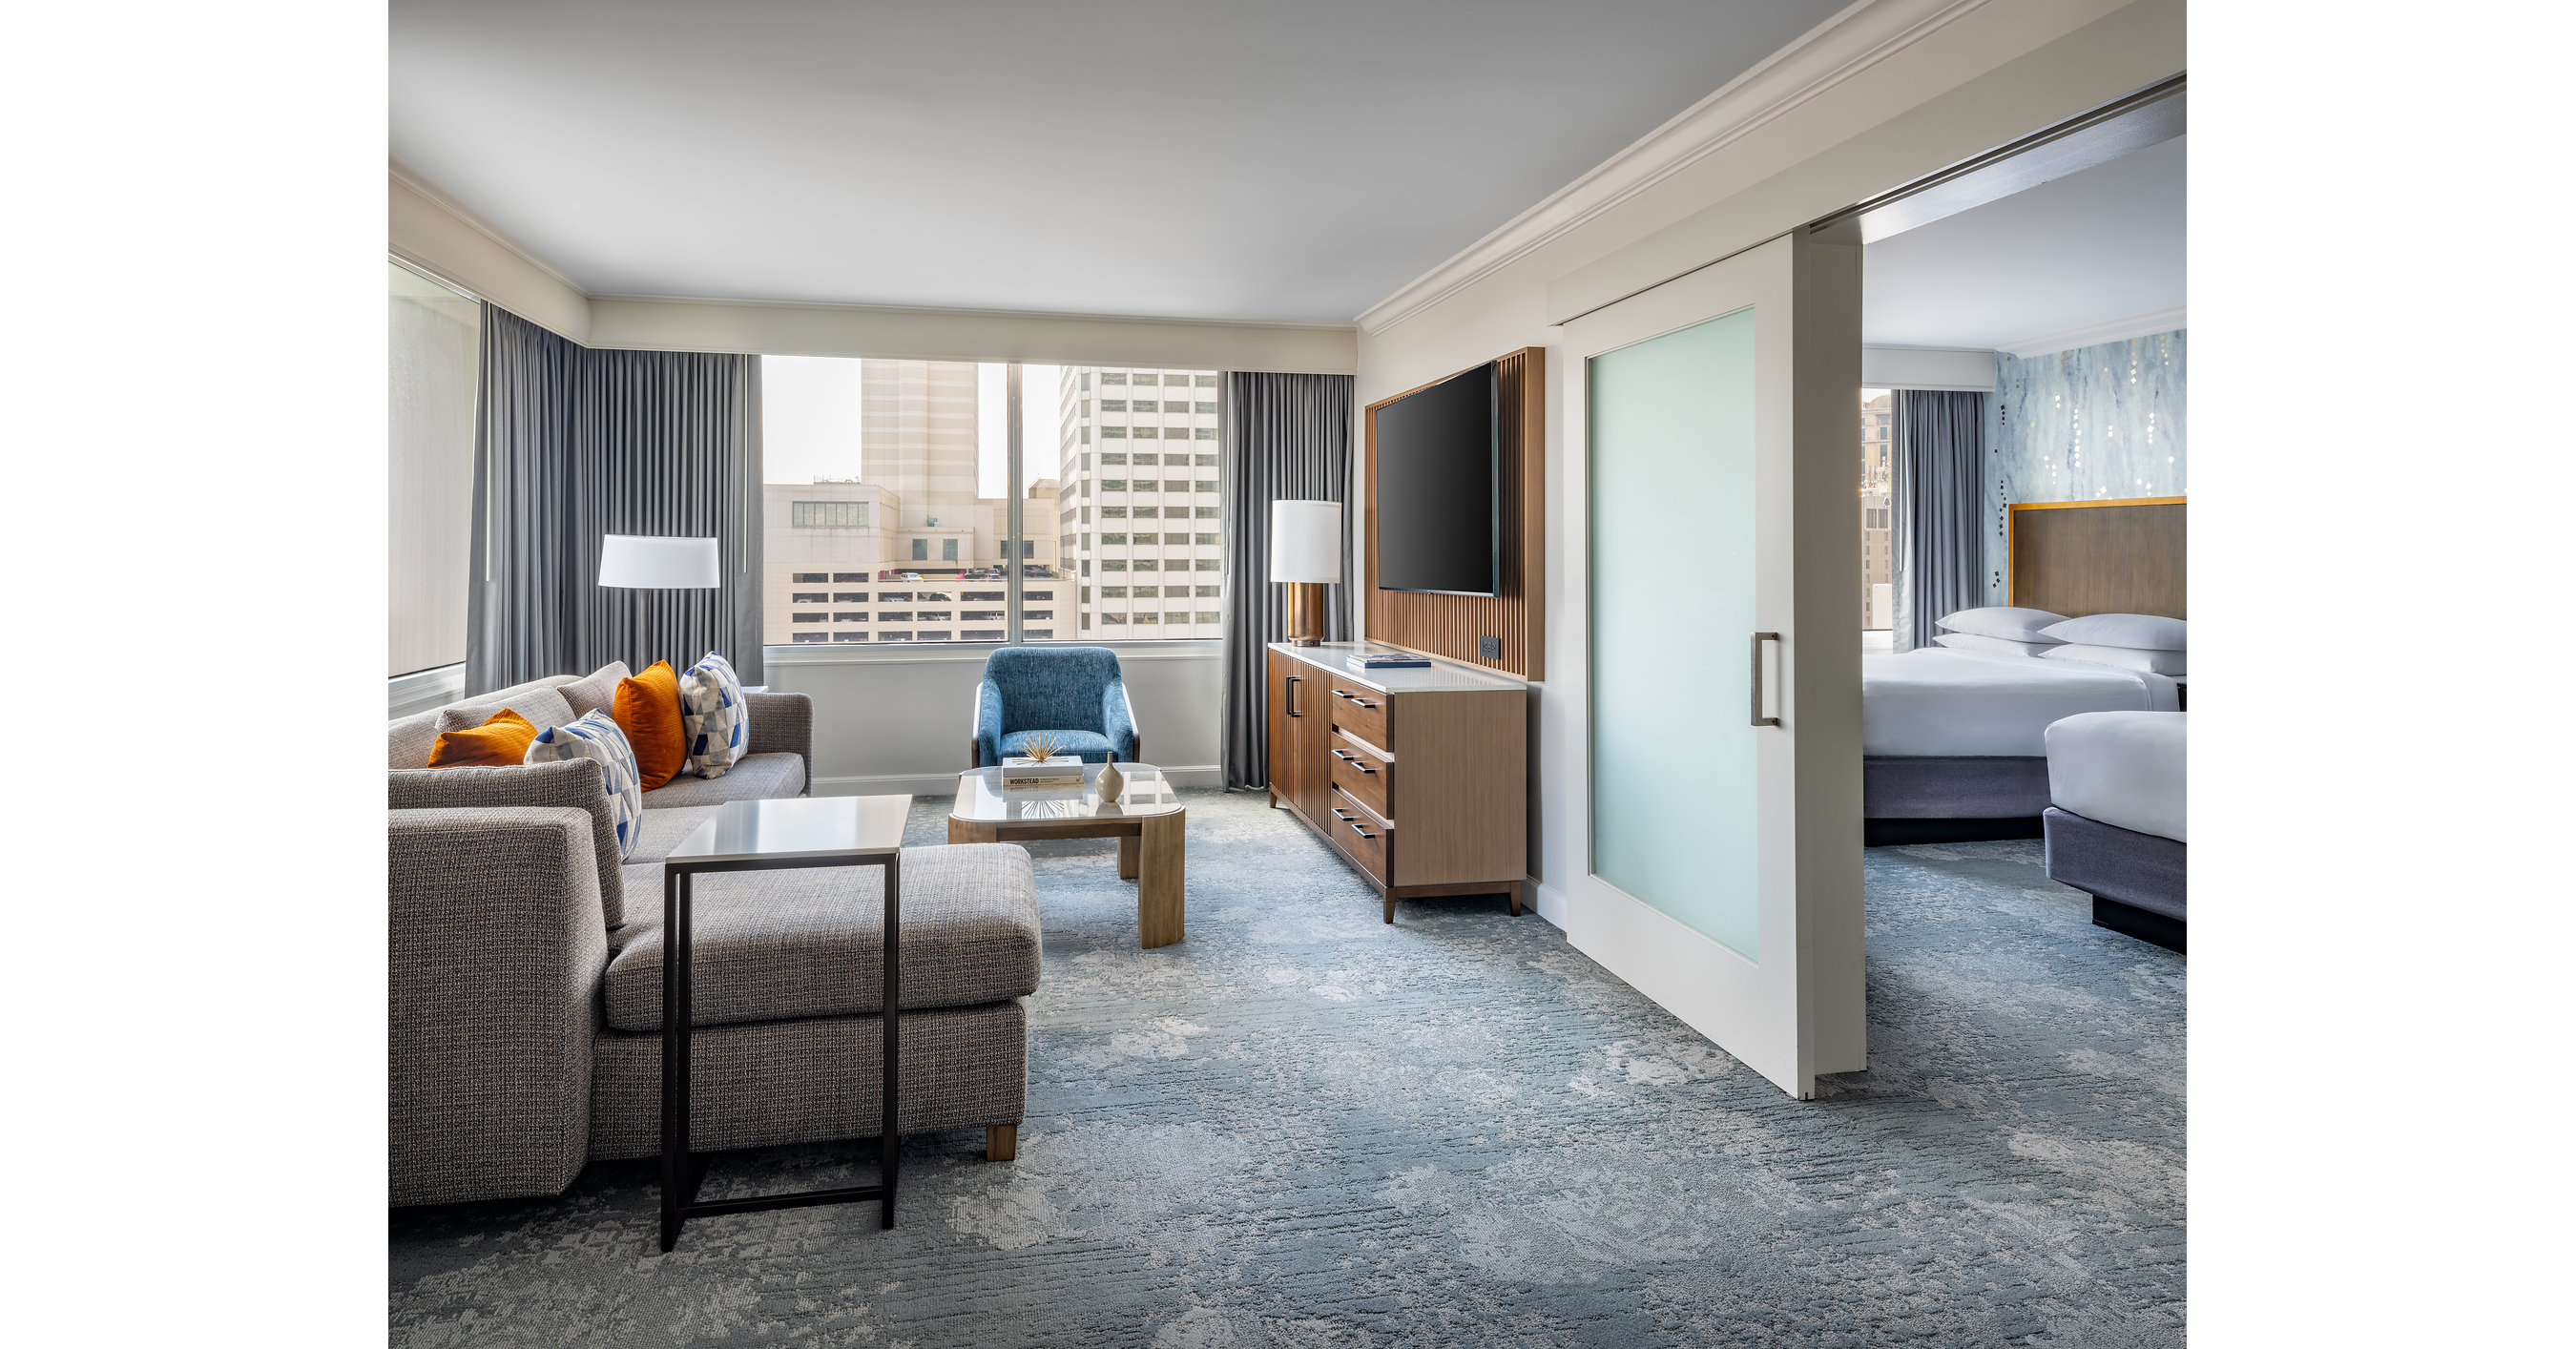
New Orleans Marriott completed a full renovation of all 1,333 guest rooms and suites and redesigned its M Club lounge, reinforcing its positioning for leisure, group, and convention travelers. The property offers more than 86,000 square feet of meeting space and is promoting stays with discounts of up to 15% for extended weekends and up to 10% for advance purchases. The upgrade is a positive property-level investment but is unlikely to materially affect Marriott International's broader financial performance.
Analysis
This is immaterial to Marriott International's consolidated earnings, but it is directionally supportive of the managed/franchised fee stream if the asset can sustain a higher group and premium-leisure mix. The relevant mechanism is not room count growth; it is RevPAR index gain versus nearby convention inventory, with renovated room configurations potentially lifting occupancy on shared-stay demand and reducing the need to discount during shoulder periods. For MAR, any benefit will appear only indirectly in systemwide U.S. group RevPAR and management/franchise fee growth over the next 2-4 quarters.
The more investable read-through is competitive: a refreshed large-box property near the convention center can pressure independent French Quarter hotels and older full-service branded supply, including Hilton, Hyatt and IHG properties dependent on citywide convention compression. The renovation may also allow the property to defend rate while offering promotional packages, which would shift demand rather than create it; New Orleans' convention calendar, airlift and event demand remain the binding constraints. SBUX exposure is effectively nil: an on-property licensed café does not alter consolidated store economics.
Consensus should not extrapolate a single-asset refresh into a MAR demand signal. Property-level owner capital expenditure can improve brand standards and reduce churn, but MAR captures a modest share of incremental room revenue while the owner bears renovation payback risk. A broader signal would require evidence that group bookings, ADR and meeting-space utilization outpace the local competitive set after the reopening marketing period.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- No standalone MAR trade on this announcement; maintain existing fundamental view and use it only as a datapoint for U.S. urban group-demand monitoring over the next 1-3 quarters.
- Set an alert around MAR quarterly disclosures: upgrade the read-through only if U.S. group RevPAR and management/franchise fee growth accelerate while company-wide net unit growth remains intact; weaker U.S. urban ADR or softer group commentary falsifies the benefit.
- For lodging relative-value books, monitor long MAR versus a basket of urban full-service exposure in HLT/H/ IHG over 6-12 months, but do not initiate from this release alone; require independently observable New Orleans ADR/occupancy share gains and convention booking data.
- Avoid treating SBUX as a beneficiary. Any local licensed-store sales uplift is too small to matter; no actionable earnings sensitivity exists.
More News
- Starbucks stock outlook: premium valuation meets a turnaround still in progress
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
- Chinese investors rush into US stocks as Beijing opens wider path overseas
- Is Amazon Stock a Buy After Its Best Quarter in Years?