
SANY Renewable Energy ogłasza ponad 300-procentowy wzrost przychodów z rynków zagranicznych podczas WindEnergy Hamburg 2026
Source: PR Newswire
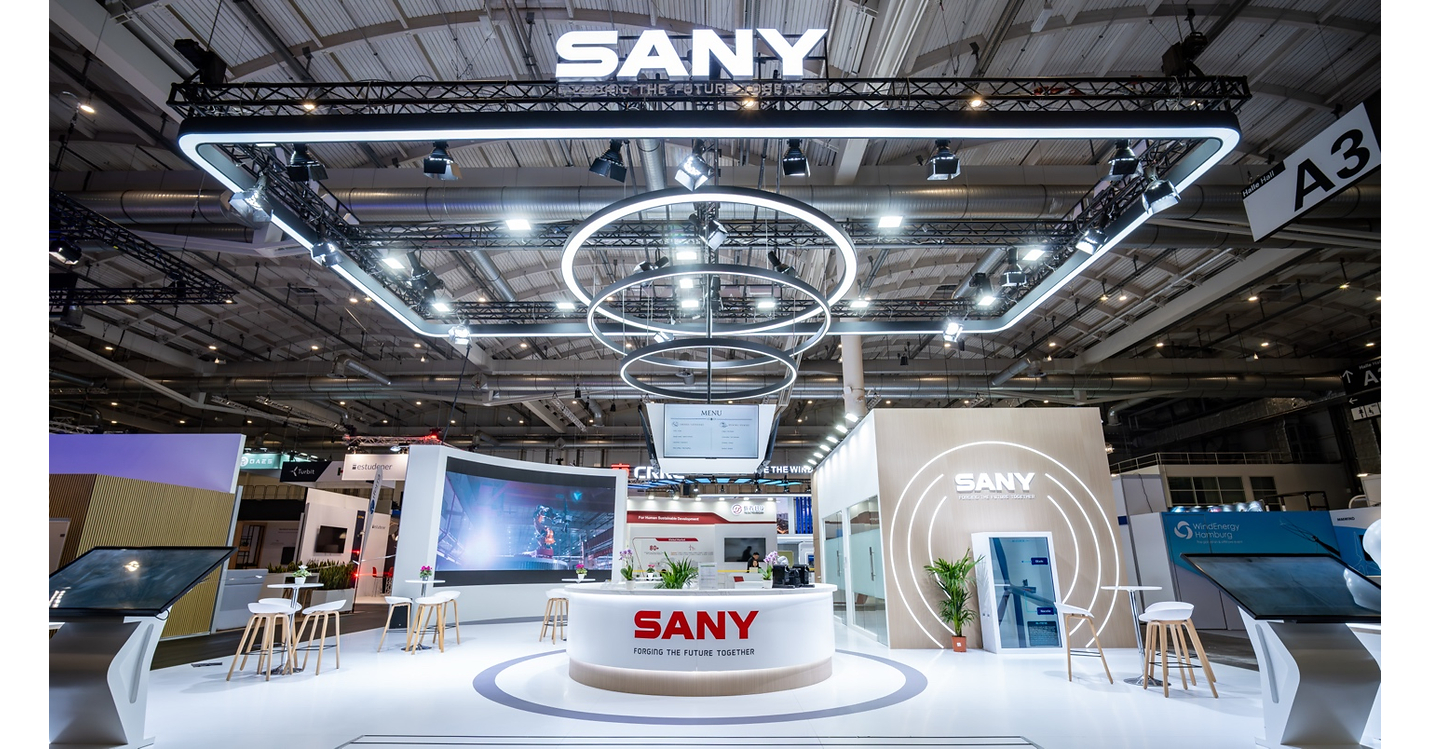
SANY Renewable Energy reported overseas revenue growth of more than 300% in H1 2026, while signed international wind-turbine orders approached 5 GW. DNV granted European type certification for SANY's SI-17578EU turbine, supporting market expansion, and the company showcased 10 MW turbine technology and AI-enabled blade-to-tower clearance modeling. Overseas installed capacity reached 1,462.35 MW, with more than 100 MW of projects commissioned in 2026, reinforcing its international execution track record.
Analysis
The relevant signal is not S&P Global's supplier classification for SPGI, which has no material earnings read-through, but whether a Chinese OEM can convert European technical acceptance into financeable projects. If SANY Renewable Energy (688349.SS) wins EU orders at materially lower turbine pricing, Vestas (VWS.CO), Nordex (NDX1.DE), and Siemens Energy (ENR.DE) face a more difficult margin-recovery path in onshore wind: incumbents may retain volume but need to concede price, service terms, or warranty coverage. The first-order impact is likely limited because EU permitting, local-content preferences, and bankability reviews extend award-to-revenue conversion well beyond 12 months.
The second-order risk is concentrated in the balance sheet and service model. A new entrant can use aggressive turbine pricing to secure installations, but project-finance lenders will focus on multi-year availability guarantees, spare-parts localization, and parent support; any under-reserved warranty event would rapidly erase the apparent volume advantage. Conversely, demonstrated availability through one or two European winter cycles could pressure incumbent valuation multiples before SANY's reported revenue becomes material, particularly for Nordex, whose onshore exposure leaves less diversification.
Consensus may overestimate the immediacy of disruption. Certification is an entry condition rather than proof of repeatable EU profitability, and trade-defense measures, cybersecurity scrutiny, and grid-code compliance can raise delivered cost or delay approvals. The more investable near-term expression is to monitor tender pricing and financing approvals rather than extrapolate a high overseas-growth rate from a low base; SPGI's mention is reputational data, not an actionable catalyst for its earnings.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.68
Ticker Sentiment
Key Decisions for Investors
- No directional SPGI trade: treat the supplier-list reference as immaterial to revenue and EBITDA. Reassess only if S&P Global launches a paid benchmark, ratings, or data product directly tied to Chinese wind-OEM financing volumes.
- Place a 1-3 month alert on European onshore-wind tender results and disclosed turbine ASPs: repeated awards to 688349.SS in Spain, Central Europe, or Latin America at a discount greater than 10-15% versus VWS.CO/NDX1.DE would support a tactical long 688349.SS / short NDX1.DE pair, subject to confirmation of local-service and financing commitments.
- Maintain caution on shorting VWS.CO or ENR.DE solely on this development. A short thesis requires evidence of order-margin deterioration or incremental warranty provisions at the next reporting cycle; absent that, incumbents' installed-base service revenue and procurement scale can offset isolated price competition.
- For 6-18 months, monitor EU trade-policy and project-finance decisions as thesis falsifiers. Tariffs, local-content enforcement, or lender refusal to fund projects using SANY equipment would impair the challenger’s conversion rate and favor VWS.CO and ENR.DE; multiple financed, operating projects with contractual availability data would validate the competitive threat.
More News
- Markets are rapidly coming around to the reality that the Fed has a lot more work to do
- SpaceX Can't Join the S&P 500 Before June 2027 -- and Its Losses Could Keep It Out Longer
- Nvidia's Demand Is Outpacing Its 70% Growth Forecast, and That Is Just the Beginning
- Market sees next Fed hike in October, following Barr comments and hot inflation reading
- Business Activity in the Euro Area Reaches Three-Year High
- The Economy Is Booming, So the Market Indexes Fell. Go Figure.
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Eli Lilly Q4 2025 Earnings: Revenue Surges 43% as Mounjaro and Zepbound Dominate the GLP-1 Market
- Investment Research Software Costs: A 2026 Budget Framework