
Maura Burns, Former Chief Operating Officer of the CIA, Joins the SAGINT Board of Advisors
Source: PR Newswire
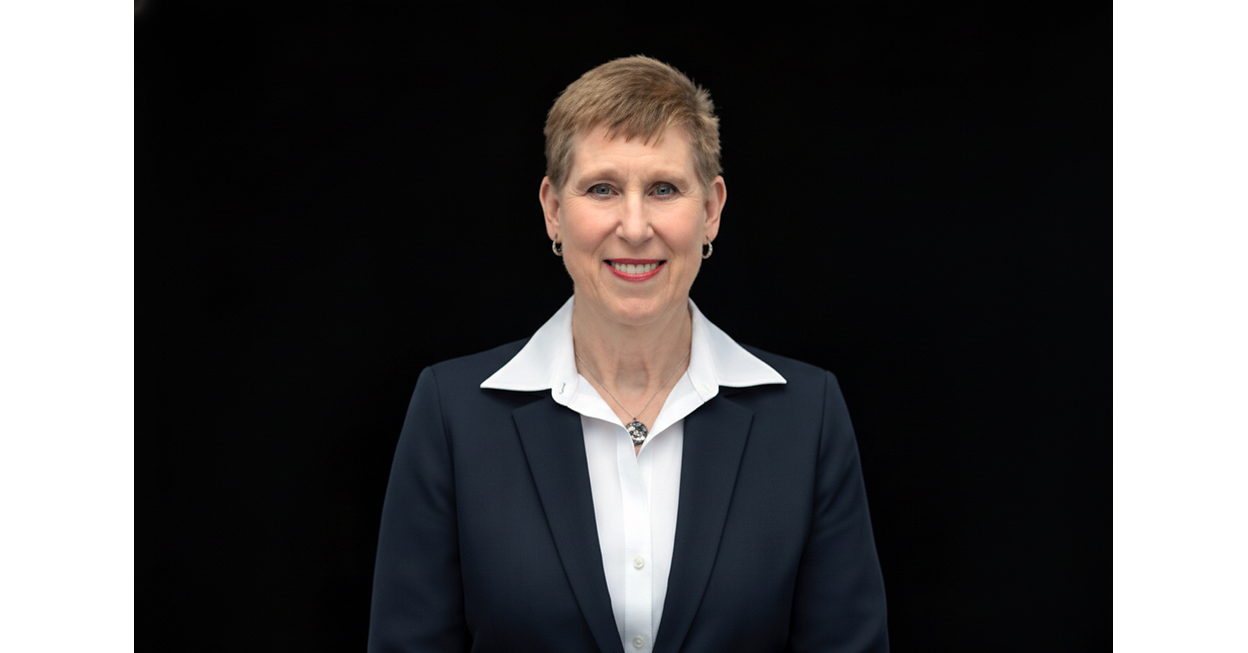
SAGINT appointed former CIA Chief Operating Officer Maura Burns to its advisory board as it prepares customers for stricter U.S. critical-material origin requirements effective January 1, 2027. The expanded DFARS restriction will cover material mined, refined, separated, melted or produced in covered countries, while a July 2026 executive order directs defense suppliers to map critical-material supply chains back to raw-material origin. SAGINT says its Digital Warehouse Receipts provide lot-level, process-data-derived evidence of origin, custody, control and assay, positioning the company to benefit from rising traceability and compliance demand.
Analysis
The investable implication is not the private-company appointment; it is a near-term compliance bottleneck that increases the value of verified provenance across defense-linked critical-mineral supply chains. Public primes such as LMT, RTX, NOC, GD and LHX face asymmetric execution risk: a small fraction of non-compliant inputs can delay deliveries or require costly supplier requalification, while direct compliance software spend is likely immaterial to their earnings. The more sensitive public exposures are specialty-material suppliers with concentrated defense revenue—MP, UUUU, ATI, CRS, and LYB—where traceability can become a qualification advantage or a working-capital constraint if lots cannot be documented and financed cleanly.
Over the next 1-3 months, expect limited broad-market repricing until implementation guidance defines covered materials, acceptable evidence, audit liability and subcontractor flow-down requirements. The second-order effect is supplier consolidation: smaller refiners and processors lacking instrumented process data may lose approved-vendor status, allowing qualified domestic/ally producers to secure longer contracts and better pricing. This is structurally favorable over 6-18 months for MP and ATI if procurement rules reward verifiable origin rather than merely geographic representations; it is unfavorable for commodity intermediaries dependent on opaque multi-country processing routes.
Consensus may overestimate the immediacy of revenue benefits to domestic miners. Compliance deadlines create administrative friction before they create new mine output, and DoD procurement cycles, qualification testing and capacity expansion remain the gating items. The thesis is falsified if forthcoming DoD guidance permits supplier certifications or retrospective documentation as sufficient evidence, materially reducing the premium for lot-level chain-of-custody systems; monitor contract language and supplier-audit disclosures in 4Q26 results.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Key Decisions for Investors
- Maintain a 6-18 month watch-to-buy bias on MP: initiate only after DoD implementation guidance explicitly favors mine-to-lot provenance or MP discloses incremental qualification/contract wins. Target a 10-15% position risk budget; invalidate on evidence that non-domestic separated material remains broadly acceptable under grandfathering or certification safe harbors.
- Pair trade for the guidance catalyst: long MP / short REMX over a 3-6 month horizon, sized beta-neutral. MP has more direct leverage to U.S. sourcing and qualification premiums, while REMX retains meaningful exposure to opaque offshore processing. Exit if the rules prove technology-neutral and documentation-light.
- Do not add broad defense-prime exposure solely on this development. Instead, monitor LMT, RTX and NOC 4Q26/1Q27 calls for disclosed supplier requalification costs, inventory buffers or delivery-risk commentary; such disclosures would support a tactical short versus ITA if compliance disruption becomes program-level rather than supplier-level.
- Track ATI and CRS for long opportunities following evidence of multiyear aerospace/defense material contracts with traceability-linked pricing. Require confirmation through backlog growth or margin guidance—not advisory-board announcements—before underwriting a multiple expansion.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Budget 2026 speech
- The UK cuts energy bills, taxes banks and boosts defense in high-stakes budget
- Microsoft's Big Bets on AI Start to Pay Off
- Google's Gemini 4 Carbon looks like a diamond in the rough
- Microsoft’s strong quarter backs up its stock rebound. Here's our new price target
From AllMind Research
- AllMind Platform Feature Updates - Fall 2026
- AI Credit Covenant Monitoring: From Clause to Review
- AI-Led Expert Interviews vs. Transcript Libraries
- Augmented Intelligence: AllMind, Elevate Human Judgement With an Accessible, Powerful, Data-Driven Financial AI Toolkit
- Choosing an AI Copilot for Equity Research