
Zoomlion Expands Mining Machinery Business as International Revenue Grows
Source: PR Newswire
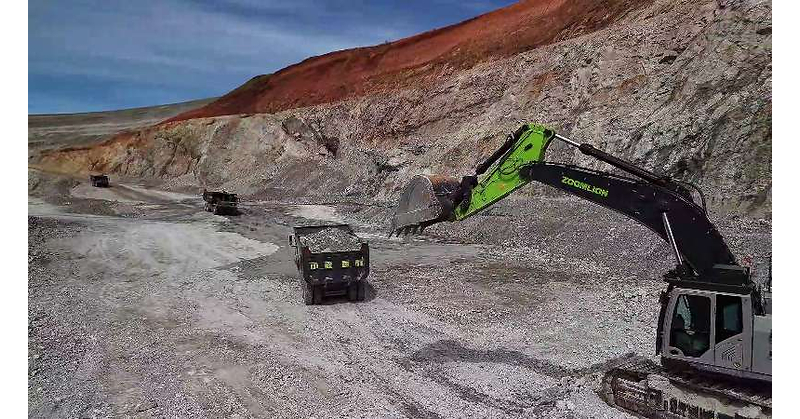
Zoomlion’s mining machinery business grew more than 57.20% year on year in the first half of 2026, while international revenue rose 12.45% to RMB 15.535 billion, or 57.25% of total revenue. The company highlighted electrified and autonomous mining equipment, including reported fuel savings of up to 40% for hybrid trucks and a mine deployment where fleet coordination increased average daily truck trips by over 10%. It is expanding overseas infrastructure, with more than 30 primary hubs, over 530 additional outlets and more than 300 spare-parts warehouses as of June 30, 2026.
Analysis
The investable signal is potential mix improvement, not proof of an earnings inflection. Mining equipment and overseas sales could reduce dependence on China construction demand, but the release gives neither mining’s revenue base nor segment margins, order intake, backlog, or cash conversion. The reported growth therefore cannot yet be translated into consolidated EPS sensitivity.
The second-order opportunity is lifecycle service: electrification, autonomy, parts availability, and local support can raise customer switching costs and create recurring aftermarket revenue. But these benefits accrue only if Zoomlion can demonstrate uptime and total-cost savings across varied mines; its operating-cost claims and deployment productivity figures are company-reported, not independent validation. Caterpillar and Komatsu have established global service networks, so execution—not product specifications alone—will determine whether Zoomlion can win repeat orders outside China.
Near term, the release may support sentiment but is unlikely to justify a durable re-rating without order and margin evidence. Over 1–3 months, watch mining orders, overseas backlog, receivables, and segment profitability. Over 6–18 months, localized service capacity could enable share gains, while also adding fixed costs, working-capital needs, and exposure to trade restrictions, local-content rules, and commodity-capex cycles. Electrification is not an automatic tailwind: mine power infrastructure, charging downtime, and uncertain residual values can slow adoption. Contrarian read: investors may overvalue headline growth while underweighting execution and financing costs; equally, they may underappreciate the strategic value of a functioning international service footprint.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.52
Key Decisions for Investors
- No trade on this release alone: treat it as a diligence catalyst, not earnings confirmation. Verify mining revenue and gross margin contribution, order intake/backlog, and segment cash conversion before underwriting a valuation premium.
- Put Zoomlion on an overseas-growth watchlist; upgrade the thesis only if subsequent reporting shows repeat international mining orders and improving service economics without disproportionate receivables or inventory growth.
- Track Caterpillar and Komatsu disclosures for pricing, delivery times, and mining-equipment orders. Evidence of persistent share gains by Zoomlion outside China would strengthen the competitive thesis; isolated project wins would not.
- Falsifiers: mining orders or overseas growth decelerate, segment margins fail to improve, working capital rises materially faster than sales, or localization faces regulatory/trade barriers. Also monitor mine-capex plans and commodity prices, which can reverse equipment demand with a lag.
More News
- US forces disable ship ‘attempting to run’ Iran blockade in Gulf of Oman
- Attack on Saudi airport kills 12 people and wounds more than 300—the deadliest strike in any Gulf Arab country since the start of the Iran war
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- Ship captains and crews transiting the Strait of Hormuz make so much danger pay that they’re ‘almost being viewed as mercenaries’
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Palantir (PLTR) Q4 2025 Earnings: 70% Revenue Growth, Then an 11% Single-Day Crash
- AlphaSense Pricing: What Public Contract Data Shows in 2026