
XPeng: Attractive Catalyst Landscape
Source: seekingalpha.com
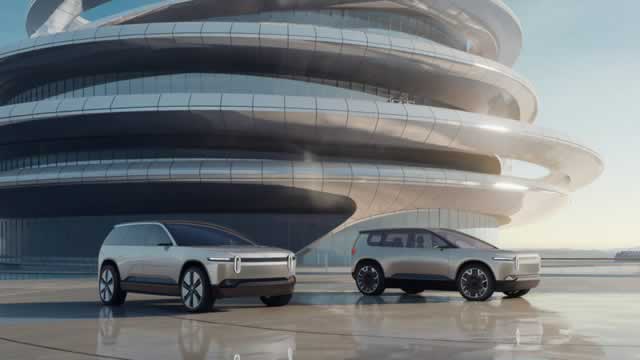
XPeng reported Q2 net loss that tripled, while deliveries were flat year-over-year and vehicle margins held at 12.1%. The company guided to 115,000–121,000 deliveries in Q3 and expects a ramp to 60,000 monthly units by year-end. Despite the loss deterioration, the Buy view is supported by expected Q4 traction from new SUV launches (G9L and Mona L05).
Analysis
The key issue is not the reported loss itself; it’s that stable gross margin is being outpaced by a much heavier fixed-cost base, which means incremental volume has to arrive fast enough to absorb R&D/SG&A or the market will keep assigning XPEV a “growth without earnings” multiple. In China EV, that dynamic usually turns on product cadence more than quarterly noise: if the next launches land, the stock can re-rate quickly; if not, the market will focus on cash burn and discounting pressure.
The competitive read-through is more important than the company-specific print. A credible ramp toward much higher monthly run-rate would force rivals like NIO, Li Auto, and especially Tesla China to defend share with incentives, which would pressure sector ASPs and delay profitability across the group. BYD is the structural winner if the market stays price-competitive, because it can trade volume for margin better than smaller peers; XPEV only benefits if its new models create enough differentiation to reduce reliance on rebates.
Near term, the stock likely trades on delivery data and pre-orders rather than accounting results. Over 1-3 months, the falsifier is simple: if monthly registrations and Q3 deliveries do not trend toward the implied ramp, the Q4 thesis becomes a forward-guide miss story. Over 6-18 months, the real question is whether XPEV can convert product launches into sustained operating leverage, or whether it remains a niche volume player with structurally low pricing power in a brutally competitive market.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.22
Ticker Sentiment
Key Decisions for Investors
- Do not chase the stock on the earnings print alone; wait for weekly China insurance-registration data to confirm a step-up in demand before taking directional risk.
- If entering long, prefer a December-Q4 call spread on XPEV rather than stock: limited downside if the launch slips, with upside tied to evidence of ramp; thesis invalidates if registrations fail to accelerate over the next 4-6 weeks.
- Relative-value idea: long XPEV / short NIO for 1-3 months, betting that the cleaner product-cycle catalyst and better margin profile will outperform if the China EV tape stays promotional; cut the pair if NIO delivers a stronger-than-expected order trend or XPEV margin compresses below the low-teens.
- Use BYD as the sector hedge: if you are long XPEV into Q4, partially hedge with short exposure to the broader Chinese EV basket (e.g., KWEB or an EV ETF proxy) because the likely second-order effect of a demand push is pricing pressure, not just share gains.
- Set a hard watch item on the next quarter’s operating expense growth versus delivery growth; if opex remains faster than units, the market will treat the model launches as a timing issue rather than a durable earnings inflection.
More News
- Why is T-Mobile stock tumbling today?
- Why is Verizon stock sliding today?
- SpaceX wants to become a 'major mobile carrier' with low-band spectrum acquisition
- OpenAI projected to bring in $20bn less in revenue than expected
- Soitec climbs 7% as BofA turns bullish on silicon photonics demand
- Schott Pharma drops after Deutsche Bank downgrades on demanding valuation