
Global Tech Hiring Steadies as Skills Take Priority
Source: PR Newswire
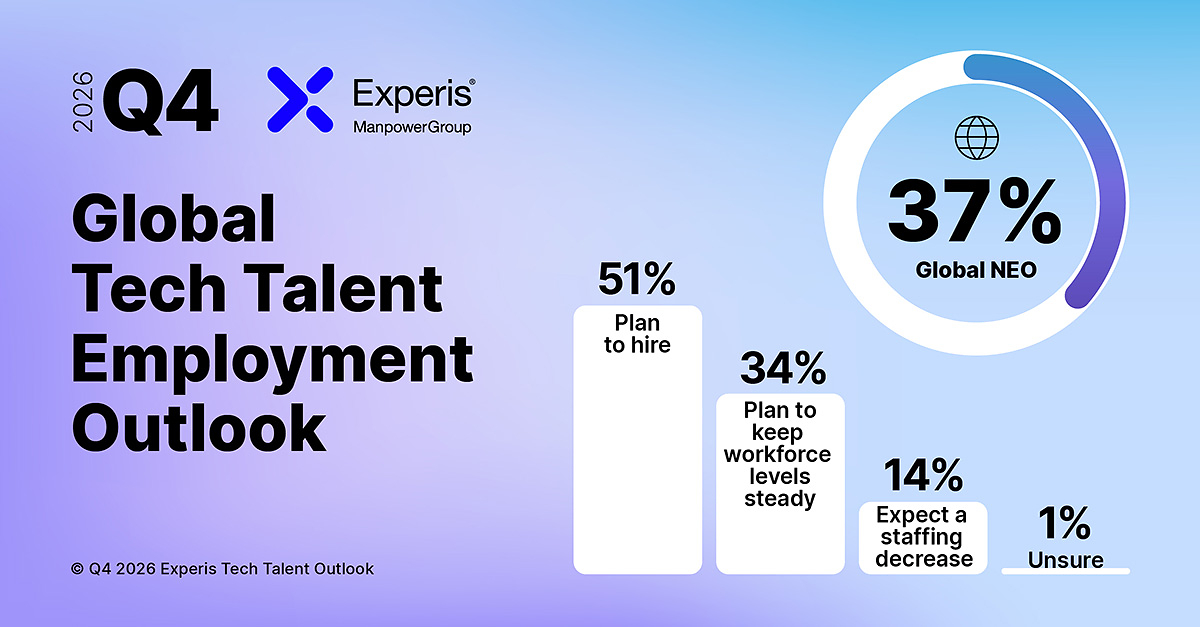
Experis reported a global Q4 2026 Tech & IT Services Net Employment Outlook of 37%, up 2 points quarter-over-quarter and unchanged year-over-year, with 51% of employers planning to add staff versus 14% expecting cuts. Demand is shifting toward a blend of human and AI capabilities: communication and teamwork rank highest at 41%, while AI modeling and application development leads technical demand at 34%. Hiring is strongest in Guatemala (74%), Brazil (61%) and India (53%), while the U.S. remains at 37% but is down 10 points from a year earlier.
Analysis
This is incrementally supportive for MAN's higher-value Experis mix, but not sufficient to underwrite a broad earnings upgrade. The economically relevant signal is that AI adoption is creating implementation labor demand rather than simply replacing headcount: staffing firms with credible technology-specialist supply can improve gross margin and fill rates, while lower-skill general staffing remains exposed to automation and cyclical client budget pressure. MAN's valuation response should depend on whether Experis growth can offset weaker U.S. hiring demand and improve group mix, not on the survey headline itself.
The second-order beneficiary set is specialized IT staffing and digital-consulting vendors—ASGN, RHI, ACN and GLOB—where scarce AI/data talent supports pricing. Conversely, hyperscalers and software vendors do not necessarily benefit near term: persistent implementation hiring implies enterprise AI deployments remain labor-intensive, potentially delaying realized productivity savings and extending services costs. India’s relative hiring strength favors offshore delivery economics for GLOB and INFY, though wage inflation could capture part of the benefit.
Near-term market impact is likely limited because this is company-sponsored survey data and U.S. momentum is weaker than the global aggregate. Over 1-3 months, the investable catalyst is Q4 client-order commentary, Experis organic revenue, and gross-margin progression; a sustained recovery would matter over 6-18 months only if AI-skilled placements become a larger share of revenue. Falsification: another sequential decline in U.S. perm/tech demand, Experis margins failing to expand despite higher utilization, or enterprise AI spending shifting from services-heavy deployments to packaged automation.
Contrarian view: persistent demand for human implementation capability is more bullish for labor intermediaries than for enterprise-software multiples. The market has largely priced AI as a labor-cost deflation story; evidence that adoption requires complementary skilled labor would favor staffing/consulting earnings durability, but MAN needs reported conversion before the thesis merits a material position.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Ticker Sentiment
Key Decisions for Investors
- Maintain MAN as a watch-list long rather than initiate on this release; add only after Q4 results show Experis organic growth stabilizing and segment margin expansion. Target a 3-6 month rerating from mix improvement; exit if U.S. demand commentary deteriorates or group guidance is cut.
- Prefer a 6-12 month pair trade long ASGN / short MAN if AI-specialist requisitions accelerate: ASGN offers more direct U.S. technology-staffing sensitivity, while MAN retains greater exposure to cyclical general staffing. Reassess if ASGN utilization or bill rates decline for two consecutive reported quarters.
- For offshore implementation exposure, accumulate GLOB on weakness over 3-6 months rather than chase broad AI software beta. The thesis requires improving bookings and stable delivery margins; invalidate on meaningful wage-driven margin compression or a material reduction in North American discretionary spending.
- Do not treat ISC as actionable from this datapoint: the survey provides no verifiable linkage to ISC revenue, contract volume, or AI-related monetization. Set an alert for disclosed technology-services backlog or bookings data before assigning a directional position.
More News
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- BOJ expected to hike rates by 25 basis points to fresh three-decade high: CNBC survey
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- U.S. stock futures drift higher with Fed rate hike in focus
- Americans' incomes rose and poverty fell in 2025, Census Bureau says
- AWS says it can't restore service to Bahrain, UAE facilities 6 months after Iran strikes
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for Family Offices: A Stack by Decision Type
- Reading Conviction in the Tape: What Level 3 Order Book Data Really Tells Discretionary PMs