
Galaxy Announces Third Quarter 2026 Financial Results
Source: PR Newswire
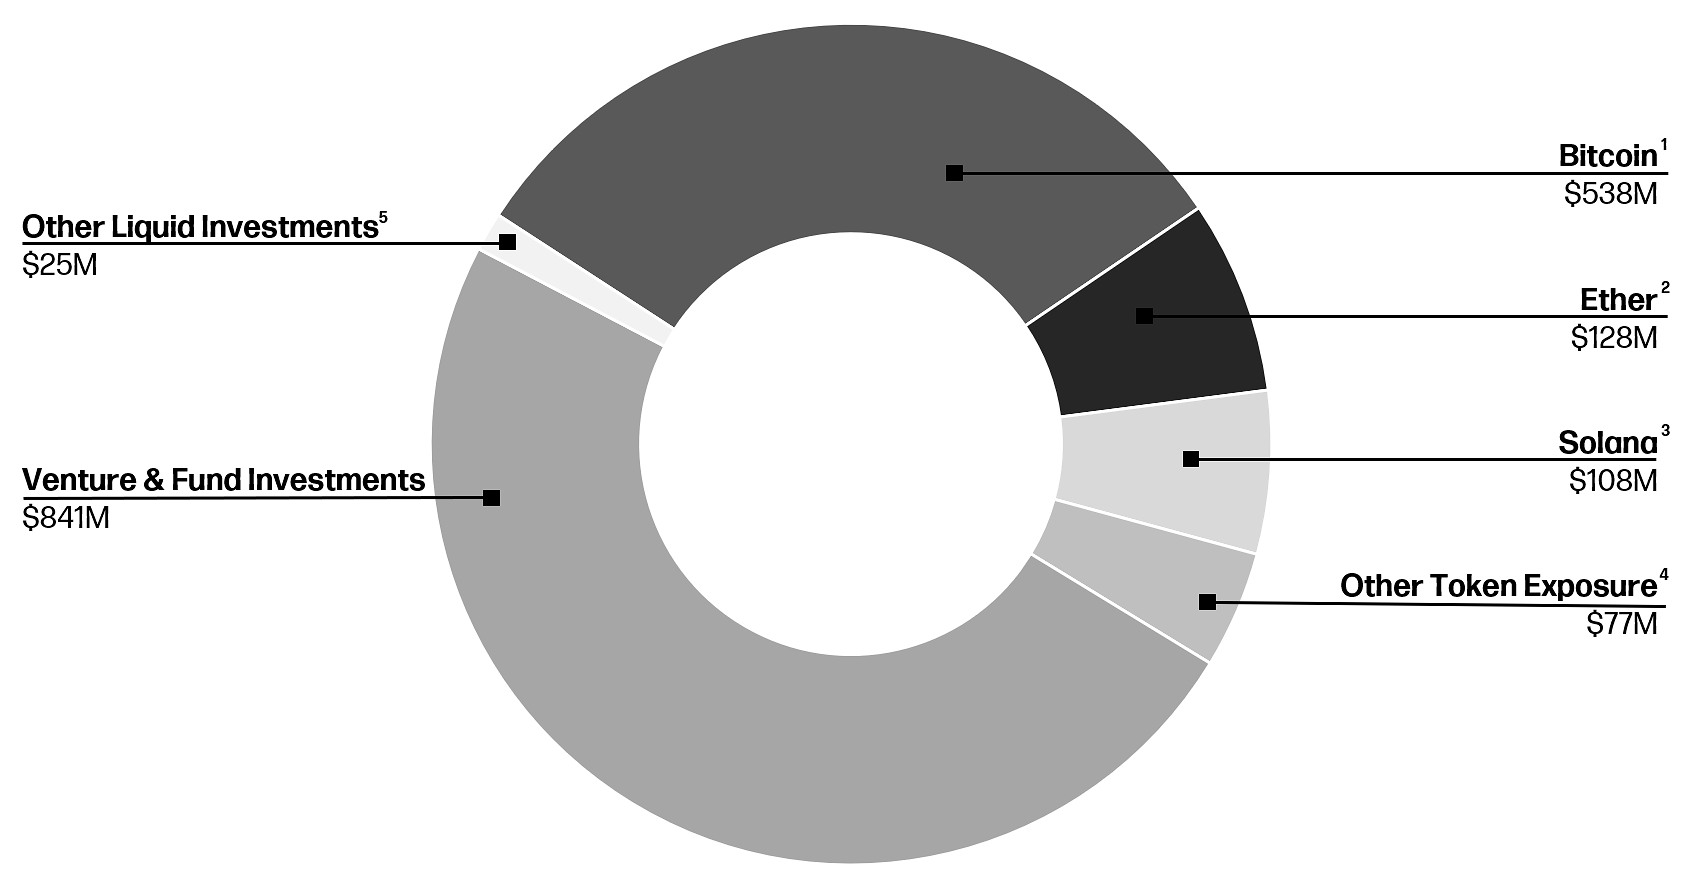
Galaxy Digital reported Q3 2026 net income of $323 million, adjusted EBITDA of $455 million and adjusted EPS of $0.83; adjusted EBITDA compares with a $77 million loss in Q2. Data Centers adjusted EBITDA rose to $69 million from $11 million, while the company’s gross power pipeline exceeded 5.7 GW and Helios I, Phase II construction remained on schedule and within budget. The board authorized up to $200 million in additional share repurchases after the company repurchased approximately 9.8 million shares year-to-date.
Analysis
The key quality-of-earnings issue is that the quarter’s $455M adjusted EBITDA was dominated by Treasury & Corporate ($395M), while Digital Assets remained EBITDA-negative and Data Centers contributed $69M. The headline therefore overstates the run-rate improvement in operating businesses: portfolio marks and other investment performance can reverse quickly, whereas data-center cash generation is still ramping. The 133 MW operating lease is useful execution evidence for GLXY and indirectly supports CRWV’s demand validation, but it does not remove tenant-concentration risk or establish economics for the unleased Helios II capacity.
The strategic upside is a potentially valuable mix shift toward contracted infrastructure revenue. The offset is financing and delivery risk: data-center liabilities rose faster than assets, and the $3.5B secured-note financing increases sensitivity to construction delays, power approvals, and lease-up. Near term, the market may reward reported earnings and buyback authorization; over 1–3 months, focus on lease announcements, project milestones, and operating cash flow rather than the 5.7 GW pipeline headline. Over 6–18 months, execution and incremental financing terms determine whether infrastructure merits a durable valuation premium. BNY may benefit from institutional staking adoption, but the agreement’s financial contribution is not quantified.
Contrarian risk: investors may capitalize a volatile treasury-driven quarter as if it were recurring infrastructure earnings. Also, adjusted EPS uses a materially broader share base than GAAP diluted EPS, so per-share comparisons require care. A reversal in digital-asset prices could hit reported results while construction spending and debt service persist.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.68
Ticker Sentiment
Key Decisions for Investors
- Do not chase GLXY solely on the earnings headline. Treat Treasury & Corporate’s $395M adjusted EBITDA as volatile; verify the segment’s composition and cash conversion in the 10-Q and earnings call before underwriting it as recurring.
- For a relative-value expression, consider short GLXY versus long BTC only if GLXY materially outperforms on the print while digital-asset prices and operating metrics do not confirm the move. This isolates potential multiple/earnings over-extrapolation, while retaining crypto exposure; cut the hedge if GLXY demonstrates sustained data-center cash generation or secures meaningful additional leases.
- Track Helios II lease-up, construction milestones, ERCOT power approvals, and financing terms over the next 1–3 months. Delays, cost overruns, or weaker lease economics would undermine the infrastructure-premium thesis; on-time delivery and contracted capacity would strengthen it.
- CRWV’s role as the existing tenant provides operational validation but also creates counterparty concentration for GLXY. Monitor lease disclosures and tenant credit signals; do not infer broader GLXY tenant demand from the current delivered capacity alone.
- BNY’s staking/platform agreement is strategically supportive but not yet a measurable earnings catalyst. Keep it on watch pending disclosed adoption, assets, or revenue contribution rather than initiating a trade on the partnership announcement.
More News
- Meta, SpaceX, Anthropic stoke the AI funding frenzy. What it means for our stocks
- Elon Musk warns more than 200 AI cloud companies face ‘guppy-level death’ as the AI boom runs into a debt crisis
- General Compute raises $100 million Series A, countering the neocloud disaster narrative
- As AI becomes more fractured, one names stands out: AMD
- Cramer: I asked some tech insiders what to buy. They surprisingly said this drug stock
- Why are CoreWeave and Nebius stocks rising 4% on Tuesday?