
Pavlus Travel & Cruise Identifies Fast-Evolving Trends in Global River Cruising.
Source: PR Newswire
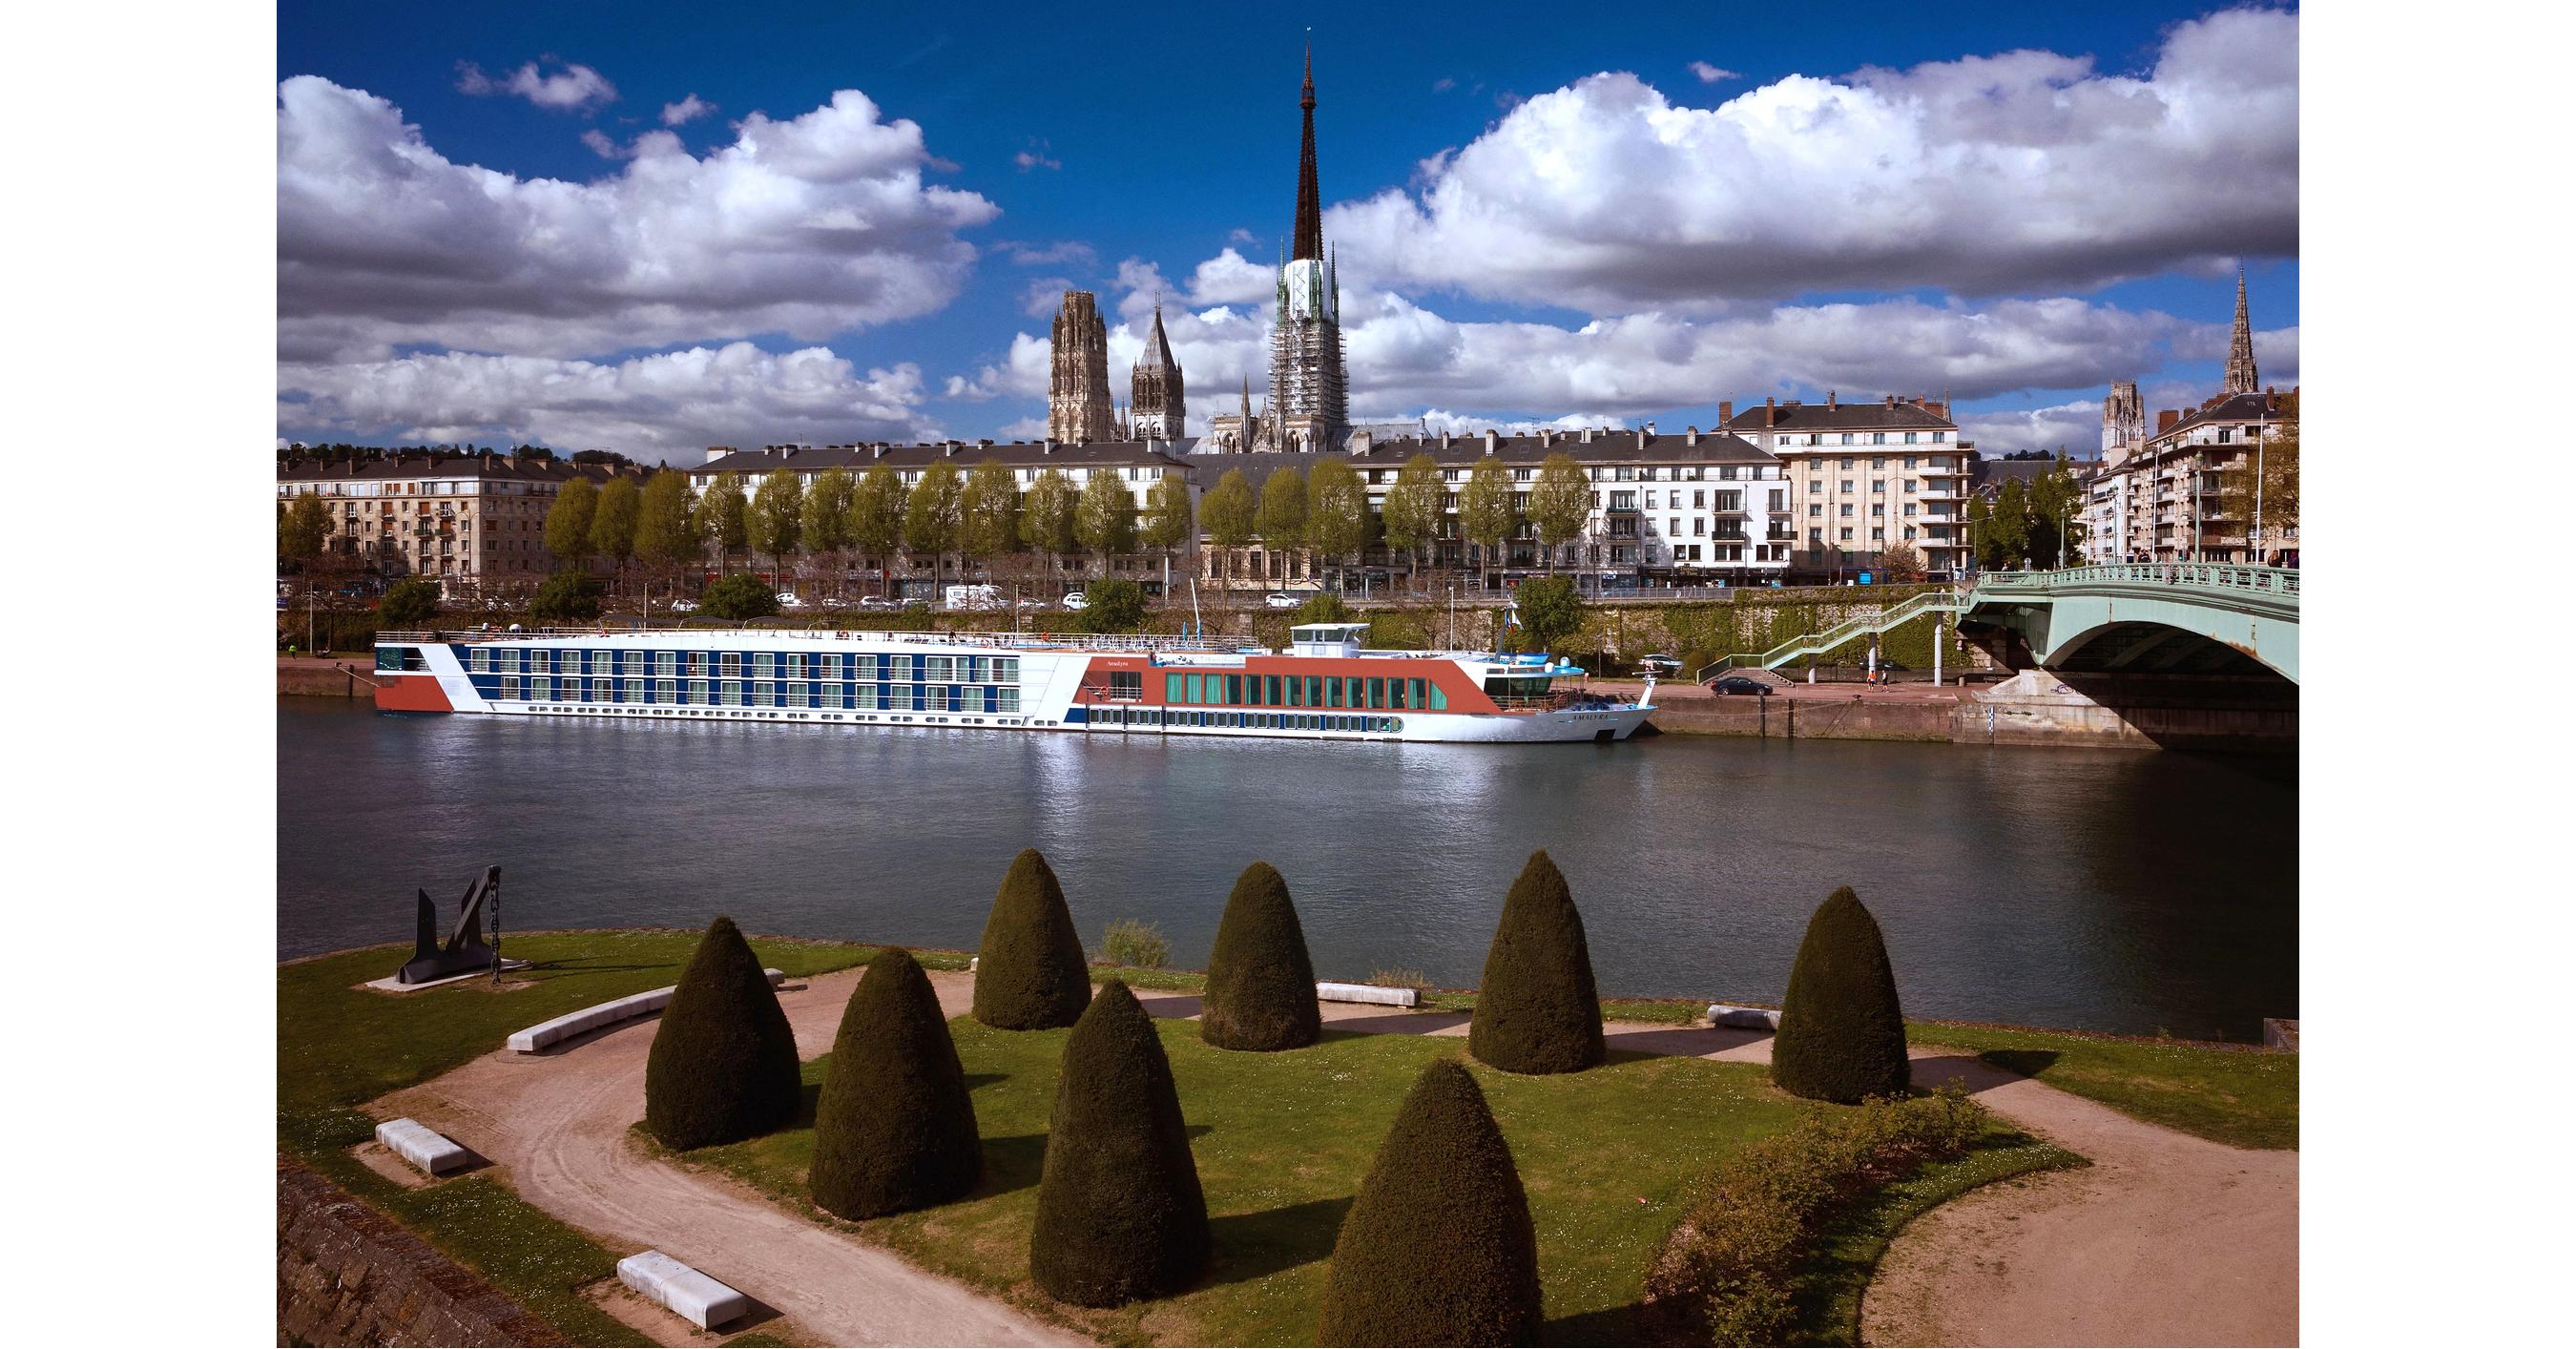
Pavlus Travel & Cruise says demand for river cruises is growing, with younger and first-time cruise travelers increasingly considering the segment; river cruising represents about 7% of overnight cruise capacity, with approximately 61,000 berths versus roughly 776,000 for ocean cruising. The agency points to at least 25 new river vessels expected to launch in 2027, alongside new routes, wellness options, and cruise-and-land itineraries. The article is an agency’s industry outlook and does not report company financial results or market reactions.
Analysis
The signal is strategically positive for Viking (VIK), but weak as a near-term earnings catalyst: the evidence is a luxury agency’s customer anecdotes and industry plans, not disclosed bookings, yields, or margins. The key market mechanism is product mix, not simply more berths. If younger and first-time guests extend trips with land packages and pay for active or culturally immersive excursions, VIK may gain ancillary spend and customer lifetime value; that benefit depends on attach rates and pricing, neither of which is established here.
The competitive read-through cuts both ways. Celebrity’s planned entry validates demand but raises the risk that established ocean brands use distribution and loyalty ecosystems to compete for premium customers. The announced 2027 ship wave could broaden choice while pressuring occupancy, itinerary quality, and pricing—especially if demand is concentrated in a few navigable rivers. Low water, route disruption, or weak execution on newer itineraries could expose the difference between headline capacity growth and usable capacity.
Contrarian view: a small starting market is not proof of a large profit pool. The release is promotional, and agent inquiries are not conversion or revenue data. Near-term share reaction may be limited; the more relevant 1–3 month checks are VIK booking commentary, pricing/yield trends, and river-specific capacity utilization. Over 6–18 months, successful launches and land-package attachment could support a differentiated premium narrative; excess supply or discounting would reverse it. Starlink is mentioned as an amenity enabler, but no material SpaceX (SPCX) revenue implication can be inferred.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- Do not trade the release alone. Treat VIK as a watchlist-positive; seek confirmation in booking pace, realized pricing, and management commentary on river demand before adding exposure.
- For the next 1–3 months, monitor VIK’s disclosed yield/occupancy trends and any booking updates, plus Celebrity’s launch details. Falsify the demand thesis if guidance or pricing weakens as new capacity approaches.
- For 6–18 months, track 2027 launches against utilization and discounting. A broad capacity ramp without sustained pricing would shift the read-through from category validation to competitive overbuild.
- Avoid inferring a direct earnings catalyst for RCL from Celebrity’s planned entry until investment, launch timing, and returns are quantified; the article provides no comparable support for NCLH or SPCX.
More News
- SpaceX Seeks $40B for Nvidia Chips as AI Megadeals Loom
- Cruise sector outlook: Carnival, Royal Caribbean and Norwegian compared
- FOMC minutes ahead; Constellation Brands reports - what’s moving markets
- OpenAI dots inspire open source imitators amid technical difficulties
- Bloomberg Intelligence: SpaceX in Fundraising Talks (Podcast)
- Asia shares subdued, bonds swamped by AI debt wave