
DCK organiza dos lanzamientos de productos en línea para Europa en 2026
Source: PR Newswire
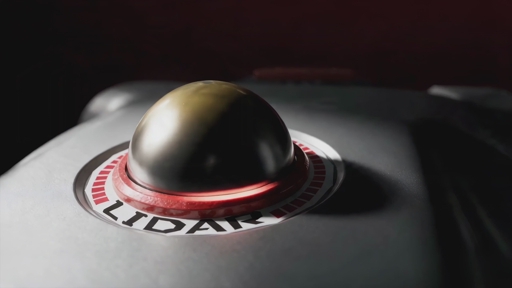
DCK launched two European online product events in September 2026, unveiling 14 new products across heavy-duty power tools and lawn-and-garden equipment. The range includes seven professional tools for fastening, cutting and drilling, plus seven garden products including robotic mowers with precision navigation, obstacle avoidance, app control and smart-home connectivity. The launches support DCK's effort to expand its European presence through electrified and intelligent tool solutions.
Analysis
This is not independently investable news, but it marginally reinforces a broader competitive threat: Chinese power-tool manufacturers are moving beyond value-priced corded tools into battery ecosystems, robotic outdoor equipment and connected devices. The near-term effect on listed incumbents is likely negligible; the relevant issue is whether DCK can secure European retail/distribution shelf space and comply with product, battery and after-sales-service requirements. Those bottlenecks, rather than product-launch marketing, determine whether price competition becomes material.
Over 6-18 months, the most exposed category is entry-level/prosumer outdoor power equipment, where cordless platforms create repeat battery and accessory revenue but also lower switching costs for consumers. Stanley Black & Decker (SWK) and Techtronic Industries (TTNDY) have greater exposure to promotional pricing in mass retail; Husqvarna (HSQVY) and Deere (DE) are more insulated through dealer networks, installed-base service and premium autonomous mowing positioning. A successful low-cost robotic mower entrant could pressure category ASPs before it meaningfully affects incumbent unit volumes.
The contrarian read is that the launch could validate demand for electrified garden equipment without changing industry profit pools. European channel inventory, replacement cycles and compliance/service investment are the gating data; absent evidence of distributor wins, retail listings or material price gaps versus Ryobi, Bosch, Makita and Husqvarna, this is a watch item rather than a catalyst. Thesis turns more negative for incumbents only if EU retailers begin broad private-label/DCK assortment expansion ahead of spring 2027 selling season.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No standalone trade on this release; set a 1-3 month channel-check alert for DCK European distributor agreements, Amazon/major DIY retailer listings and advertised price points versus Ryobi, Bosch and Husqvarna.
- Maintain a watch on SWK for 2027 outdoor-tool gross-margin risk: reassess if management guides to higher promotions, lower cordless-tool pricing, or North American/European DIY inventory rebuilds below expectations. The release alone does not justify a short.
- For a defensive sector expression over 6-18 months, prefer dealer/service-moat exposure in HSQVY over mass-retail tool exposure in SWK, contingent on evidence that low-cost robotic mower offerings reach European shelves. Falsify if HSQVY maintains robotic-mower ASPs and margin while entry-level competitor penetration remains limited.
- Monitor TTNDY’s European revenue growth and gross-margin commentary through the next two earnings cycles; a combination of weak sell-through and margin pressure would support a tactical short or SWK/TTNDY relative-value review, while stable premium cordless growth invalidates the competitive-disruption thesis.
More News
- South Korea’s exports hit record high on AI boom
- In photos: China's Xi hardens Taiwan warning as country celebrates week-long National Day holiday
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- Asia stocks rise on chipmaker gains, soft U.S. inflation; Nikkei outperforms
- We're raising our Micron price target after an incredible quarter and robust guidance