
BUUU Group Limited Signs Definitive Agreement to Acquire Majority Stake in Brightray Science Inc. and Over US$60 Million of Private Placements, Making Industrialized AI Data Center Delivery Its Core Growth Business
Source: PR Newswire
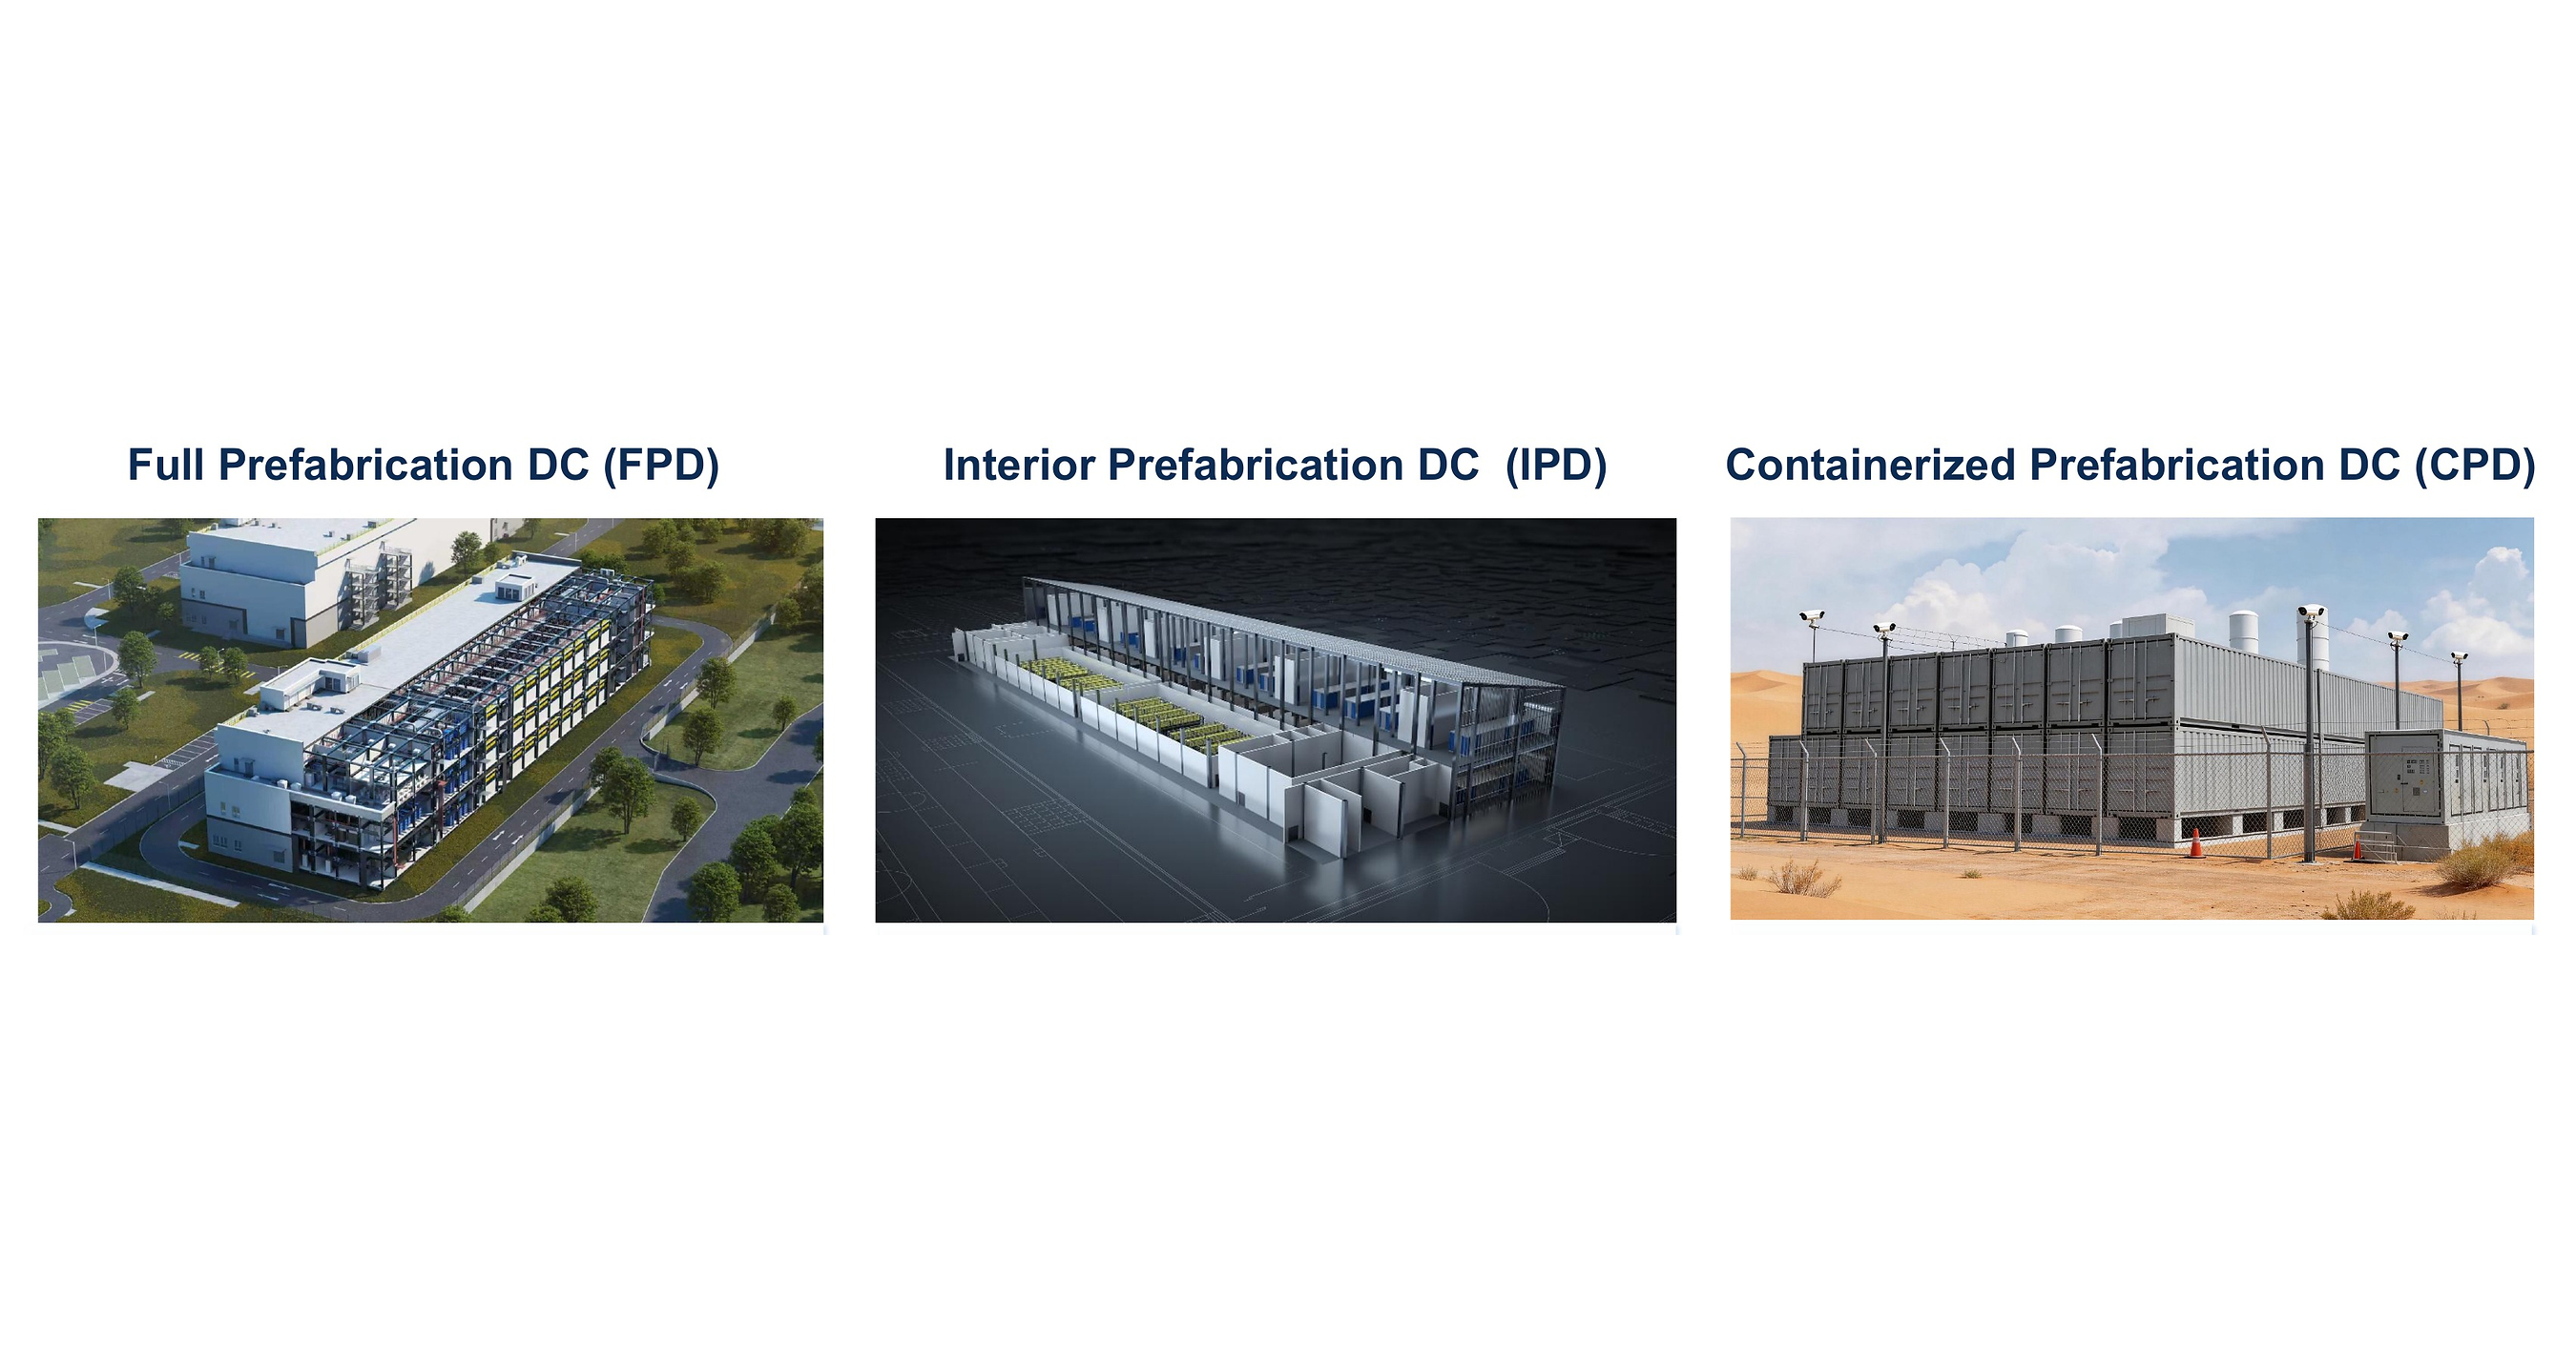
BUUU will acquire a 60% equity stake in Brightray Science in a deal that combines newly issued BUUU Class A shares valued at $20.00/share and a convertible promissory note into up to 10M BUUU shares (with 19.99% ownership limits and performance-based adjustments). The transaction positions prefabricated modular data centers as BUUU’s core AI growth business, citing delivery compression from 18–36 months to six to nine months, with 70MW already in operation in Johor and a target pipeline of ~2GW (~$9B potential contract value). BUUU also secured private placement financing expected to generate >$60M gross proceeds to support capacity expansion and working capital, subject to closing conditions.
Analysis
This is best read as an execution bottleneck trade, not a demand trade. If modular deployment genuinely compresses time-to-revenue, the economic value migrates from land banking and bespoke construction toward whoever can deliver power, cooling and integration at scale; that is a structural headwind for slow-cycle data center developers and a tailwind for prefabrication, switchgear, liquid-cooling and GPU deployment velocity. The market may miss that faster completion is itself a form of customer financing: it pulls forward rent, power usage and chip procurement, which can raise IRRs even if headline capex is unchanged.
Near term, the stock is likely to trade on financing mechanics rather than infrastructure fundamentals. The equity issuance and warrant exercise create dilution overhang, so the first 1-3 months are about whether the PIPE closes cleanly and whether the company can show signed backlog converting into recognizable revenue, not about the size of the pipeline. The key falsifier is any slippage in closing, weak disclosure on customer concentration, or inability to prove gross margin durability once factory utilization rises; that would reprice this from a growth story into a microcap financing situation.
Contrarian view: the consensus will over-attribute strategic significance to a small acquirer because the narrative is strong and the AI theme is crowded. The more important second-order effect is on incumbent custom-build contractors and slower Asia data center developers, who may face margin pressure if hyperscalers increasingly benchmark against prefab delivery times. But for the listed parent, the risk/reward is still asymmetric to the downside unless investors get hard evidence on conversion, not just a large theoretical pipeline.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Do not chase BUUU on the headline; wait for closing and PIPE pricing. If the stock trades >15-20% above the financing reference level before proof of backlog conversion, treat it as a fade candidate with a tight stop.
- Use a small tactical long in NVDA over the next 1-3 months only if the market starts to reprice faster AI deployment cycles; prefer call spreads into earnings rather than outright stock because the thesis is second-order and already partially crowded.
- Watch AMD as a relative beneficiary only if BUUU/Brightray can demonstrate qualification on liquid-cooled next-gen racks; absent that, this is narrative-only and not a high-conviction trade.
- No immediate long in BUUU until there is evidence of revenue conversion and gross margin stability; if post-close quarterly filings show dilution without backlog monetization, shorting any liquidity-driven pop is the cleaner expression.
- Set an alert on the first disclosed contract wins or backlog conversion rate. If management cannot convert a meaningful share of the claimed pipeline within 1-2 quarters after closing, the story likely de-rates sharply.
More News
- Jensen's purchase of a new toy could reshape the entire AI industry
- Taiwan flexes chip diplomacy muscles as it faces pressure to share AI wealth with allies
- Prediction: Data Center Passes 70% of AMD's Revenue in 2027, Before the Helios Ramp Is Finished
- History Says What Nvidia's Last Big Acquisition Became. Hugging Face Will Cost Nearly Twice as Much.
- I Predicted That Lululemon Stock Was In Trouble Ahead of Earnings. What's Next After Its 17% Drop?
- Prediction: Taiwan Semiconductor's Market Value Passes $3 Trillion Before 2029