
Yutong otwiera pierwsze kompleksowe centrum serwisowe w Europie
Source: PR Newswire
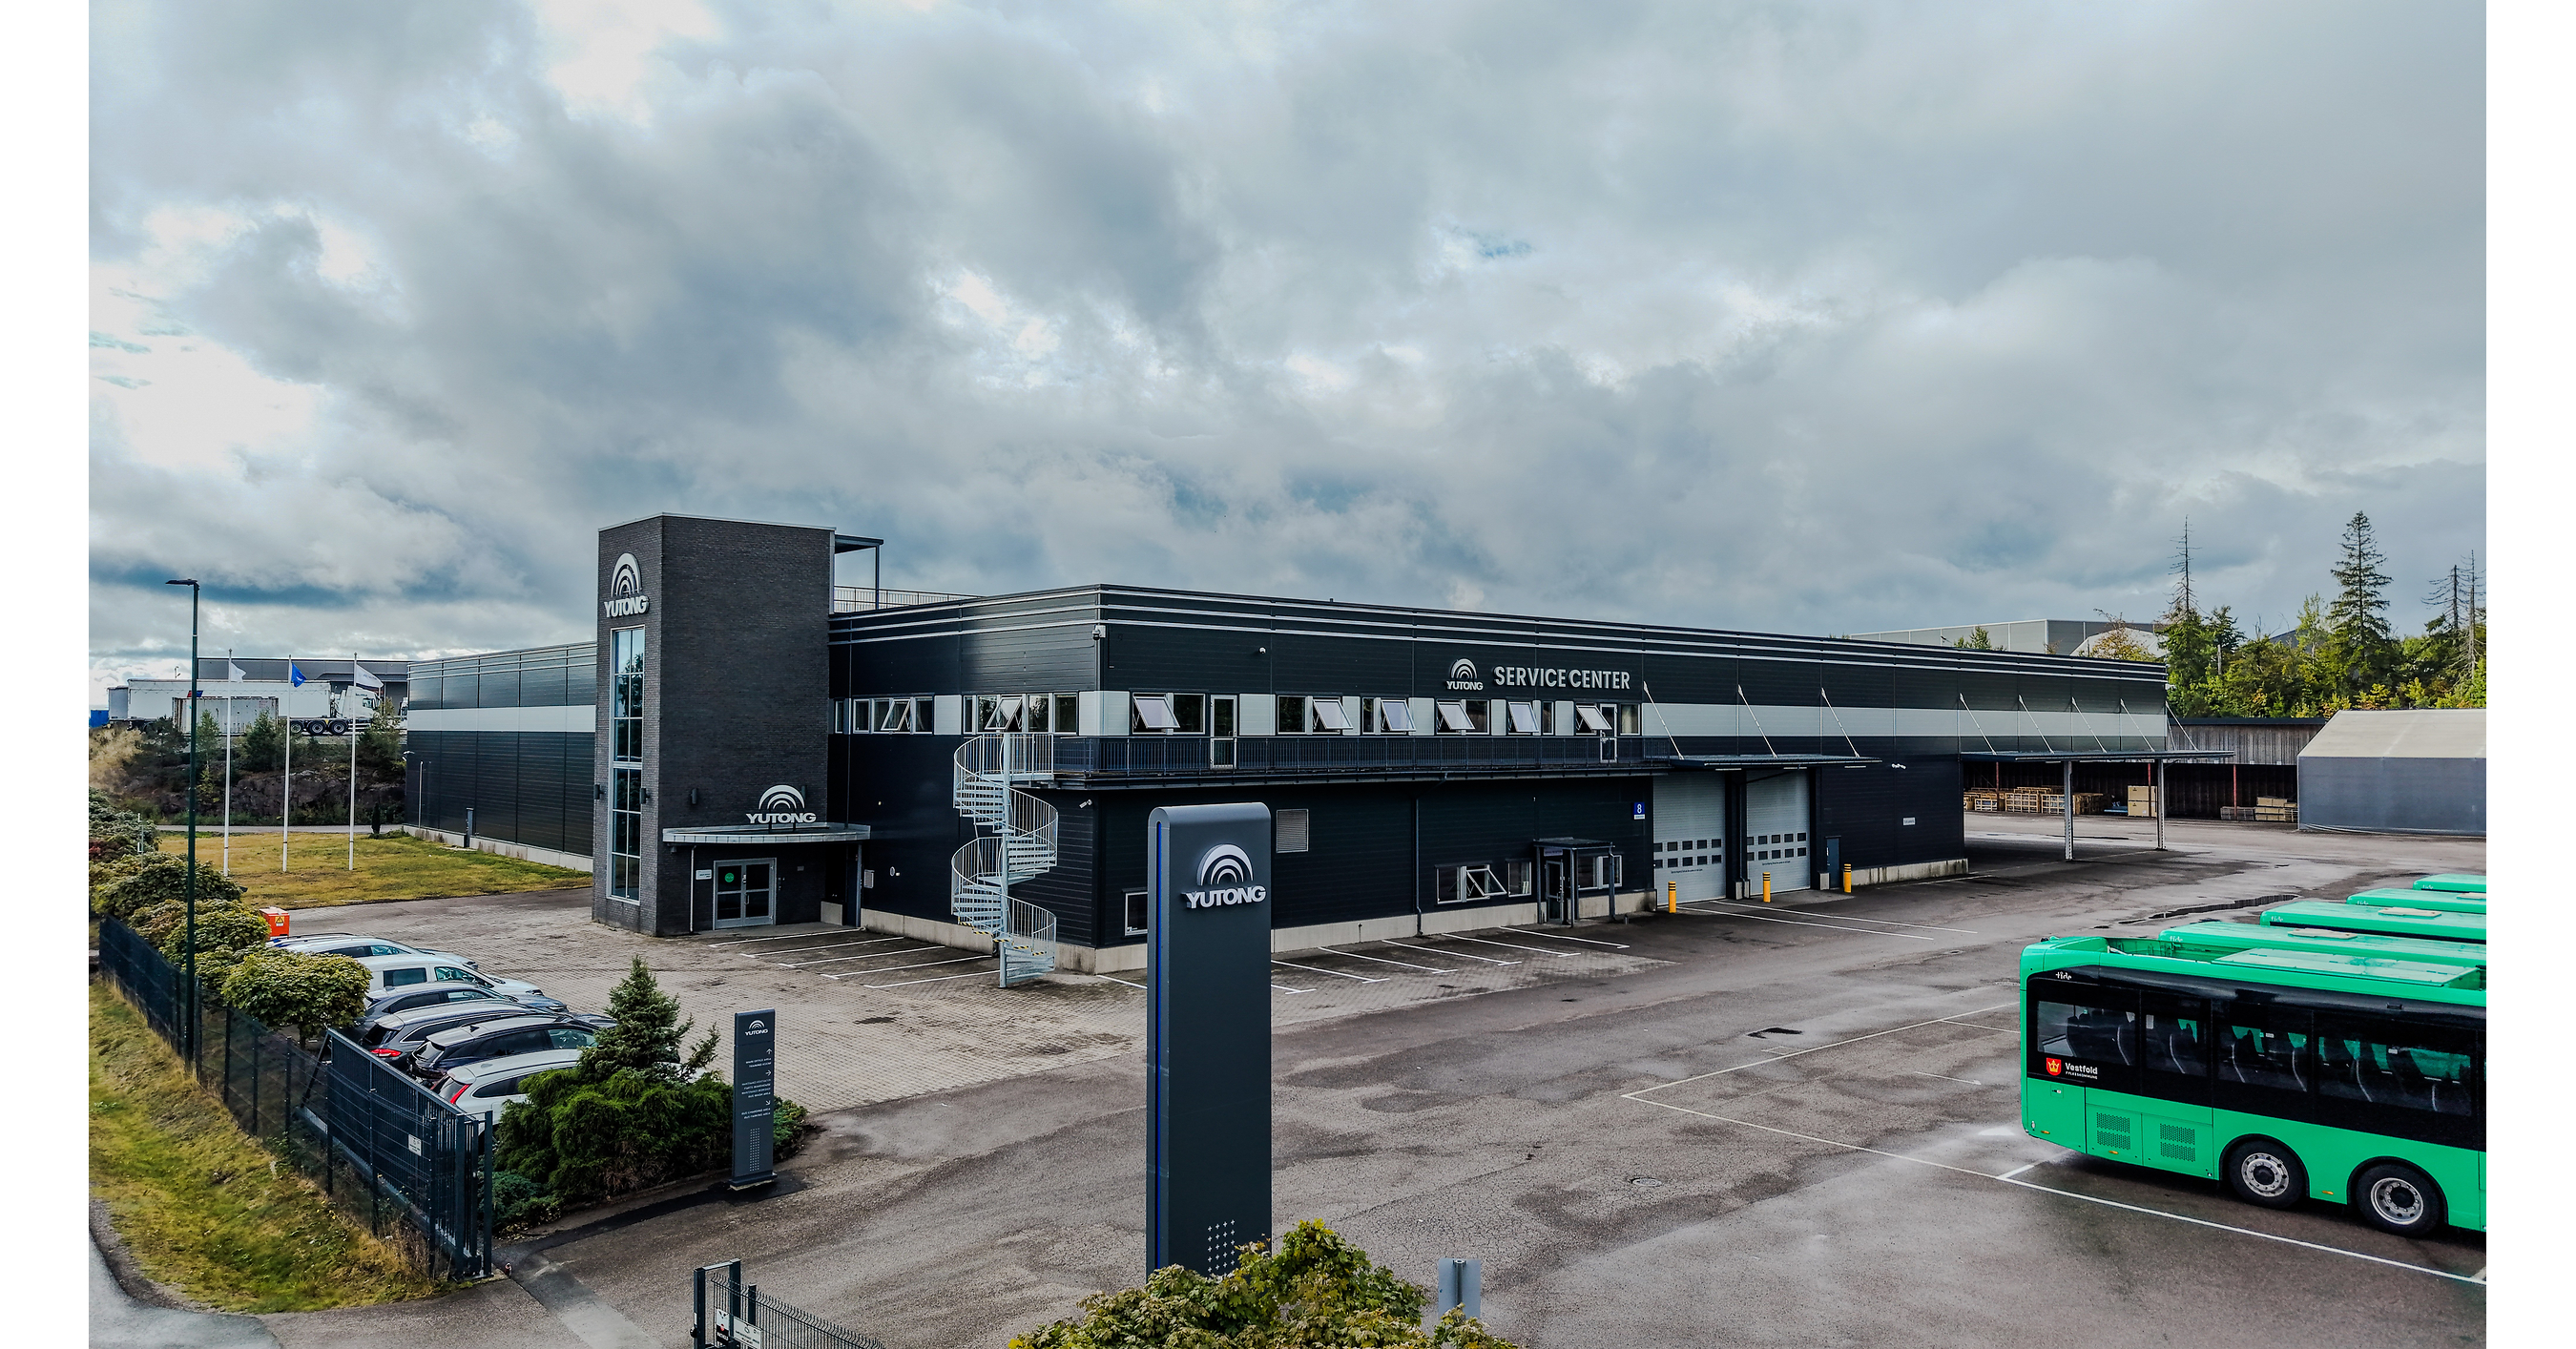
Yutong Bus opened its first comprehensive European service center in Stokke, Norway, supporting electric-bus delivery, maintenance, inspections, parts distribution and technical training. The 38,941 m² site includes 6,074 m² of buildings, a 2,300 m² parts warehouse holding 4,500 SKUs, and seven standard service bays, aiming to reduce fleet downtime and total cost of ownership. Yutong plans to use the Norwegian model to expand localized electric-bus service capabilities in markets including the Netherlands, Chile, Kazakhstan and Saudi Arabia.
Analysis
The strategic significance is not the facility itself but the reduction in procurement friction for European transit agencies evaluating Chinese electric buses. Local parts availability, technician training and compliance capability shift tender decisions from upfront vehicle price toward guaranteed uptime/TCO—an area where incumbent OEMs have historically relied on entrenched dealer networks. If execution is credible, Yutong can convert a low-cost manufacturing advantage into a service-backed bid advantage, pressuring European bus OEM pricing and aftermarket capture in Nordic tenders over the next 6-18 months.
The most exposed listed European pure plays are VLVLY (Volvo Buses within Volvo), DTG.DE (Daimler Truck/Setra) and, more indirectly, TRATON.SE (MAN), particularly where municipal fleet contracts are rebid rather than sole-sourced. The larger second-order issue is aftermarket: a meaningful installed-base gain by Chinese entrants dilutes the high-margin parts and maintenance pool that cushions OEM cyclicality. Conversely, localized service lowers perceived fleet-operating risk and may increase charger, depot-electrification and battery-service demand, benefiting ABB, Schneider Electric and Alfen only if Yutong deployments translate into incremental orders rather than displacement of incumbent buses.
Near term, this is not independently verifiable earnings news and does not justify a directional trade. The 1-3 month catalyst is Norwegian and Nordic tender data: Yutong wins accompanied by multiyear maintenance commitments would validate that service localization is changing buyer behavior. The thesis is falsified if tender win rates remain flat, reported availability/warranty performance lags local OEMs, or EU trade restrictions/procurement-security rules limit Chinese content despite a local service footprint.
Consensus may overstate the moat created by a single hub. Public operators value uptime, but they also face political scrutiny around data, supply-chain security, resale values and long-term battery warranty enforceability; centralized Norwegian inventory does not solve cross-border response times. The more probable initial effect is margin pressure in contested tenders rather than rapid share loss by established OEMs.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No immediate position: treat this as a tender-intelligence alert, not a company-specific catalyst, because Yutong is not directly investable through a liquid listed European equity and the announced facility has no disclosed revenue or fleet-throughput impact.
- Monitor Nordic public-bus awards over the next 3-6 months for Yutong share, contract maintenance terms and availability guarantees; initiate a tactical short DTG.DE or VLVLY only if Chinese OEM tender wins accelerate while award pricing indicates lower service-inclusive bid levels.
- For existing long VLVLY/DTG.DE exposure, track commercial-vehicle aftermarket guidance and European bus order margins through the next two earnings cycles. A downward revision to service revenue, warranty provisions or bus margins is the actionable confirmation signal; absent that, avoid extrapolating from one service site.
- Watch ABB and SU.PA for disclosed Nordic depot-charging orders tied to incremental electric-bus fleets over 6-18 months. Do not buy on this announcement alone; the trade requires evidence that Chinese-bus penetration expands total electrification capex rather than reallocates OEM share.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Iran says won’t allow US warships to get close as Trump ponders new attacks
- Israelis hold final rally against Netanyahu ahead of what may be the most consequential election in the country’s history
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Sudan’s soaring fuel prices make getting by harder for workers
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind Discusses Ontario's AI Economy with Minister Stephen Crawford and Supply Ontario CEO James Wallace
- AI Research Tools for SEDAR+, UK and ASX Filings