
Huawei dévoile une solution innovante de téléprésence immersive offrant des expériences immersives et des services intelligents
Source: PR Newswire
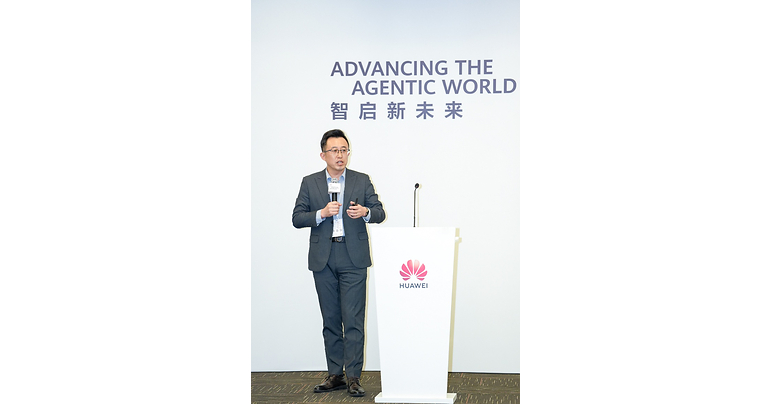
Huawei unveiled an AI-enabled immersive telepresence system at HUAWEI CONNECT 2026, led by its CloudLink Camera 610 panoramic AI-fusion camera and IdeaPresence modular displays supporting 1.07 billion colors. The platform adds AI noise separation, smart meeting-space management, one-click sharing and audio/video watermarking for traceability. Huawei is also opening UI-control, service and hardware-acceleration SDKs to partners, targeting enterprise collaboration, online meetings and OpenHarmony-based connected classrooms.
Analysis
This is unlikely to be a standalone revenue catalyst for public markets: Huawei is unlisted, enterprise collaboration hardware is a fragmented, low-growth category, and the announcement provides no pricing, backlog, channel or deployment evidence. The strategic significance is that Huawei is attempting to bundle endpoint hardware, AI meeting features and an OpenHarmony-based application layer, which can raise switching costs in Chinese public-sector, education and state-owned-enterprise accounts over the next 6-18 months. That is incrementally negative for Cisco (CSCO), Logitech (LOGI) and HP Inc. (HPQ) only where they compete for regulated Chinese collaboration-room budgets; the effect on consolidated earnings should be immaterial absent disclosed large-scale wins.
The more relevant second-order issue is ecosystem bifurcation. A locally controlled collaboration stack can reduce the addressable market for Western videoconferencing and unified-communications vendors in China while increasing procurement friction for multinational firms operating there; this favors domestic Chinese component and integration providers, most of which are not readily investable offshore. Conversely, Huawei's open-SDK framing could pressure dedicated conferencing hardware toward commoditization, benefiting software-centric platforms such as Microsoft (MSFT) and Zoom (ZM) if interoperability remains real rather than a closed distribution channel. Treat the security and AI-performance claims as unverified until customer deployments, recurring software attach rates, or independently reported contract awards emerge.
Near term, there is no reason to expect a material move in listed global peers. Over 1-3 months, watch Chinese enterprise IT procurement data and any announced government, education or SOE rollouts; over 6-18 months, the thesis becomes investable only if Huawei demonstrates software/services monetization rather than one-time hardware sales. The contrarian view is that enhanced room systems may be late to market: hybrid-work buyers increasingly prioritize low-cost interoperability and AI software features, limiting premium hardware pricing and potentially making this a margin-dilutive channel-expansion effort.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No directional trade on the announcement alone; maintain a watchlist rather than shorting CSCO, LOGI or HPQ, as China collaboration exposure is too small and no contract economics are disclosed.
- For portfolios already long CSCO or LOGI, monitor the next two earnings calls for China commercial-order commentary and gross-margin pressure in collaboration endpoints. Reassess only if management attributes a measurable revenue decline or pricing deterioration to domestic Chinese substitution.
- Watch MSFT versus ZM over the next 1-3 quarters as a software-layer relative-value signal: consider long MSFT / short ZM only if enterprise collaboration spending remains resilient while ZM fails to demonstrate AI monetization and net-revenue-retention stabilization. Falsification: ZM reaccelerates enterprise growth or MSFT reports material Teams seat/pricing pressure.
- Create an alert for verifiable Huawei wins in Chinese SOE, education or multinational-campus deployments, including contract value and recurring-service content. A series of disclosed deployments would strengthen the China-exposure risk case for Western endpoint vendors, but not before.
More News
- Trump & Xi to Meet Amidst Friction on Wars, Tech, Trade
- Here are the 3 big things we're watching in the stock market this week
- Tech leads shares higher in Asia, oil eases
- Yuan hits fresh multi-year peak as PBOC eases curb ahead of Trump-Xi summit
- China slows humanoid robot IPO rush as hype outruns reality
- The economy has undergone a structural transformation that ended the low-cost era. ‘The regime change in inflation and interest rates is the outcome’
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Research Tools for Pension Funds and Allocators
- AllMind's Data Standardization Methodology: Our Approach to Fundamentals