
VW Wants to Win Over America’s Wrangler and Bronco Drivers
Source: Bloomberg
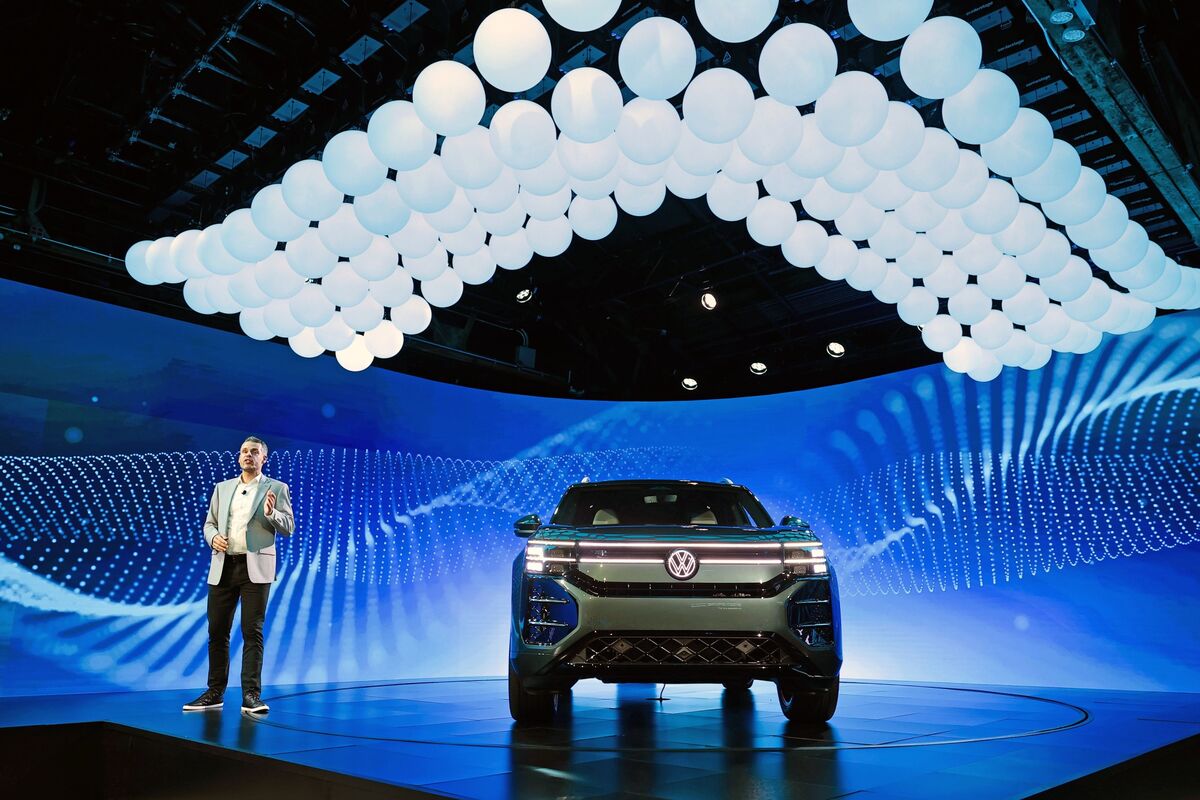
Volkswagen CEO Oliver Blume is looking to grow the company in the US by winning over Jeep Wrangler and Ford Bronco drivers, as VW remains a small player in the American market. The push comes as VW’s China business shrinks and German operations shed tens of thousands of jobs; the article provides no sales figures or details of the US strategy.
Analysis
The investment question is whether a US push can add profitable, durable earnings or merely redirect capital toward a difficult market while China and Europe remain under pressure. Competing for Wrangler and Bronco buyers means more than launching a rugged-looking vehicle: VW would need credible product differentiation, dealer/service reach, and pricing that does not rely on incentives. If those costs rise before sales scale, incremental US volume could dilute rather than improve returns. Ford and Stellantis could face added competitive pressure only if VW delivers a compelling product at scale; the more immediate second-order effect may be defensive discounting in the segment.
Near term, this is a strategy narrative, not evidence of an earnings inflection; the excerpt gives no product timing, investment, or sales targets. Over 1–3 months, watch for concrete launch plans and capital commitments. Over 6–18 months, the test is US share and contribution after incentives, alongside whether investment competes with restructuring or other priorities. Trade-policy shifts and weak US demand could worsen the economics. The contrarian risk is treating US growth as a ready substitute for China: geographic diversification does not guarantee comparable margins or returns. Without verifiable milestones, the signal is too thin for a directional trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.20
Ticker Sentiment
Key Decisions for Investors
- Keep VOW3 on a catalyst watch rather than buying the US-growth narrative. Verify model/launch timing, planned investment, dealer readiness, and any explicit US volume or profitability targets before underwriting earnings upside.
- For the next 1–3 months, monitor VW guidance and disclosures for US orders, market-share gains, incentive levels, and launch slippage. A sales-share increase without evidence of pricing discipline would not validate the thesis.
- Avoid a standalone short solely on this article. If VOW3 rerates on the strategy while subsequent disclosures show delayed launches, rising incentives, or no improvement in US contribution, reassess for underweight/relative underperformance exposure.
- Falsify the cautious view if VW demonstrates sustained US demand with controlled incentives and confirms the required investment can coexist with restructuring; worsening China results or trade-policy costs would strengthen it.
More News
- VW plans global pay freeze to 2030 for 660,000 staff; works council vows resistance
- Volkswagen Q3 Deliveries Fall 14.3% as China Sales Slump
- Strategy buys another $22 million of Bitcoin, increases planned share buybacks
- Credit stress is threatening to unwind the AI bull. All eyes are on Oracle to hold the line
- Amazon to fund 12 small nuclear reactors at former Indiana coal plant
- Inside a Packaging Industry Mega-Deal