
POWERCHINA Advances Wind Power and Energy Storage Development to Support Egypt's Sustainable Energy Transition
Source: PR Newswire
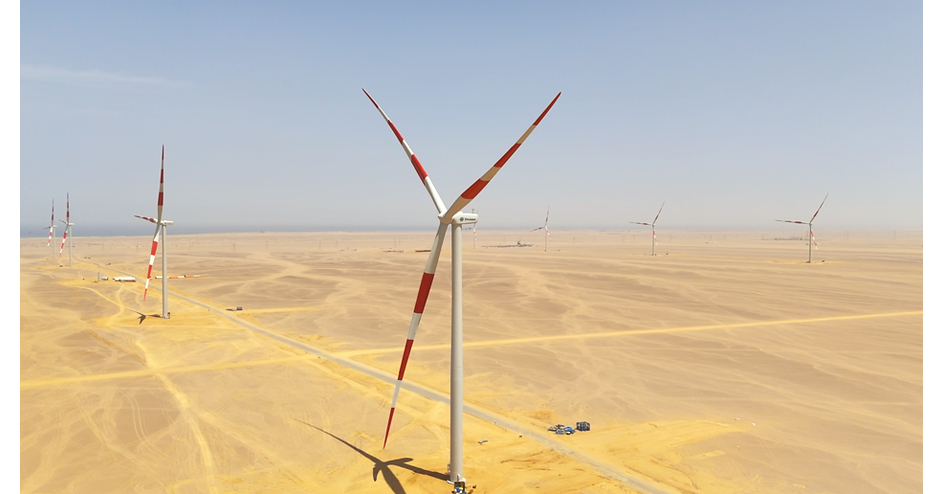
POWERCHINA is expanding its Egypt clean-energy footprint with a wind portfolio totaling 1.8GW+ and adding energy storage infrastructure, including construction of a Sungrow battery energy storage manufacturing facility in Ain Sokhna (50,000 sq. m.) started in August 2026. The company highlights operational 500MW Amunet Gulf of Suez Wind (with earlier-than-contract project acceptance and a 2025 RoSPA H&S award) plus two under-construction wind projects: 1.1GW Gulf of Suez and 202.5MW Ras Ghareb. Overall tone is supportive of Egypt’s renewable buildout and local supply-chain development, but the release appears more corporate/operational than financially market-moving.
Analysis
This reads less like a one-off project update and more like evidence that Chinese industrial players are exporting a bundled renewables stack: EPC, equipment localization, and operating know-how. The market implication is that value migrates upstream to manufacturers with service/install capability and local-content leverage, while pure contractors and import-dependent suppliers see margin compression as buyers push for cheaper, financed, in-country solutions.
The second-order effect is on the regional clean-energy supply chain, not just Egypt. Local battery assembly can shorten delivery cycles and reduce FX/friction costs, which is bullish for volume conversion in storage over 6-18 months, but it also raises the bar for competitors that lack a local footprint. That is more supportive for large Chinese OEMs with balance-sheet depth than for small U.S./European clean-tech names that need export financing to compete.
The bigger risk is that frontier-market execution issues show up late: sovereign payment delays, currency convertibility, grid interconnection bottlenecks, and desert O&M costs. Those are months-to-years problems, not day-one catalysts; if Egypt’s macro or policy backdrop weakens, the announced localization story can stall before it becomes recurring revenue. This is why the move should be treated as incremental positive sentiment, not as proof of durable earnings uplift.
Contrarian view: consensus may be overestimating how much this helps public clean-energy equities. Much of the economics may accrue to private Chinese OEMs and local contractors, while listed proxies remain underappreciated only if they have real MEA backlog conversion. Absent that, this is more of a watch item than a thesis-changing event.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- No immediate trade in CETY or PGPGF: the article does not provide enough evidence of direct revenue or backlog sensitivity; keep both on watch for follow-on disclosures only.
- Watch for a 1-3 month confirmation signal from MEA storage orders and utilization data; if export order flow appears, express it through a diversified clean-energy basket like ICLN rather than a single small-cap name.
- Set a risk alert on Egypt sovereign spreads / FX stress: if payment risk widens or project timing slips, fade the localization narrative by reducing exposure to renewables infrastructure proxies.
- If forced to express the theme, prefer a small tactical long in ICLN on pullbacks with a tight exit if project execution commentary deteriorates; risk/reward is better than chasing headline momentum.
More News
- Christine Lagarde, Boris Vujčić: Monetary policy statement
- Wall St set for lower open after hotter-than-expected producer inflation data
- Oil Hits $105 as Iran Shows No Signs of Backing Down
- Nasdaq invests $100 million in Kraken parent, eyeing 2027 launch of 'tokenized' stock trading
- ECB hikes rates as Iran war adds to inflation angst
- Stocks Waver Ahead of PPI, Earnings, Brent Hits $102, Trump Vows Midterm Payout to Voters