
Waste Management: Turn America's Trash Into Your Treasure
Source: seekingalpha.com
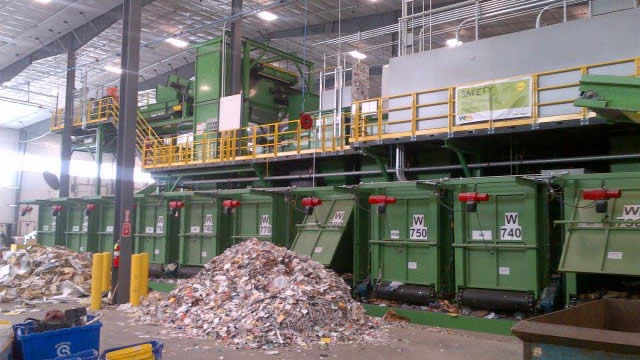
Waste Management is described as a dominant North American environmental services provider, with essential services, pricing power, automation, and vertical integration supporting resilient cash flows and margins. Adjusted diluted EPS is projected to compound at 10.3% annually through 2028. At $228, shares trade at 27.8x forward earnings versus a $230 fair value estimate, implying modest upside; dividend growth is described as continuing at 10%.
Analysis
The positive thesis is less about demand growth than the durability of pricing relative to cost inflation. That can support resilient earnings, but the key test is whether realized price increases continue to exceed labor, fuel, maintenance and disposal-cost inflation without driving meaningful volume loss. Automation could widen the advantage over less-integrated operators, though the payoff depends on realized productivity gains net of implementation and maintenance costs—not announced investment alone.
At the cited $228 price, the article’s $230 fair-value estimate leaves little valuation cushion. The projected EPS compounding and dividend growth are estimates, not independently demonstrated outcomes here. A defensive business can still suffer multiple compression if rates rise or investors rotate toward cyclicals; a small valuation gap does not protect against that. In the next 1–3 months, focus on price-versus-volume trends, margins and cash conversion. Over 6–18 months, the structural question is whether automation improves unit economics enough to sustain pricing and shareholder returns after capital spending.
Contrarian angle: essential-service characteristics may be well recognized, while the market may underweight execution and reinvestment risk. Conversely, if pricing remains firm and automation produces verifiable cost savings, the estimate could prove conservative. No high-conviction outright trade is supported without current operating results and valuation context versus peers.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.38
Ticker Sentiment
Key Decisions for Investors
- Avoid chasing WM solely on the dividend-growth and EPS-compounding estimates; at the article’s cited valuation, the stated fair value offers little margin of safety.
- Watch the next earnings release for realized pricing versus volume, operating margin, free-cash-flow conversion after capital spending, and quantified automation productivity. These are the evidence needed to validate the thesis.
- Consider initiating or adding to WM only on a material pullback, or after results confirm pricing durability and productivity gains; size the position as a defensive compounder rather than a near-term catalyst trade.
- Falsify the positive thesis if price increases no longer offset cost inflation, volumes weaken materially, cash conversion deteriorates as investment rises, or guidance is reduced. Reassess valuation risk if long-term rates rise and defensive-equity multiples compress.
More News
- Elon Musk says SpaceX and Tesla exploring largest merger in history
- Australian data center operator NextDC's shares plunge 40% after it slashes earnings forecast
- Asia stocks rebound as SpaceX, Super Micro results lift chipmakers
- Exclusive-Samsung, SK Hynix upgrading China plants to make more advanced chips, people say
- Neoclouds Lose Silver Lining as Elice, CoreWeave Dive: Evening Briefing Americas
- Elon Musk says Tesla and SpaceX are weighing a $3.5 trillion merger—without him in the room